



PW Consulting: Blood Products Market to Hit $66.2M by 2032, Reflecting 4.7% CAGR Amid Regional Shifts

Strategic Intelligence for Blood Products Leaders: Navigating the 2026 Market Landscape
Executive Overview
The global blood products market is entering a critical inflection point. With historical momentum carrying the industry from 38.15 billion USD in 2020 to an estimated 48.0 billion USD in 2025, and a projected trajectory toward 66.2 billion USD by 2032, the sector is poised for sustained, measured expansion. Our newly released research framework dissects this evolution with precision, delivering the analytical depth required for enterprise-level strategy, capital allocation, and competitive positioning in the coming cycle.
For executives, investors, and operational leaders, the years ahead will not be defined by simple top-line growth. Instead, success will hinge on understanding structural shifts in donor economics, reimbursement architectures, regulatory cadence, and manufacturing capacity deployment. This report is engineered to translate macro trends into actionable intelligence, allowing decision-makers to stress-test strategies against realistic demand scenarios, supply constraints, and competitive maneuvering.
The 2026–2032 Trajectory: A Market Built on Stable Demand, Shaped by Execution
The forecast window reflects a compound annual growth rate of 4.7 percent, a figure that signals resilience rather than volatility. Demand fundamentals remain anchored in clinical necessity: surgical interventions, trauma response, oncology protocols, and chronic hematologic management continue to drive consistent consumption. Yet growth is no longer a passive outcome of population aging or procedural volume alone. It is increasingly contingent on operational efficiency, fractionation throughput, cold-chain integrity, and the ability to scale plasma-derived therapies without compromising quality or compliance.
Notably, the projection curve does not follow a linear stretch. The data anticipates a period of consolidation and recalibration, where capacity investments, regulatory approvals, and donor recruitment dynamics will differentiate high-performing players from those merely riding baseline demand. Companies that align manufacturing footprints, collection networks, and product portfolios with regional healthcare financing models will capture disproportionate value. Those that rely solely on historical utilization patterns will face margin compression, supply bottlenecks, or competitive displacement.
Our analysis maps these inflection points across the full forecast horizon, isolating the operational levers that determine whether volume growth translates into sustainable profitability. The report does not stop at aggregate figures; it examines how pricing structures, procurement consolidation, and clinical adoption pathways interact to shape realizable revenue in each phase of the cycle.
Decoding the Competitive Arena: Integrated Networks, Specialized Technologies, and Strategic Capacity Plays
The competitive landscape is defined by a mix of vertically integrated plasma manufacturers, specialized technology providers, and large-scale blood services organizations. Each group occupies a distinct strategic position, and the dynamics between them are shifting as capacity investments accelerate and pathogen reduction technologies gain broader clinical adoption.
Grifols and CSL Behring continue to anchor the upper tier of plasma-derived therapies, leveraging vertically integrated collection and fractionation networks to supply hematology, critical care, and rare disease portfolios. Their scale advantages are counterbalanced by the operational complexity of maintaining donor throughput, fractionation yield, and regulatory compliance across multiple jurisdictions. Terumo Blood and Cell Technologies, meanwhile, operates at the intersection of automation and component production, providing apheresis platforms, processing systems, and storage technologies that influence how blood centers and hospitals manage collection efficiency and product consistency.
On the services and distribution side, Vitalant exemplifies the large-scale U.S. blood services model, delivering whole blood, platelets, plasma, cryoprecipitate, and specialty products across hospital networks. Its operational footprint highlights the importance of regional supply resilience, donor engagement, and logistics optimization in a market where inventory management and shelf-life constraints remain perennial challenges.
Specialized technology and plasma-focused players add another layer of strategic complexity. Cerus Corporation’s pathogen reduction systems address a persistent vulnerability in transfusion medicine, inactivating viruses and bacteria in platelets and plasma to enhance safety margins. Octapharma, Biotest, and Kedrion Biopharma each emphasize plasma-derived medicines and collection infrastructure, with product portfolios spanning coagulation factors, immunoglobulins, and therapies for rare and chronic conditions. Their strategies illustrate a broader industry pattern: differentiation is increasingly achieved through specialized protein fractionation, targeted disease areas, and ownership or control of collection assets.
Recent corporate activity reinforces the strategic stakes. Kedrion Biopharma’s allocation of substantial investment to expand production capacity in Italy signals confidence in regional plasma throughput and fractionation scale. Grifols has moved forward with new manufacturing construction in Spain, reinforcing its commitment toEuropean capacity and supply continuity. Cerus Corporation’s multi-year supply agreement with a major French blood establishment underscores the commercial traction of pathogen reduction platforms in institutional procurement. Additionally, the 2026 International Plasma Protein Congress, held with record participation, reflects intensifying industry focus on plasma protein therapeutics, regulatory alignment, and cross-border supply coordination. Together, these developments illustrate a market where capacity, safety technology, and institutional partnerships are converging as decisive competitive variables.
Operational Realities That Shape Margins: Donor Economics, Reimbursement, and Regulatory Discipline
Behind every market projection lies a set of operational realities that determine whether growth is profitable, sustainable, and defensible. Donor economics remain one of the most consequential cost drivers. In the United States and select markets, donor compensation commonly falls within a range of 50 to 100 USD per visit, and collection-related expenses can represent more than half of finished plasma-derived product costs. This structure means that collection efficiency, donor retention, center utilization, and labor deployment are not back-office concerns; they are direct determinants of cost of goods and margin resilience.
At the same time, hospital reimbursement models introduce a distinct pricing dynamic. Many healthcare systems operate under fixed bundled reimbursement rates for patient care episodes, which encompass blood products as part of hospitalization without separate product-level billing. This architecture compresses direct price visibility for manufacturers and distributors, while shifting commercial emphasis toward reliability, quality assurance, inventory availability, and total cost-of-care efficiency. For suppliers, the implication is clear: competitive advantage arises from demonstrating consistent supply, minimizing waste, and aligning product offerings with clinical pathways rather than pursuing isolated list-price leverage.
Regulatory oversight adds another layer of discipline. Blood establishments are required to register and list products under FDA frameworks, with inspections occurring at least every two years to verify compliance with collection, testing, and processing standards. Updated clinical usage guidance, such as revisions to red blood cell preparation and component handling specifications, further shapes how products are manufactured, stored, and deployed. These requirements elevate the importance of quality systems, audit readiness, and documentation rigor. In practice, they reward organizations that embed compliance into operational design rather than treating it as a periodic checkpoint.
Labor intensity compounds these factors. Plasma collection networks rely on large workforce deployments across hundreds of centers to sustain high-frequency donor operations and fractionation throughput. The operational implication is twofold: scaling capacity requires careful workforce planning, training, and center-level productivity management, while disruptions in staffing or donor availability can quickly propagate into fractionation schedules and supply continuity. The companies that manage these variables most effectively will be best positioned to convert demand into revenue without eroding margins.
Blood Plasma Derivatives Market
What’s Inside the Research: Practical Intelligence for Strategy and Execution
This report is designed as an operational companion for executive decision-making, not a static market snapshot. It integrates demand trajectories, competitive positioning, regulatory context, and cost-structure dynamics into a coherent strategic framework. The analysis spans the forecast period from 2026 through 2032 and is anchored in a historical baseline that captures the market’s evolution from 2020 to 2025.
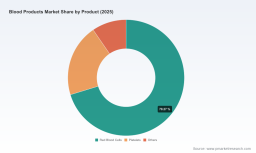
The research delivers detailed segmentation intelligence across product categories, application areas, and regional demand patterns, allowing readers to identify where growth concentrates, where throughput constraints emerge, and where procurement behavior differs by healthcare system. It examines product-level demand drivers, including red blood cell utilization in trauma and surgical care, platelet requirements in supportive treatment protocols, and the broader category of specialty and plasma-derived components. It also maps application-level consumption patterns across trauma and surgery, cancer treatment, and blood disorders, linking clinical utilization to supply planning and commercial strategy.
Beyond volume and segmentation, the report provides actionable competitive analysis. It evaluates the strategic posture of leading manufacturers, plasma collection organizations, technology suppliers, and blood services providers, highlighting how vertical integration, automation, pathogen reduction, and capacity expansion shape market positioning. The competitive framework is paired with recent corporate developments, regulatory milestones, and industry gathering activity to show how strategic intent is translating into infrastructure investment, supply agreements, and institutional partnerships.
A distinct emphasis is placed on operational economics and market mechanics. The analysis addresses donor compensation structures, collection cost weight within finished product economics, hospital reimbursement architecture, regulatory inspection cadence, and the labor footprint required to sustain high-frequency plasma collection and fractionation. These factors are integrated into a broader assessment of margin sensitivity, supply resilience, and procurement behavior, enabling readers to evaluate not just where the market is going, but how value is created and defended along the way.
Blood Products Market
To support practical decision-making, the report also includes scenario-based interpretation tools that help leadership teams test strategic assumptions against changing demand intensity, capacity deployment timelines, and competitive response patterns. The goal is to provide clarity on priorities: where to invest, where to optimize, where to partner, and where to differentiate.
Why This Report Matters for 2026 Decision-Making
The 2026 decision environment demands more than high-level forecasts. It requires an understanding of how donor economics, reimbursement models, regulatory oversight, and capacity investments interact to shape competitive outcomes. It requires clarity on which product and application segments will absorb incremental demand, which regions will see the most pronounced shifts in procurement behavior, and which strategic moves will separate market leaders from followers.
This research is built for that purpose. It provides the structural insight needed to align product strategy, supply chain planning, and commercial positioning with realistic market conditions. It helps organizations anticipate where margin pressure may emerge, where safety technology and compliance rigor will influence purchasing decisions, and where capacity expansion will alter supply dynamics. It also serves as a reference point for investment evaluation, partnership assessment, and long-range planning in a market where execution quality increasingly determines returns.
The full report contains the detailed segmentation breakdowns, regional demand mapping, competitive profiles, operational cost analysis, and strategic scenario interpretation needed to convert market intelligence into concrete action. For teams responsible for portfolio strategy, operations, procurement, or investment planning, the complete dataset and interpretive framework are essential for building resilient 2026 and beyond strategies.
Explore the full research suite to access the complete segmentation intelligence, competitive landscape analysis, and operational dynamics assessment that underpin the findings outlined here.
For detailed analysis of this topic, please visit the official page: Blood Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


