



PW Consulting: Civil Helicopter MRO Market Hits $9.7B in 2025, Projects 6.5% CAGR to 2032

Strategic Intelligence Brief: The Civil Helicopter MRO Market Outlook 2026–2032
The civil helicopter maintenance, repair, and overhaul (MRO) sector stands at a pivotal inflection point as we move into 2026. Driven by accelerating fleet utilization rates, evolving regulatory frameworks, and sustained investment in rotorcraft modernization, the market has transitioned from a post-pandemic recovery phase into a period of structured, high-velocity growth. For executives, investors, and operational leaders across the aviation value chain, understanding the trajectory of this market is no longer optional. It is a strategic imperative.
This analysis serves as a strategic preview to PW Consulting's newly released Civil Helicopter MRO Market Research Report , a comprehensive intelligence asset designed to equip decision-makers with the granular insights, competitive mapping, and forward-looking projections necessary to navigate the next seven years of industry evolution. The following overview highlights the macro-scale dynamics, competitive realities, and regulatory currents shaping the landscape, while demonstrating why this research has become an essential tool for institutional strategy in 2026 and beyond.
Market Trajectory: Sustained Expansion Anchored in Historical Momentum
The civil helicopter MRO market has demonstrated remarkable resilience and consistent upward momentum over the past half-decade. Drawing on a robust historical dataset spanning 2020 through 2025, the sector has recorded steady year-over-year revenue expansion, culminating in a baseline valuation of approximately $9.7 billion in the most recent full-year cycle. This trajectory reflects not only the restoration of civil aviation activity but also the deepening integration of helicopter assets into critical infrastructure: emergency medical services, offshore energy support, law enforcement, and an expanding array of commercial passenger and cargo logistics networks.
Forecasting models projecting through 2032 indicate that this growth will not merely continue but accelerate in structural complexity. The market is anticipated to surpass the $10.2 billion threshold in 2026, with compound annual growth rates stabilizing at approximately 6.5 percent over the forecast horizon. By the close of the projection window in 2032, total market valuation is projected to approach the $15 billion mark. This sustained expansion is underpinned by several converging forces: the aging of incumbent rotorcraft fleets that demands increasingly intensive heavy maintenance cycles, the modernization of avionics and propulsion systems that introduces new service categories, and the geographical diversification of civil helicopter operations into emerging markets where aerial mobility solutions are gaining institutional adoption.
For corporate strategists, these figures represent more than macroeconomic indicators. They signal a market in which capacity planning, service-line prioritization, and regional footprint decisions will yield disproportionate competitive advantages. Organizations that align their MRO investments with the cadence of fleet age profiles and regulatory timelines will be positioned to capture disproportionate shares of high-margin maintenance cycles, while those that rely on backward-looking utilization models risk strategic misalignment.
Structural Segmentation: Where Value Is Created and Captured
The civil helicopter MRO ecosystem is not a monolith. It is a layered constellation of service categories, each with distinct demand drivers, technical requirements, and margin profiles. Market intelligence reveals that airframe heavy maintenance continues to command the largest share of industry revenue, reflecting the capital-intensive nature of structural inspections, corrosion mitigation, and comprehensive rotorcraft airframe overhauls. Engine maintenance constitutes the second-largest pillar of the market, driven by the operational imperative to sustain powerplant reliability and the growing trend of engine life-extension programs that defer prohibitive replacement costs. Component maintenance, encompassing dynamic systems, avionics, transmissions, and rotor assemblies, represents a rapidly evolving segment where precision engineering and digital diagnostics are increasingly reshaping service delivery models.
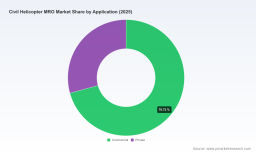
Alongside these technical divisions, the application landscape reveals a pronounced tilt toward commercial operations, which account for the dominant portion of MRO spending across the civil rotorcraft sector. Private and corporate helicopter fleets contribute a substantial secondary stream of demand, characterized by more customized service requirements, shorter turnaround expectations, and a higher willingness to invest in premium maintenance packages that preserve asset values and operational flexibility. Understanding the interplay between these service lines and application categories is critical for firms evaluating capacity allocation, pricing architecture, and partnership strategies.
The regional distribution of MRO activity further underscores the importance of geographically informed strategy. North America remains a foundational market, anchored by dense fleets, mature regulatory environments, and a robust network of certified repair stations. Europe follows as a structurally significant region, supported by stringent EASA compliance frameworks and a growing emphasis on cross-border rotorcraft operations. Asia Pacific represents an increasingly dynamic frontier, where expanding public safety mandates, resource-sector helicopter demand, and emerging commercial rotorcraft programs are catalyzing new MRO investments. Latin America and the Middle East and Africa, while currently smaller in aggregate scale, are experiencing targeted growth driven by energy-sector operations, crisis-response capabilities, and localized fleet modernization initiatives.
Military Helicopter MRO Market
A complete picture of these segmentation dynamics, however, requires more than high-level categorizations. It demands detailed breakdowns of demand elasticity, service-cycle durations, regional certification pathways, and the margin implications of each maintenance modality. This is precisely the level of granularity embedded within the full research deliverable.
Competitive Landscape: OEM Dominance, Independent Agility, and Strategic Differentiation
The civil helicopter MRO market is characterized by a moderately concentrated competitive environment, where a handful of large-scale players command meaningful market share while a diverse field of specialized independents competes on technical agility, regional proximity, and niche service capabilities. Market concentration metrics indicate that the top three participants collectively control roughly 38 percent of industry revenue, while the top five extend their combined footprint to approximately 48 percent. This structure suggests a market that rewards both scale efficiencies and specialized differentiation, with room for agile entrants to secure sustainable positions through certified capabilities, strategic partnerships, and targeted service expansions.
At the OEM tier, Airbus Helicopters maintains a formidable presence through its integrated HCare service portfolio, which spans heavy maintenance, dynamic component repair, blade restoration, avionics upgrades, and continuing airworthiness management organization (CAMO) support. Operating across more than thirty sites and ninety-three MRO centers globally, the OEM leverages its manufacturing heritage, proprietary technical data, and expansive service network to anchor long-term fleet support relationships. Its recent emphasis on preserving MRO expertise amid digital transformation signals a strategic recognition that technological modernization must be paired with the retention of high-caliber engineering and maintenance talent.
Within the independent MRO segment, several firms have established strong reputations for operational excellence and regulatory compliance. StandardAero and Heli-One, both Canadian-based specialists, deliver comprehensive airframe maintenance, repair, overhaul, and component support services for civil and commercial rotorcraft fleets worldwide. Their scale, technical certifications, and global service footprints position them as critical capacity providers for operators seeking independent, cost-competitive alternatives to OEM channels. Rotortrade, headquartered in Atlanta, has emerged as a highly adaptive independent provider, combining full-service maintenance, CAMO oversight, and FAA Part 145 certification with avionics integration capabilities, including its recognized dealership status with Garmin. Eurotech, based in Italy, operates as an EASA Part 145 certified MRO center delivering comprehensive maintenance and overhaul services for civil rotorcraft, while Saudia Technic, anchored in Riyadh, has expanded its capabilities to encompass comprehensive helicopter maintenance and overhaul services for civil and commercial aircraft, reflecting broader regional investment in aviation infrastructure.
The competitive landscape is not static. Recent developments illustrate how targeted investments and regulatory certifications are reshaping service capabilities in real time. In late 2025, Rotortrade officially launched its U.S. MRO facility, securing full FAA Part 145 certification and enabling return-to-service approvals for FAA-regulated rotorcraft—a move that materially expands its domestic service reach. The following year, in early 2026, the company's Latrobe facility was appointed an official Garmin dealership, broadening its certified avionics integration capabilities under existing FAA approvals. These developments highlight a broader industry pattern: independents are increasingly differentiating through specialized certifications, strategic technology partnerships, and facility expansions that align with regional regulatory frameworks and operator demand.
Simultaneously, the inaugural Vertical MRO Conference, held in Kelowna, British Columbia, drew over five hundred rotorcraft MRO professionals for education sessions and industry exhibitions, underscoring the growing institutional focus on knowledge exchange, technical standards, and cross-company collaboration within the rotorcraft maintenance community. For market participants, these gatherings are more than networking events; they are barometers of emerging best practices, supplier relationships, and regulatory expectations that will shape competitive dynamics in the years ahead.
Regulatory Dynamics and Industry Currents: The Compliance-Led Evolution of MRO Strategy
Regulatory evolution is one of the most powerful forces reshaping the civil helicopter MRO market. In the United States, the FAA Modernization of Special Airworthiness Certification (MOSAIC) final rule, published in mid-2025, introduced a series of phased compliance milestones that directly affect pilot training, maintenance rules, and the regulatory classification of certain aircraft categories. The staggered effective dates—spanning pilot training and maintenance rule updates in late 2025 through the removal of the light-sport aircraft definition from federal aviation regulations in mid-2026—require MRO providers and fleet operators to adapt their compliance frameworks, training pipelines, and service protocols with precision and foresight.
Parallel regulatory developments have reinforced the importance of structured safety management. U.S.-registered Part 145 repair stations that also hold EASA Part 145 certification were required to implement formal safety management systems by the end of 2025, aligning North American and European maintenance standards with increasingly rigorous risk-management expectations. More recently, the FAA has emphasized a long-term industry goal of achieving zero fatal civil helicopter accidents, publishing enhanced guidance that includes updated Airman Certification Standards for rotorcraft-helicopter series, replacing older practical test standards with more rigorous competency frameworks. These regulatory currents do not merely impose compliance obligations; they reshape the competitive landscape by rewarding organizations that invest early in proactive safety cultures, standardized training, and digitally enabled compliance tracking.
Beyond regulation, the market is responding to broader operational and technological currents. Eurotech's certification by Robinson Helicopter Company as an Authorized Robinson Helicopter Dealer for 2026 exemplifies how manufacturer-aligned authorizations are becoming strategic differentiators, validating MRO providers' adherence to specific technical standards and unlocking access to dedicated service ecosystems. Meanwhile, advances in predictive maintenance analytics, digital airworthiness documentation, and component lifecycle tracking are gradually transforming traditional MRO workflows from reactive repair models into data-informed service architectures. Organizations that integrate these capabilities into their operational models will be better positioned to reduce turnaround times, optimize parts inventory, and deliver the transparency that modern operators increasingly demand.
The Strategic Value of Comprehensive Market Intelligence in 2026
For enterprises operating in or adjacent to the civil helicopter MRO ecosystem, the complexity of the market environment in 2026 demands more than generalized industry awareness. It requires a structured, evidence-based intelligence foundation that integrates historical performance data, forward-looking projections, segmentation analysis, competitive profiling, and regulatory foresight into a single, coherent decision-support framework.
Civil Helicopter MRO Market
PW Consulting's Civil Helicopter MRO Market Research Report has been designed to meet this need. The study draws upon extensive primary and secondary research to deliver a multi-dimensional view of the market across its full forecast horizon. It provides detailed analysis of revenue trajectories, service-line dynamics, regional demand patterns, and the strategic moves of key market participants, enabling readers to benchmark their positioning, identify whitespace opportunities, and anticipate shifts in competitive intensity. The report also examines the practical implications of regulatory changes, technological adoption curves, and fleet lifecycle dynamics, translating high-level trends into actionable strategic considerations for capacity planning, partnership evaluation, and market-entry or expansion decisions.
Importantly, the intelligence contained within this research is structured to support a range of operational and strategic functions. For MRO service providers, the analysis offers a basis for calibrating investment in facility capacity, certification pathways, and specialized service lines. For OEMs and component manufacturers, it illuminates downstream demand patterns and the service-interface opportunities that accompany fleet modernization. For financial stakeholders and investors, it provides a disciplined framework for evaluating growth trajectories, margin drivers, and the competitive vulnerabilities that may influence long-term returns. For fleet operators and aviation authorities, it delivers context on service availability, regulatory alignment, and the evolving standards that shape procurement and compliance strategies.
Navigating the Next Seven Years with Confidence
The civil helicopter MRO market is entering a phase defined by sustained growth, regulatory refinement, and intensifying competitive differentiation. The macroeconomic trajectory is clear: revenue expansion will continue at a robust pace, fleet age profiles will drive increasing demand for heavy maintenance and component overhaul, and regional demand centers will continue to diversify as rotorcraft operations expand into new operational contexts. Yet the precise allocation of opportunity across service categories, geographic zones, and competitive tiers remains a question that can only be answered through detailed, research-backed analysis.
In an environment where strategic agility depends on accurate foresight, access to comprehensive market intelligence is not merely an informational advantage—it is a foundational element of operational resilience and growth planning. The full Civil Helicopter MRO Market Research Report provides the depth, structure, and analytical rigor required to make informed decisions with confidence. Readers seeking the complete segmentation breakdowns, detailed company profiles, regional demand mappings, and forward-looking scenario analysis are encouraged to access the full report through the source webpage, where the complete intelligence suite is available for institutional review and strategic application.
For detailed analysis of this topic, please visit the official page: Civil Helicopter MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


