



PW Consulting: Auto Repair Market Hits $779.3M in 2025, Projected 5.7% CAGR to 2032

Navigating the Automotive Repair and Maintenance Services Market in 2026
The automotive service industry stands at a critical inflection point. As vehicle technologies evolve and consumer expectations shift, the Automotive Repair and Maintenance Services Market requires rigorous analysis to support strategic decision-making in 2026 and beyond. PW Consulting's latest market research delivers a comprehensive examination of this dynamic landscape, offering enterprise leaders the intelligence needed to navigate growth, competition, and transformation.
This market study tracks historical performance from 2020 through 2025, establishing a robust baseline against which future projections can be measured. The global market reached approximately 779.3 million USD in 2025, reflecting steady expansion driven by increasing vehicle parc, aging fleets, and rising consumer awareness of preventive maintenance. Looking ahead, the forecast period spanning 2026 to 2032 projects the market to reach 1,148.76 million USD by the terminal year, representing a compound annual growth rate of 5.7 percent. These macro-level indicators signal sustained demand, but the true strategic value lies in understanding the underlying forces shaping this trajectory.
Why This Research Matters for Enterprise Strategy
Market intelligence is only valuable when it translates into actionable insight. This report is designed for executives, investors, and operational leaders who need to make informed decisions about capacity planning, service portfolio optimization, geographic expansion, and competitive positioning. The analysis goes beyond surface-level metrics to examine the structural dynamics that will define winners and laggards in the coming years.
Several macro trends converge to create both opportunity and disruption. Vehicle ages continue to rise in many developed markets, extending the repair lifecycle and sustaining demand for mechanical and electrical services. Simultaneously, the transition toward electrification introduces new service categories while rendering certain traditional skill sets obsolete. Regulatory developments around data access and repair rights reshape the competitive balance between dealerships, independent shops, and aftermarket suppliers. Labor markets present their own challenges, with technician shortages and wage inflation pressuring margins across the value chain.
Worldwide Car Body Repair Market
This research contextualizes these forces within a rigorous analytical framework. It provides clients with the clarity needed to allocate capital efficiently, identify adjacent growth opportunities, and mitigate risks stemming from technological or regulatory shifts.
Report Scope and Practical Components
The study delivers a multi-dimensional view of the market, structured to support diverse use cases across strategy, finance, and operations. Key components include:
Automotive Repair and Maintenance Services Market
- Historical and Forecast Modeling: Detailed year-over-year projections from 2026 through 2032, enabling scenario planning and sensitivity analysis for revenue forecasting and investment appraisal.
- Segmentation Analysis: Breakdowns across service types, vehicle categories, end-user profiles, and regional dimensions to pinpoint where growth concentrates and which subsegments warrant dedicated resources.
- Competitive Landscape Mapping: Profiles of leading operators, examination of market concentration metrics, and assessment of consolidation trends that influence pricing power and market access.
- Industry Dynamics and Structural Shifts: Evaluation of workforce development, certification trends, regulatory initiatives, and supply chain factors that alter operating economics.
- Strategic Recommendations: Actionable guidance for service providers, investors, and suppliers seeking to optimize portfolios, enter new geographies, or pivot toward emerging service categories.
Each section is designed to stand alone for targeted deep dives while contributing to a cohesive narrative about where the market is headed and how stakeholders should respond.
Dynamic Market Forces Shaping 2026
No market analysis is complete without acknowledging the rapidly evolving environment in which companies operate. Several developments in early 2026 illustrate the pace of change and the need for agile strategy.
Regulatory and Policy Evolution
The U.S. House Energy and Commerce Committee passed the Motor Vehicle Modernization Act of 2026, a legislative milestone that modernizes vehicle data access and repair rights. This act carries significant implications for independent repair shops, dealerships, and aftermarket suppliers, as it redefines who can access diagnostic data and under what conditions. Around the same time, the Auto Care Association launched a member-exclusive Auto Parts Tariff Calculator and hosted a webinar addressing the 2026 policy landscape, including Right to Repair considerations and vehicle data governance. These initiatives underscore the growing importance of regulatory fluency as a competitive differentiator.
Workforce and Certification Transformation
The National Institute for Automotive Service Excellence announced a major training expansion, with total nationwide technicians holding L3 Electric Vehicle Safety certifications surpassing 25,000. This milestone reflects the industry's urgent response to electrification, as high-voltage systems demand specialized knowledge and safety protocols. Concurrently, labor economics remain a persistent concern. Automotive repair labor rates average 110 USD per hour in Mississippi and approach 175 USD per hour in California, illustrating the regional variability that complicates standardized service pricing and margin management. Companies must balance wage pressures with throughput efficiency and service mix optimization.
Corporate M&A and Strategic Positioning
Consolidation continues to reshape the competitive field. Valvoline Inc. completed its acquisition of Breeze Autocare from Greenbriar Equity Group in December 2025, integrating over 200 geographic locations into its retail infrastructure. This move expands Valvoline's service footprint and reinforces its emphasis on preventive maintenance and quick-lube convenience. In parallel, Bosch Car Service issued a global opportunity statement to experts for the development of EV repair and maintenance aspects, signaling supplier-side investment in capability building. These actions highlight how incumbents and adjacent players are repositioning to capture value in a transitioning market.
Competitive Landscape and Market Concentration
The market exhibits moderate concentration, with the top three firms accounting for approximately 35 percent of revenue and the top five reaching roughly 42 percent. This structure suggests room for both scaled operators and regional specialists to compete effectively, though scale advantages in procurement, brand recognition, and service network density remain influential.
Several established players illustrate the diversity of strategic approaches within the sector:
- Monro, Inc. operates a family of 16 brands including Mr. Tire, Mr. Lube, and Mr. Muffler, delivering complete under-car care, oil changes, brakes, shocks, struts, exhaust systems, and state inspections across 1,115 service locations in 32 states. Its multi-brand architecture enables targeted positioning across price points and service specialties.
- Jiffy Lube International provides quick-lube and full-service offerings spanning oil changes, tires, brakes, batteries, fluids, and vehicle inspections at over 2,000 service centers coast to coast. Its emphasis on speed, convenience, and consistency aligns with consumer demand for low-friction maintenance experiences.
- Valvoline Inc. manages Valvoline Instant Oil Change and allied brands, delivering preventive maintenance, oil changes, tire services, and general repairs through approximately 2,400 franchised and company-operated centers in the U.S. and Canada. Its hybrid franchise and corporate model supports rapid scaling while maintaining service quality standards.
- Mavis Tire Express Services Corp. offers tires, oil changes, brakes, alignments, and general automotive repair at over 2,100 service centers across 36 states. Its broad geographic coverage and integrated service menu position it to capture share in tire-centric and general repair demand.
These companies demonstrate that differentiation can emerge from brand architecture, service mix, operational model, or geographic density. The report analyzes how each player navigates margin pressures, regulatory shifts, and technology transitions, providing benchmarks for peers evaluating their own strategic direction.
Segmentation Considerations Without Losing Sight of the Whole
While aggregate growth figures provide orientation, the real strategic insight emerges from understanding how demand distributes across service categories, vehicle types, and end users. For instance, mechanical services and electrical services collectively represent a substantial share of market activity, reflecting both traditional repair needs and the growing complexity of vehicle electronics. Body repair services and tire services constitute additional meaningful pillars, each with distinct demand drivers tied to accident rates, seasonal usage patterns, and vehicle age profiles. Preventive maintenance remains a critical lever for customer retention and lifetime value, particularly as fleets and individual owners seek to extend vehicle lifecycles amid rising replacement costs.
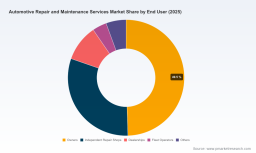
On the vehicle side, passenger cars drive the largest portion of service volume, yet light and heavy commercial vehicles contribute materially to overall revenue, especially in regions with strong logistics and construction activity. Motorcycles and other niche categories add incremental but strategically relevant demand, particularly where two-wheeler penetration is high. End-user dynamics further complicate the picture: owners represent the largest customer base, while independent repair shops, dealerships, fleet operators, and other channels each exhibit unique purchasing behaviors, margin structures, and service expectations.
Rather than presenting static splits that quickly become outdated, the research emphasizes the relationships between these segments and the forces that shift their relative importance over time. This approach equips clients to anticipate which subsegments will accelerate, which will face headwinds, and where cross-segment synergies can be captured.
Regional Dynamics and Geographic Strategy
Geographic variation in demand, labor economics, regulatory environment, and competitive intensity requires tailored strategy. North America and Asia Pacific represent large and evolving market centers, each with distinct growth drivers and operational considerations. Europe maintains a mature service ecosystem shaped by stringent vehicle standards and strong independent repair traditions. Latin America and the Middle East and Africa present smaller but potentially high-growth opportunities, often contingent on infrastructure development, vehicle parc expansion, and formalization of service channels.
The report examines regional trends without reducing them to simplistic rankings. It explores how local labor markets influence service pricing, how regulatory frameworks affect aftermarket access, and how consumer preferences shape service mix. This nuanced perspective enables clients to prioritize markets based on their risk appetite, operational capabilities, and strategic objectives rather than chasing aggregate size alone.
Cost Structures and Economic Realities
Margin management sits at the heart of service business performance. Recent industry analysis indicates that average vehicle maintenance and repair cost per mile reached 9.83 cents in the most recent AAA assessment, a figure that encapsulates parts, labor, and overhead across a broad vehicle population. For service providers, this benchmark contextualizes the value proposition offered to consumers and fleet operators alike. It also highlights the sensitivity of demand to economic cycles, fuel prices, and vehicle reliability trends.
Labor remains the most variable and strategically significant cost component. Regional disparities in wage rates, combined with technician availability and certification requirements, create a complex operating environment. Companies that invest in training pathways, workflow optimization, and service scheduling technology can partially offset wage inflation while improving throughput and customer satisfaction. The research integrates these economic realities into its forward outlook, helping clients stress-test their assumptions about pricing, staffing, and capacity.
Strategic Implications for 2026 Decision-Makers
Leaders evaluating this market in 2026 should focus on several interconnected priorities:
- Service Portfolio Rebalancing: Assess exposure to traditional mechanical and body repair demand while building capability in electrical diagnostics, battery-related services, and preventive maintenance programs that align with evolving vehicle fleets.
- Workforce Strategy: Develop recruitment, training, and retention programs that address technician shortages and support certification pathways, particularly for high-voltage and EV-related competencies.
- Regulatory Readiness: Monitor data access rules, tariff implications, and Right to Repair developments that influence aftermarket participation, supplier relationships, and service delivery models.
- Scale and Network Optimization: Evaluate whether organic growth, acquisition, or partnership models best fit target geographies and customer segments, considering the concentration dynamics and competitive intensity present in each market.
- Technology and Equipment Investment: Align tooling, diagnostic systems, and service management platforms with the mix of conventional and electrified vehicles expected to enter the service pipeline over the forecast period.
These priorities are not isolated; they interact in ways that reward integrated strategy. A workforce initiative supports service quality, which strengthens customer retention, which improves the economics of preventive maintenance, which in turn reduces reliance on higher-cost reactive repairs. The report provides the analytical foundation to design and sequence such initiatives coherently.
Access the Full Intelligence
This overview highlights the strategic dimensions and market momentum captured in PW Consulting's Automotive Repair and Maintenance Services Market research. It demonstrates the breadth of analysis available, from historical baselines and multi-year forecasts to competitive profiling, regulatory context, and operational economics. Yet the full value of the study lies in its detailed breakouts, scenario frameworks, and segment-specific guidance, which are essential for precise planning and execution.
Enterprise leaders seeking to translate market awareness into decisive action are encouraged to access the complete report. The full analysis provides the granular insight required to validate assumptions, benchmark performance, and model strategic options with confidence. In a market defined by technological change, regulatory flux, and competitive realignment, comprehensive intelligence is not a luxury—it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Automotive Repair and Maintenance Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


