



PW Consulting: Cellophane Market Hits $403M in 2025, Projected to Reach $557M by 2032 at 4.8% CAGR

Navigating the Regenerated Cellulose Landscape: Strategic Insights for the Cellophane Market Through 2032
Executive Summary
The global cellophane market stands at a critical intersection of sustainability mandates, packaging innovation, and supply chain recalibration. As enterprises navigate the transition from conventional plastics toward bio-based, transparent packaging solutions, regenerated cellulose films are experiencing a measured but definitive resurgence. Our latest Cellophane Market research report provides a comprehensive, data-driven framework designed specifically to support strategic decision-making across procurement, product development, regional expansion, and competitive positioning through 2032.
Built on a rigorous historical foundation spanning 2020 through 2025 and extended forward to 2032, this analysis captures the structural shifts, regulatory tailwinds, and material science advancements that will define commercial viability in the coming years. Below, we outline the strategic architecture of the study, highlight the operational intelligence it delivers, and demonstrate why access to granular market intelligence is no longer optional for organizations competing in the advanced packaging ecosystem.
Market Trajectory and Structural Growth Drivers
The cellophane market has demonstrated consistent expansion over the past half-decade, with global revenue progressing from approximately 322.0 million USD in 2020 to an estimated 403.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 4.8 percent across the analysis window, culminating in projected revenue of 426.65 million USD for 2026. The forward forecast indicates steady momentum, with market valuation expected to approach 557.0 million USD by 2032.
Several structural forces underpin this growth profile. First, regulatory frameworks across major economies are increasingly penalizing conventional plastic packaging while incentivizing compostable, recyclable, and bio-based alternatives. Regenerated cellulose films, which derive their functional properties from wood-pulp-based feedstocks, align closely with these policy directions. Second, consumer-facing brands in food, personal care, and tobacco segments continue to prioritize visual clarity, breathable barrier properties, and eco-credentialing in their packaging architectures, all of which reinforce demand for high-grade cellophane grades. Third, manufacturing capacity expansions in key production hubs are gradually improving supply reliability and cost competitiveness, though regional variations in pellet-to-film conversion efficiency and raw material availability continue to shape localized pricing dynamics.
Our report synthesizes these demand-side, supply-side, and policy-driven variables into a cohesive forecasting model, enabling organizations to stress-test procurement strategies, anticipate capacity utilization cycles, and map growth corridors with greater precision.
Segmentation Intelligence: Where Commercial Value Is Being Concentrated
Effective strategy formulation requires more than top-line market sizing. The cellophane market is inherently segmented across product types, application verticals, and geographic footprints, each presenting distinct margin profiles, regulatory exposures, and growth velocity. This research deconstructs those dimensions with operational granularity.
Cling Film Market
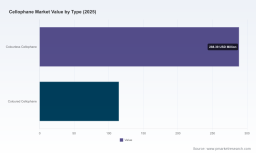
By product type, the market bifurcates into specialty grades optimized for visual transparency and moisture management, alongside variant formulations engineered for enhanced barrier performance, printability, and compatibility with automated packaging lines. Demand patterns across these categories reflect differing end-use requirements: beverage and confectionery applications prioritize clarity and tactile premiumization, while industrial and adhesive-adjacent uses emphasize dimensional stability and coating adhesion. The report evaluates volume shifts, price elasticity, and substitution risks within each product tier.
Application segmentation reveals a diversified consumption base. Food packaging continues to anchor the largest share of industrial demand, driven by regulatory alignment around compostable wraps, breathable confectionery films, and tamper-evident presentation layers. Tobacco packaging maintains a stable, brand-conscious demand profile where cellophane's clarity and sealing characteristics support traditional and premium product positioning. Pharmaceutical packaging leverages the film's moisture-regulating properties and regulatory compliance pathways for blister backing, unit-dose sleeves, and secondary presentation wraps. Personal care and specialty applications, including cosmetic pouches, gift presentation, and industrial wrapping, round out a consumption matrix that demonstrates both resilience and adaptability.
Cellophane Market
Geographically, the market exhibits pronounced regional divergence in consumption intensity, manufacturing localization, and policy exposure. Developed markets with mature packaging ecosystems show steady replacement-driven demand and heightened sensitivity to extended producer responsibility frameworks, while emerging and industrializing regions display faster volume expansion tied to retail formalization, e-commerce logistics, and domestic film manufacturing scale-up. The analysis maps these regional trajectories without relying on surface-level aggregate splits, instead focusing on the structural drivers, trade flow patterns, and capacity deployment strategies that determine where competitive advantage can be sustained.
Raw material sourcing represents a critical supply-side variable. Wood-derived cellulose is projected to account for a dominant share of feedstock input in 2026, reflecting the material's capacity to deliver consistent film strength, commercial throughput, and functional transparency. However, supply continuity remains sensitive to forestry harvest cycles, pulp pricing volatility, and competing industrial demand from textile and paper sectors. The report assesses how feedstock availability, regenerative sourcing certification trends, and alternative cellulose pathways influence cost structures and long-term supply resilience.
Competitive Landscape: Positioning, Capability, and Market Concentration
Market concentration in the cellophane sector reflects a structure where scale, technological differentiation, and regional manufacturing presence converge to shape competitive outcomes. Industry analysis indicates a concentrated landscape in which leading producers capture a substantial share of global throughput, with the top three competitors accounting for approximately 60 percent of market revenue and the top five collectively representing around 70 percent. This concentration underscores the importance of understanding not just who competes, but how they compete across product architecture, sustainability credentials, and downstream customer integration.
Futamura Chemical Co., Ltd., headquartered in Japan, remains a defining reference point for the sector. As a leading producer of cellophane-based and cellulose-derived transparent packaging films, the company has historically anchored its commercial strategy around renewable wood-pulp formulations designed for food, confectionery, and sustainable packaging applications. Its recent product development pathway emphasizes compostable sachet architectures and collaborative engineering with packaging machinery manufacturers, reflecting a broader industry shift toward closing the loop on single-use non-compostable formats.
In China, several manufacturers have scaled cellophane and coated cellulose film production into globally exported volumes. Weifang Henglian Cellophane Co., Ltd., based in Shandong, operates annual capacity exceeding 5,000 metric tons across PT-cellophane, roll cellophane, MST-cellophane, and coated variants, with commercial focus spanning food packaging, adhesives, and printing applications. Zhejiang Koray New Materials Co., Ltd., located in Shaoxing, specializes in cellulose film production including coated grades and markets high-quality transparent films through eco-industrial production lines. Hubei Golden Ring New Materials Tech Ltd., operating from Hubei, integrates viscose and lyocell fiber production with cellulose film manufacturing, supplying regenerated cellulose packaging materials through vertically coordinated pulp-to-film processes. Together, these entities illustrate how regional capacity expansion, cost engineering, and export-oriented supply chains are reshaping the competitive equilibrium.
Recent corporate and policy developments further illuminate the trajectory of competition. Futamura's launch of compostable packaging sachets for liquid products, developed in collaboration with machine producer GK Sondermaschinenbau, signals an industry-wide push to lower dependence on non-compostable formats through advanced cellulose film engineering. Meanwhile, manufacturing participation at major trade platforms such as interpack 2026 demonstrates how suppliers are using exhibition-driven visibility to reinforce green packaging positioning and showcase regenerated cellulose film capabilities to global buyers. These moves are not isolated product launches; they are strategic signals that reshape customer expectations, procurement criteria, and supplier qualification standards.
Regulatory and Operational Dynamics Shaping Procurement and Compliance
Regulatory frameworks are no longer peripheral considerations; they are central determinants of cost allocation, material selection, and market access. The U.S. FDA permits the use of regenerated cellulose film for food packaging under structured conditions, reinforcing the material's eligibility within certified food-contact applications and influencing procurement specifications among North American buyers. In parallel, European and Commonwealth policy architectures are moving toward packaging stewardship models that assign financial responsibility for end-of-life management directly to producers.
The UK government's publication of 2025–2026 base fees for Extended Producer Responsibility for Packaging illustrates this shift in operational terms. The fee structure introduces differentiated rates across material categories, with implications for cellulose film producers classified under broader packaging material designations. Because extended producer responsibility schemes tie compliance costs to material composition and recovery performance, procurement teams must evaluate not only unit pricing and conversion efficiency but also downstream recyclability, compostability claims, and administrative burden associated with fee registration and reporting.
The operational consequence is clear: packaging decisions increasingly require integrated assessments that combine material performance, regulatory cost exposure, supplier documentation readiness, and brand sustainability messaging. Our research maps these regulatory dynamics to real procurement scenarios, enabling teams to anticipate compliance friction, quantify total cost of ownership more accurately, and align material selection with policy trajectories rather than reacting after regulatory thresholds shift.
What the Report Delivers: Practical Intelligence for Cross-Functional Decision-Making
This Cellophane Market study is designed as an executive-grade operational resource rather than a static market summary. It translates macroeconomic trends, segmentation behavior, and competitive dynamics into actionable intelligence across multiple functional domains.
- Historical reconstructions and forward forecasts that establish a defensible baseline for capacity planning, inventory strategy, and revenue modeling through 2032.
- Granular segmentation analysis across product types, application verticals, and geographic markets, enabling teams to isolate high-margin demand pockets and identify substitution pressure points.
- Raw material and supply chain assessments that examine cellulose feedstock reliance, forestry supply sensitivity, and regional pulp-to-film conversion dynamics affecting cost structures and availability risk.
- Competitive profiling of leading producers, with emphasis on manufacturing scale, product differentiation, sustainability positioning, and recent corporate developments that influence customer qualification and supplier selection.
- Regulatory and compliance mapping that connects packaging stewardship frameworks, food-contact permissions, and material classification rules to procurement strategy and total cost evaluation.
- Strategic scenario considerations that help organizations evaluate growth corridors, pricing sensitivity, capacity deployment logic, and portfolio alignment with sustainability-driven procurement mandates.
Each section is structured to support direct integration into commercial planning workflows. Whether the objective is to validate regional expansion assumptions, benchmark supplier capabilities, refine application-specific packaging specifications, or assess the financial impact of extended producer responsibility exposure, the report provides the analytical scaffolding necessary to move from intuition to evidence-based strategy.
Why This Research Matters for 2026 Strategic Planning
The 2026 planning cycle demands more than retrospective market readouts. It requires forward visibility into a market where regulatory cost structures, feedstock availability, consumer packaging expectations, and competitor capability development are evolving simultaneously. The 4.8 percent compound growth trajectory, the progression toward 557.0 million USD by 2032, and the concentration of market revenue among a limited set of scaled producers all point to a sector where timing, positioning, and intelligence quality directly influence commercial outcomes.
Organizations that treat cellophane as a commodity input risk underpricing compliance exposure, overestimating supply flexibility, and missing segment-specific demand shifts. Organizations that treat it as a strategically managed material system, by contrast, can align procurement with sustainability mandates, lock in preferred supplier relationships ahead of capacity constraints, and tailor product specifications to application-level performance requirements. The distinction between these two approaches is often determined by the quality of market intelligence available at the point of decision.
Our report is structured to close that gap. It provides the macro context, segmentation clarity, competitive map, and regulatory overlay needed to support confident choices in sourcing, product development, and market prioritization. The full dataset, scenario analysis, and detailed segmentation breakdowns are reserved for the complete study, where they can be deployed with the precision necessary for capital allocation, supplier negotiation, and long-range planning.
Next Steps: Accessing the Complete Intelligence Framework
For executives, procurement leaders, packaging developers, and strategy teams preparing for 2026 and beyond, partial visibility is a strategic liability. The complete Cellophane Market research report extends far beyond the summary perspective outlined here, offering detailed segmentation depth, regional demand logic, competitive benchmarking, and forward-looking scenario analysis calibrated for operational decision-making.
To obtain the full intelligence package, including granular market size trajectories, application-level demand analysis, supplier capability comparisons, and regulatory impact assessments, we invite you to access the complete report through our official research portal. The comprehensive version is designed to support precise forecasting, procurement strategy refinement, and competitive positioning grounded in data rather than generalization.
In a market defined by sustainability transitions, regulatory recalibration, and concentrated supplier capability, strategic advantage belongs to organizations that make decisions with full context. This research is built to provide that context.
For detailed analysis of this topic, please visit the official page: Cellophane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


