



PW Consulting: 4K Ultra HD TV Market Hits $118.85M in 2025, Projected 24.38% CAGR to 2032

Strategic Horizon: Navigating the 4K Ultra HD TV Market in 2026 and Beyond
The 4K Ultra HD television market stands at a critical inflection point as of 2026. Driven by an accelerating compound annual growth rate of 24.38 percent, the sector has transformed from a mature consumer electronics category into a high-velocity growth arena fueled by display innovation, smart ecosystem integration, and shifting viewer behaviors. Our latest 4K Ultra HD TVs Market study compresses the historical trajectory of 2020 through 2025 and extends a disciplined forecast window to 2032, delivering the analytical architecture executives need to calibrate capital allocation, product roadmaps, and supply chain resilience in an increasingly volatile landscape.
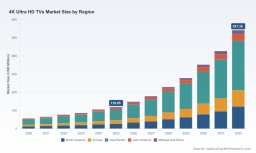
For strategic decision-makers, the overarching narrative is clear: market revenue has climbed from 56.22 million USD in 2020 to an estimated 118.85 million USD in 2025, positioning the base year as a springboard for exponential expansion. Looking forward, the forecast period maps a steep upward curve, projecting revenue to reach 147.92 million USD in 2026, 178.42 million USD in 2027, and accelerating toward 541.36 million USD by 2032. This trajectory is not merely a statistical projection; it is a structural signal that the next wave of growth will be captured by organizations that align product strategy with regional demand patterns, display technology adoption, and application-driven usage models. The purpose of this preview is to illuminate the analytical depth awaiting buyers of the full study, while deliberately withholding the granular breakdowns that only the complete report can provide.
Decoding the Growth Trajectory: From Recovery to Accelerated Expansion
The historical window of 2020 to 2025 reveals a market that has consistently outgrown the broader consumer electronics average. Revenue climbed to 64.76 million USD in 2021, advanced to 76.68 million USD in 2022, and held steady growth at 86.68 million USD in 2023. The acceleration became more pronounced in 2024, when revenue reached 105.39 million USD, before culminating in the 2025 base-year figure of 118.85 million USD. This progression underscores a market that has successfully navigated post-pandemic demand normalization, channel rebalancing, and the early adoption of premium display technologies.
The forecast window from 2026 through 2032 is where strategic planning becomes decisive. Starting at 147.92 million USD in 2026, the market is projected to scale to 228.87 million USD by 2028, then 351.99 million USD by 2030, and ultimately 541.36 million USD by 2032. This stepped expansion signals a market in which technological differentiation, smart-platform monetization, and regional penetration rates will increasingly determine competitive positioning. Executing on this opportunity requires more than a top-line growth assumption; it demands a comprehensive understanding of how product segmentation, regional dynamics, and end-use applications interact over time. The full study unpacks these interactions with a level of granularity that enables scenario planning, market-entry prioritization, and investment sequencing.
Segmentation Architecture: Where Growth Will Concentrate
A market moving at this pace cannot be managed through aggregate figures alone. The report disaggregates the landscape across three critical dimensions, each carrying distinct strategic implications for product planning, pricing architecture, and channel strategy. Understanding how display types compete, how applications evolve, and how regional markets behave is essential for translating a 24.38 percent CAGR into actionable forecasts.
Display Technology Dynamics
The competitive battleground for 4K Ultra HD televisions is increasingly defined by the interplay of advanced display technologies. The study examines OLED, QLED, and LED architectures as distinct value pools, mapping their adoption curves, pricing tiers, and performance positioning. Each technology offers a different value proposition, from premium contrast and color performance to cost-efficient scalability and smart-feature enablement. The analytical framework inside the full report isolates the demand drivers that will determine which technology segments capture share, how pricing pressure evolves, and where manufacturers can secure margin resilience. Because these technology shares are shifting rapidly with new panel supply and consumer preference, the detailed splits and growth trajectories are disclosed only within the complete study.
Application-Driven Demand
Modern 4K Ultra HD TVs are no longer passive display devices; they are content hubs, gaming platforms, and smart-ecosystem endpoints. The report evaluates application categories including Smart TV and Gaming TV environments, alongside other specialized use cases. This segmentation is vital because application mix directly influences feature requirements, connectivity expectations, and retail positioning. Smart TVs, for instance, require deep integration with operating systems, streaming partnerships, and AI-driven user experiences, while gaming-focused models emphasize refresh rates, low latency, and HDR alignment. The study maps demand intensity and growth prospects across these applications, equipping product teams with a demand-side blueprint. Specific proportion breakdowns and revenue attribution by application are reserved for the full report to preserve the precision of the underlying model.
Regional Growth Profiles
Geographic demand is unevenly distributed and increasingly shaped by regulatory conditions, infrastructure readiness, and local pricing dynamics. The research partitions the market across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each presenting a distinct value-creation path. Asia Pacific represents the largest value concentration, reflecting scale demand and rapid technology adoption, while North America and Europe contribute structurally significant volumes with higher average unit pricing in premium segments. Latin America and the Middle East and Africa present growth opportunities tied to infrastructure expansion, digital content availability, and evolving retail ecosystems. The complete study provides a region-by-region examination of market size trajectories, demand catalysts, and competitive intensity without publishing the detailed regional percentages here, so decision-makers are encouraged to consult the full report for the exact geographic splits required to build accurate regional plans.
Competitive Landscape: Strategic Positioning and Innovation Pressure
The 4K Ultra HD TV market is defined by a dense field of global manufacturers, each pursuing differentiated strategies in display technology, smart-platform integration, and pricing architecture. The report profiles leading enterprises including Samsung Electronics, LG Electronics, Sony Corporation, Hisense, TCL Corporation, Panasonic Corporation, VIZIO, and Skyworth. These companies anchor the market through distinct value propositions: Samsung and LG leverage advanced QLED, OLED, and AI-enhanced smart features; Sony competes on premium picture quality and BRAVIA platform integration; Hisense and TCL push Mini-LED and QD-Mini LED architectures into broader consumer segments with Google TV and smart ecosystem alignment; Panasonic combines OLED and 4K LCD panels with Fire TV integration; VIZIO focuses on accessible 4K UHD smart TVs with Dolby Vision and HDR support; and Skyworth delivers HDR-enabled 4K UHD models targeting value-conscious segments.
Beyond the established incumbents, market dynamics are being reshaped by new entrants and platform-driven expansion. Notably, Amazon announced the W70B Series Smart TV as a core 4K UHD model, emphasizing sleek design and immersive viewing, signaling how platform players are entering the hardware space to deepen ecosystem lock-in. This kind of product launch matters strategically because it intensifies competition for share of attention, smart-services revenue, and retail shelf presence. The full study goes beyond company profiles to map competitive interaction patterns, including how brand portfolios are structured, where pricing pressure is building, and which segments are most vulnerable to disruption. Given the consolidated nature of the industry, competitive analysis must also consider market concentration, and the complete research provides the exact concentration metrics needed to assess barrier-to-entry conditions and pricing power.
Industry Dynamics: Supply Chain Constraints, Regulatory Headwinds, and Cost Volatility
No strategic assessment of the 4K Ultra HD TV market is complete without confronting the operational and regulatory pressures that shape cost structures and supply continuity. As of April 2025, China placed export restrictions on seven categories of medium and heavy rare earths, including dysprosium, samarium, and terbium, which are essential for permanent magnets used in 4K TV displays and components. These restrictions were part of a broader response to tariff escalations and have introduced material price volatility and supply chain uncertainty across electronics production. Further analysis from early 2026 indicates that these controls will continue to affect component availability and cost planning, with additional foreign direct product rule extensions shaping procurement strategies.
The practical implication for manufacturers and channel partners is that cost forecasting can no longer rely solely on historical component pricing. Rare earth constraints and raw material volatility have become structural variables in the cost stack, influencing margin planning, sourcing diversification, and manufacturing geography. The report integrates these dynamics into a broader sustainability and supply chain risk framework, helping executives anticipate where bottlenecks may emerge, how pricing architectures may need to adapt, and which product tiers are most exposed to input-cost fluctuations. Because the precise impact varies by component, component substitution pathways, supplier diversification options, and regional sourcing implications differ across product segments, the complete study supplies the operational detail necessary to translate these macro risks into procurement and product decisions.
Inside the Report: Operational Content Built for Executive Action
This market study is designed to move beyond descriptive trends and deliver decision-grade intelligence. The full version includes product and technology assessments, application-level demand analysis, regional market mapping, and competitive positioning evaluations. It is structured to support multiple functional needs: product managers can use it to prioritize feature roadmaps and display mix decisions; sales and commercial teams can align go-to-market plans with regional demand signals; supply chain and sourcing leaders can evaluate material exposure and supplier diversification paths; and strategy teams can build investment scenarios grounded in forecast-period growth paths.
In addition to the core segmentation and forecast content, the study synthesizes recent industry developments and regulatory milestones, including export control actions and platform-driven product launches, into a practical context for near-term planning. The report is built for readers who need a single analytical reference that connects market size, growth trajectory, competitive intensity, and supply-side risk into one consistent framework. Readers seeking exact regional percentages, application splits, type-based revenue shares, and company-level concentration figures will find those details only in the full release, which is why this preview deliberately highlights the architecture and advisory value without disclosing the embedded figures.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a market view that is simultaneously optimistic about growth and disciplined about risk. A compound annual growth rate of 24.38 percent over the forecast period signals an exceptional opportunity, but capturing that opportunity requires a precise understanding of where growth is concentrated, how competitive pressures are evolving, and which external shocks can alter cost and availability assumptions. The 4K Ultra HD TVs Market study provides that integrated view, linking historical momentum, forecast expansion, segmentation dynamics, and competitive context into a single strategic frame. It is intended to help leadership teams answer the practical questions that shape capital allocation, product portfolio strategy, regional prioritization, and risk mitigation in the year ahead.
For organizations building their 2026 plans, the full report offers the depth required to convert a high-level growth story into actionable strategy. The preview above demonstrates the analytical approach, the scope of coverage, and the strategic context embedded in the research, while preserving the segmented data and competitive metrics for the complete edition. To access the full market size progression by year, the detailed segmentation splits, the comprehensive company profiles, and the operational dynamics analysis, readers are encouraged to obtain the full study from the source page, where the complete intelligence package is available for decision-making across product, commercial, and supply chain functions.
4K Ultra HD TVs Market
UHD TV Market
For detailed analysis of this topic, please visit the official page: 4K Ultra HD TVs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


