



PW Consulting: Sulphur Bentonite Market Hits $178.1M in 2025, Projects 4.7% CAGR to 2032

Strategic Intelligence for the Sulphur Bentonite Market: Navigating Growth, Volatility, and Competitive Shifts Through 2032
The Sulphur Bentonite Market stands at a critical inflection point. As agricultural demand intensifies and regulatory frameworks evolve across key producing and consuming regions, manufacturers, investors, and supply chain strategists require more than surface-level projections. PW Consulting’s latest market research delivers a comprehensive, forward-looking assessment designed to equip decision-makers with actionable intelligence for the 2026–2032 horizon. This report does not merely chart historical trajectories; it decodes the structural forces shaping value creation, margin dynamics, and competitive positioning in a market experiencing steady, technology-driven expansion.
Market Trajectory: A Data-Backed Foundation for Strategic Planning
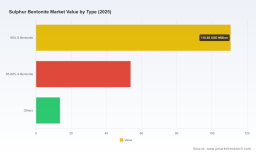
Building on a clear historical baseline, the Sulphur Bentonite Market has demonstrated consistent upward momentum across the 2020–2025 evaluation window. Total market valuation climbed from approximately 140.5 million USD in 2020 to an estimated 178.1 million USD by 2025, reflecting sustained adoption of bentonite-sulphur formulations across agricultural and industrial applications. This trajectory is projected to accelerate into the forecast period, with the market anticipated to reach 184.9 million USD in 2026 and expand further to 242.72 million USD by 2032. The compound annual growth rate of 4.7 percent throughout the 2026–2032 forecast window underscores a market characterized by moderate but reliable expansion, driven by soil health initiatives, micronutrient integration requirements, and evolving fertilizer blend architectures.
Revenue streams have consistently been denominated in USD million, providing a standardized metric for cross-regional benchmarking and investment allocation. Rather than relying on static snapshots, this research maps the inflection points where capacity expansions, raw material price realignments, and policy-driven demand shifts converge. For executives calibrating production schedules, pricing architectures, or geographic market entries, these projections establish a disciplined foundation for scenario modeling and resource deployment.
Report Scope and Operational Content: What Decision-Makers Will Gain
PW Consulting’s Sulphur Bentonite Market study is structured to translate macro-level indicators into operational clarity. The report opens with a rigorous segmentation analysis that isolates demand patterns by product specifications, regional consumption profiles, and end-use applications. Each segment is evaluated through the lens of volume drivers, substitution risks, and pricing elasticity, enabling readers to identify where margin expansion is structurally achievable versus where competitive intensity will compress returns.
Sulphur Bentonite Market
Beyond segmentation, the research delivers a granular competitive landscape assessment. It maps enterprise positioning, manufacturing footprints, product portfolio strategies, and recent capacity deployment initiatives. The analysis goes further by integrating supply chain vulnerability mapping, evaluating how molten sulphur feedstock availability, energy cost fluctuations, and logistics constraints influence production economics. Regulatory and environmental compliance requirements are also examined in depth, particularly their impact on dust control protocols, emission standards, and plant-level operating expenditures.
To ensure strategic relevance, the report incorporates a comprehensive dashboard of recent industry developments. These timelines capture manufacturing expansions, facility inaugurations, product line extensions, and regional demand interventions that have already altered market dynamics. By contextualizing these events within broader pricing cycles and policy trajectories, the research provides a working framework for forecasting near-term supply responses and identifying windows of competitive advantage.
Competitive Landscape: Key Players and Strategic Positioning
The Sulphur Bentonite sector exhibits a moderately consolidated structure, with the top three firms commanding approximately 48.0 percent of market share and the top five reaching 58.0 percent. This concentration level suggests that scale, distribution networks, and formulation expertise remain decisive competitive moats. Yet the market continues to attract targeted expansions from both established producers and regional specialists, indicating room for differentiation through product customization, organic certification, and micronutrient integration.
Among the leading participants, several enterprises illustrate distinct strategic orientations. In Gujarat, India, Maruti Corporation has positioned itself as an active manufacturer and exporter of 90 percent sulphur bentonite, alongside micronutrient-enhanced variants incorporating zinc and copper. Its export-oriented model and focus on blended formulations reflect a strategy aimed at capturing emerging market demand for customized nutrient delivery. In Edmonton, Alberta, Keg River has built a reputation around premium bentonite sulphur fertilizers, including its Keg90S and Keg 85S lines, with particular emphasis on pastille form factors and dust mitigation. The company’s OMRI-listed organic offerings further signal a strategic pivot toward compliance-driven and sustainability-conscious buyer segments.
Globally, Tiger-Sul operates as a recognized leader in sulphur bentonite production, maintaining a broad footprint across multiple regions and emphasizing micronutrient-enhanced sulphur products. Its scale and distributionreach provide a benchmark for market positioning. In the Middle East, the National Sulphur Fertilizer Company, based in Qatar’s Messaied Industrial Area, has structured its core plant nutrient offering around high-quality sulphur bentonite, targeting substantial production capacity as part of its regional supply strategy. Meanwhile, Istanbul-based Sulfert Chemical has carved a specialized role in organic bentonite sulphur manufacturing, aligning product development with regulatory and certification preferences in export markets.
India’s Coromandel International Limited continues to expand its dedicated bentonite sulphur fertilizer manufacturing footprint, reinforcing its position within a market increasingly shaped by domestic soil health programs and import demand dynamics. In Dubai, Amarak Chemicals has advanced its portfolio beyond standard formulations to include zincated and boronated sulphur bentonite variants, recently launching a fully automated production facility designed to enhance throughput and consistency. These company profiles collectively illustrate a market where product engineering, certification pathways, and capacity agility are becoming as important as baseline volume output.
Recent Developments and Structural Industry Shifts
Several high-impact developments since early 2025 have already begun reshaping capacity allocation and regional supply balances. In March 2025, Coromandel International Limited inaugurated a second sulphur manufacturing plant at its Visakhapatnam facility, effectively doubling its bentonite sulphur capacity to 50,000 tonnes per annum. This expansion directly addresses rising domestic and export demand, while also signaling India’s broader push toward self-sufficiency in sulphur-based fertilizer inputs.
By February 2026, Amarak Chemicals commenced operations at a fully automated sulphur bentonite facility within the Jebel Ali Free Zone in Dubai, with a 60,000 tonnes per annum capacity target. The launch underscores accelerating investment in Middle Eastern production hubs, where logistics advantages and export-oriented infrastructure are being leveraged to serve both regional agricultural demand and overseas distribution channels. These capacity additions arrive against a backdrop of fluctuating molten sulphur feedstock availability, where refinery maintenance schedules and export restrictions in key producing regions have periodically constrained supply for bentonite sulphur producers.
Simultaneously, raw material pricing dynamics have introduced meaningful volatility into production economics. Average global sulphur prices have fluctuated between roughly 70 and 130 USD per metric ton through mid-2025, compelling manufacturers to recalibrate hedging strategies, inventory buffers, and pass-through pricing mechanisms. Energy cost variability and input price swings have further pressured production economics in key manufacturing zones, particularly in India and China, where cost structures are highly sensitive to feedstock and utility pricing.
Environmental and regulatory developments are equally consequential. Stricter emissions standards and dust control requirements during bentonite sulphur fertilizer production have elevated operational expenditures for manufacturers, prompting investments in closed-system processing, dust suppression technologies, and compliance-driven process upgrades. In India, government-backed fertilizer support programs and widespread soil health card distribution have amplified sulphur bentonite import volumes and domestic demand, creating an additional growth catalyst that interacts with global supply reallocations and pricing cycles.
Strategic Implications for 2026 and Beyond
For executives operating in or adjacent to the Sulphur Bentonite Market, the convergence of steady top-line growth, moderate competitive concentration, and evolving input cost dynamics demands a disciplined strategic posture. The 4.7 percent CAGR through 2032 suggests that broad market expansion will continue, but revenue capture will increasingly depend on segment selection, formulation differentiation, and supply chain resilience. Companies that can align capacity deployment with regional demand signals, manage sulphur feedstock exposure through contractual and inventory strategies, and navigate environmental compliance without sacrificing throughput will be best positioned to defend margins.
Sulphur Recovery Market
The competitive landscape also indicates that scale alone is no longer a sufficient differentiator. Enterprise strategies that incorporate micronutrient enhancement, organic certification readiness, dust control advantages, and automation-driven consistency are emerging as meaningful value drivers. Regional dynamics further complicate the equation: policy interventions in key agricultural markets, refinery-driven sulphur supply constraints, and logistics infrastructure variations require firms to maintain flexible sourcing architectures and scenario-aware production planning. In this environment, intelligence that connects macro forecasts with segment-level demand behavior, competitor capacity moves, and regulatory cost trajectories becomes a critical asset rather than a supplementary report.
How to Access the Complete Intelligence Package
This overview provides a structured preview of the market forces, competitive dynamics, and developmental milestones shaping the Sulphur Bentonite Market through 2032. However, the full research deliverable extends significantly beyond these highlights. Readers seeking detailed segment-level valuations, regional consumption mappings, pricing scenario models, competitive share analyses, and operational benchmarking frameworks will find the complete PW Consulting market study designed specifically for strategic planning, investment evaluation, and supply chain optimization. To access the full dataset, granular forecasts, and executive decision matrices, visit the official market research page and secure the complete intelligence package built for 2026-facing strategy teams.
For detailed analysis of this topic, please visit the official page: Sulphur Bentonite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


