



Dipropylene Glycol Market Hits USD 4.9B in 2025, Projects 4.14% CAGR Through 2030

Strategic Intelligence in the Dipropylene Glycol (DPG) Market: Navigating the 2026-2032 Forecast Period
The global Dipropylene Glycol (DPG) market stands at a critical inflection point as we move deeper into 2026. For procurement leaders, supply chain strategists, and market expansion teams, understanding the trajectory of this essential chemical intermediate is no longer just a matter of cost optimization; it is a strategic imperative. The DPG market, valued at 4.9 billion USD in the base year of 2025 and projected to reach 6.51 billion USD by 2032, presents a complex landscape shaped by feedstock volatility, evolving regulatory frameworks, and shifting end-user demand. This comprehensive market research study offers the granular intelligence required to make informed decisions in this dynamic environment.
Our latest report provides a deep dive into the historical performance and future outlook of the DPG sector. With a historical review spanning 2020 to 2025 and a detailed forecast period extending from 2026 to 2032, the study is designed to equip stakeholders with the foresight necessary to mitigate risk and capitalize on emerging opportunities. The compound annual growth rate (CAGR) of 4.14 percent underscore a steady, yet nuanced, expansion trajectory. However, headline figures only tell part of the story. To truly navigate the market, one must understand the underlying forces driving these numbers, from regional supply dynamics to grade-specific demand shifts.
Market Trajectory and Growth Dynamics
Analyzing the historical data reveals a resilient market foundation. After reaching 4.0 billion USD in 2020, the market witnessed a consistent upward trend, accelerating to 4.63 billion USD by 2024 and settling at 4.9 billion USD in 2025. This growth reflects the compound's versatility across diverse industrial applications. Looking ahead, the forecast period suggests continued expansion, with market size anticipated to hit 5.28 billion USD in 2026. However, astute analysis reveals that growth is not always linear. Strategic fluctuations noted in the forecast data highlight the sensitivity of the market to external pressures such as raw material costs and production scheduling, making real-time intelligence crucial for capacity planning and procurement timing.
The projected growth to 6.51 billion USD by 2032 indicates a robust long-term outlook. Yet, the path to this figure is influenced by several macroeconomic and microeconomic variables. Our research dissects these variables to provide a clear view of where value is being created and where margins might be under pressure. Understanding the interplay between supply chain constraints and demand generation is key to leveraging these forecasts effectively.
Supply Chain Pressures and Raw Material Dynamics
One of the most significant factors influencing the DPG market in 2026 is the cost of raw materials, specifically propylene oxide. As a co-product of monopropylene glycol production, DPG manufacturing is intrinsically linked to the availability and pricing of upstream feedstocks. Recent data indicates that propylene oxide prices in North America rose 7.5 percent quarter-over-quarter to 1.14 USD/KG by March 2026. This upward pressure on feedstock costs directly impacts DPG manufacturing economics, prompting strategic adjustments across the value chain.
These cost pressures have already manifested in market behavior. In April 2026, Industry leaders Dow Chemical and Monument Chemical announced price increases on Dipropylene Glycol and related glycol products. Dow Chemical specifically targeted DPG LO+ and related glycol products, citing exposure to propylene oxide feedstock pressures. Such moves signal a tightening margin environment that buyers must anticipate. Our report provides detailed analysis on how these cost pass-through mechanisms affect different regions and application sectors, enabling buyers to negotiate from a position of strength.
Technological Innovation and Sustainability Trends
Sustainability is no longer a peripheral concern in the DPG market; it is becoming a core driver of procurement decisions. Leading producers are increasingly integrating bio-based and recycled feedstocks into their portfolios to meet the growing demand for sustainable chemicals. Dow Inc.'s marketing of Dipropylene Glycol-REN LO+ with at least 50 percent ISCC PLUS certified bio-based material via the Ecolibrium mass-balance approach serves as a prime example. This innovation allows customers in personal care and industrial applications to reduce their carbon footprint without compromising product performance.
Such developments require buyers to evaluate not just the chemical properties but also the lifecycle credentials of the DPG they source. Our research assesses the availability and scalability of these sustainable grades against traditional petrochemical routes. We examine how mass-balance certification and bio-circular feedstocks are reshaping the competitive landscape and influencing customer preferences, particularly in regions with stringent environmental regulations.
Regional and Segment Growth Opportunities
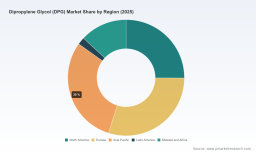
The Asia Pacific region continues to command a significant share of global DPG consumption, reflecting the broader growth of chemical-intensive industries in the region. Similarly, North America and Europe remain substantial demand centers, driven by established industrial bases and high standards for product quality and safety. Our report breaks down market dynamics across these key geographies, analyzing how local production capacities, import-export balances, and regional regulatory environments shape supply availability and pricing structures. By understanding regional nuances, stakeholders can optimize their sourcing strategies and identify untapped markets or underserved segments.
Beyond geography, the composition of the DPG market by type and application reveals critical growth vectors. Technical grades hold a prominent position, catering to broad industrial needs such as solvents and coupling agents. Pharmaceutical and electronics grades also command significant value, driven by stricter purity requirements and niche applications. The analysis covers Functional Fluids, Polyurethane and Polyester Resins, and Personal Care and Pharmaceuticals, highlighting how demand patterns differ across these verticals. For instance, while functional fluids represent a large volume segment, the personal care sector drives demand for high-purity, low-odor variants. Understanding these segmentation dynamics allows companies to tailor their product development and marketing strategies to the most lucrative opportunities.
Competitive Landscape and Industry Consolidation
The DPG market is characterized by a moderately concentrated competitive structure. Our analysis identifies a CR3 of 51.0 percent and a CR5 of 62.0 percent, indicating that the top five players hold a substantial portion of the market. This concentration suggests that major producers have significant influence over pricing, supply stability, and innovation directions. Key companies profiled in the research include Dow Inc., BASF SE, LyondellBasell Industries, Shell Chemicals, and ExxonMobil Chemical.
Each of these players brings distinct capabilities and strategic focuses to the market. Dow Inc., based in Midland, Michigan, is a primary producer of DPG Regular Grade and specialized grades such as DPG-CIR LO+, DPG-REN LO+, as well as DPG LO+ and DPG JSQI variants. Dow supplies fragrance-grade, industrial-grade, and sustainable options, leveraging its co-product status from monopropylene glycol production to offer a wide array of solutions for solvents, coupling agents, and personal care. BASF SE, headquartered in Ludwigshafen, Germany, offers DPG as a by-product of monopropylene glycol production and provides grades for use as solvents in fragrances, inks, semiconductors, leather, and hydraulic fluids, along with Care-grade humectant and solubilizer formulations.
Propylene Glycol (PG) Market
LyondellBasell Industries, with its operations in Houston, Texas, manufactures both industrial grade and fragrance-grade DPG, supplying the polyester synthesis, urethane, personal care, and industrial sectors. Shell Chemicals, based in London, United Kingdom, focuses on supplying DPG LO (low-odor) and standard grades for perfumery, cosmetics, and industrial solvents, supported by comprehensive product stewardship summaries. ExxonMobil Chemical, located in Spring, Texas, produces and supplies DPG as part of its broader glycol portfolio, serving chemical intermediates, coatings, and personal care applications. The report provides in-depth competitive profiling, examining each company's product portfolio, regional footprint, and strategic moves to help clients benchmark their position and identify partnership or acquisition opportunities.
Regulatory Compliance and Operational Safety
Operating in the DPG market requires strict adherence to regulatory standards and product stewardship protocols. Dipropylene Glycol production is a by-product of monopropylene glycol manufacturing, subjecting it to specific regulatory oversight. For instance, strict REACH registration requirements govern the safety data sheets and handling of DPG in European markets. Additionally, industrial grade DPG requires compliance with the Globally Harmonized System for transport and handling, as outlined in stewardship bulletins from major producers like LyondellBasell. These regulatory frameworks impact not only the cost of compliance but also the flow of goods across borders and the ability to enter certain markets. Our report details the regulatory landscape, providing guidance on how to navigate these requirements efficiently while maintaining operational continuity.
Executive Takeaways and Strategic Recommendations
For executives and decision-makers, the insights contained in this report translate into actionable strategies. The 4.14 percent CAGR and the projected market size of 6.51 billion USD by 2032 suggest ample opportunity, but realizing this value requires precise navigation of the complexities outlined above. Procurement teams should consider locking in supply agreements or diversifying sources in light of the April 2026 price increases and ongoing feedstock volatility. R&D and product development units can leverage the growth in sustainable grades and specialty applications to differentiate offerings. Furthermore, understanding the competitive concentration and the specific capabilities of key players like Dow, BASF, and LyondellBasell can inform partnership strategies and market entry plans.
Dipropylene Glycol (DPG) Market
The DPG market is evolving. The transition from high-volume industrial consumption to more specialized, value-driven applications, coupled with the push for sustainability and the realities of raw material cost fluctuations, demands a sophisticated approach to market intelligence. This study is designed to be that compass, offering the depth and breadth of analysis needed to thrive in the 2026-2032 period. By illuminating the hidden drivers of market performance and forecasting, we empower our clients to move beyond reactive adjustments and toward proactive, strategic growth. To access the full scope of data, detailed segmentation breakdowns, and comprehensive company profiles, we invite you to explore the complete market research report.
For detailed analysis of this topic, please visit the official page: Dipropylene Glycol (DPG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


