



PW Consulting: Automotive Auxiliary Heater Market Hits $2.2B in 2025, Thriving for 2032

Navigating the Thermal Edge: Strategic Intelligence for the Automotive Auxiliary Heater Market 2026-2032
The automotive auxiliary heater market stands at a critical inflection point where thermal comfort, emissions compliance, and electrification converge to reshape aftermarket value chains and OEM procurement strategies. As vehicle architectures grow increasingly complex and regional operating conditions demand reliable cabin and engine preconditioning, auxiliary heating systems have evolved from convenience accessories to mission-critical components. Our newly published Automotive Auxiliary Heater Market study delivers a granular, forward-looking intelligence package designed specifically to support enterprise decision-making through 2032. This overview highlights the strategic architecture of the research, the competitive forces shaping pricing and technology roadmaps, and the regulatory tailwinds that will dictate margin structures and market entry timing in the coming years.
Market Trajectory and Base-Year Dynamics
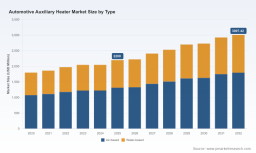
Over the past half-decade, the sector has demonstrated resilient demand expansion anchored by cold-climate markets, commercial fleet operational requirements, and the gradual migration of passenger vehicles toward supplementary heating architectures that complement main powertrains. The market’s baseline valuation for 2025 rests at approximately 2.2 billion USD, signaling a sustained recovery and incremental share capture following the volatility of the early 2020s. Historical performance from 2020 through 2024 reveals a compound trajectory marked by moderate but consistent growth, with annual valuations progressing from 1.8 billion USD to roughly 2.05 billion USD before crossing the 2.2 billion USD threshold in the base year.
Automotive Seat Heater Market
Looking ahead, the forecast horizon from 2026 to 2032 projects a compound annual growth rate of 4.5 percent, steering the market toward a 3.0 billion USD milestone by 2032. These directional figures provide a stable macroeconomic scaffold for capacity planning, channel investment, and portfolio prioritization. Yet, aggregate valuations alone do not reveal the operational leverage points that executives need. Our analysis dissects demand concentration across product architectures, application verticals, and geographic corridors without flattening the nuance that actually guides sourcing, localization, and pricing strategy. The report quantifies how revenue is structurally distributed across air-based and water-based heating modalities, how passenger car and commercial vehicle segments command differing margin profiles, and how regional demand intensity drives localization requirements for assembly, service networks, and regulatory compliance.
Equally important is the competitive concentration backdrop. The top three participants collectively account for roughly one-third of market revenue, while the top five expand that share to just under half. This fragmented-but-tiered structure creates a strategic environment where scale advantages matter, but differentiation through technology, service ecosystems, and regional compliance capabilities can still yield outsized share gains. The study examines supplier positioning, channel influence, and OEM dependency patterns to help firms anticipate pricing pressure, negotiate component roadmaps, and identify partnership opportunities before the next consolidation wave.
Automotive Auxiliary Heater Market
Why This Study Matters for 2026 Decision-Making
Entering 2026, executives face a set of interlinked imperatives: aligning product portfolios with electrification mandates, managing customs and duty exposure in cross-border supply chains, preparing for evolving safety and emissions oversight, and timing capacity investments against uncertain demand pacing. This report is engineered to convert those uncertainties into a sequenced decision framework. Rather than offering static sizing tables, the research maps the operational levers that determine commercial outcomes in real market conditions.
- Strategic sizing and scenario planning that translate baseline and forecast valuations into capacity, inventory, and capex decisions calibrated for 2026-2032
- Segment-level demand characterization across heater types, vehicle applications, and regional corridors to prioritize where to allocate engineering resources and commercial efforts
- Competitive benchmarking of incumbent manufacturers and emerging entrants, including product line breadth, OEM relationships, and recent innovation cadence
- Regulatory and trade exposure assessment that connects safety oversight, duty classification, and environmental standards to landed-cost modeling and market-entry sequencing
- Technology transition mapping that tracks the shift from fuel-operated heating platforms toward electric and hybrid auxiliary architectures, with implications for component sourcing and service reliability
The analytical depth is designed to support cross-functional teams. Procurement leaders can use the supplier landscape and concentration metrics to stress-test sourcing strategies and negotiate long-term agreements with a clearer view of rival capacity. Product and engineering teams gain visibility into how application requirements and regional operating conditions influence performance expectations and warranty profiles. Commercial and market-development teams receive the segmentation and regional context needed to determine where to localize distribution, service, and technical support. And strategy leaders can integrate the regulatory and trade dimensions into investment sequencing, prioritizing markets where duty exposure, safety compliance, and emissions definitions create either friction or first-mover advantage.
Competitive Landscape and Innovation Cadence
The supplier ecosystem is anchored by a small group of technically sophisticated incumbents, each with distinct positioning across OEM channels, application segments, and heating architectures. Webasto, headquartered in Gilching, Germany, has built a broad portfolio spanning OEM diesel fuel-operated parking heaters such as the Air Top, Thermo Top, and Thermo Plus series, alongside electric PTC auxiliary heaters serving passenger cars, commercial vehicles, buses, and heavy-duty trucks. The company’s recent activity signals a deliberate push toward higher-power electric heating platforms and smarter parking heat solutions. In April 2026, Webasto launched modular PTC air heaters delivering up to 2,100 watts of heating power tailored for electric commercial vehicles, reinforcing the strategic pivot toward electrified thermal management. In October 2025, the firm announced the Thermo Top Evo Smart parking heater for passenger cars with up to 5 kW heating capacity and extended warranty options, a move that emphasizes user convenience and post-sale value. Earlier in March 2025, Webasto showcased the Air Top Pro 25 fleet heater at Work Truck Work in Indianapolis, underscoring continued attention to commercial vehicle applications.
Eberspächer, based in Esslingen, Germany, maintains a complementary but distinct footprint with OEM fuel-operated air heaters, notably the Airtronic series, and pre-heater solutions targeting passenger cars, commercial vehicles, and special-purpose applications. Valeo, headquartered in Poissy, France, concentrates its auxiliary heater offering on OEM diesel auxiliary heaters under the Thermo+ series, with a particular emphasis on commercial vehicles and buses. Espar, operating from Germany, rounds out the core group with OEM fuel-operated parking heaters and auxiliary heaters designed for commercial vehicles, vans, and trucks. Together, these players illustrate the dual tension shaping the market: incumbents must defend share in established fuel-operated segments while simultaneously expanding electric and modular offerings to align with fleet electrification and changing emissions expectations.
The study examines how these profiles translate into competitive dynamics. It evaluates product differentiation through heating power ranges, control intelligence, warranty structures, and application focus. It also assesses how recent launches and trade-show presentations indicate where each supplier is directing engineering investment, which customer segments they are prioritizing, and how their roadmaps may influence pricing and availability over the forecast period. By mapping innovation cadence alongside channel reach, the report helps decision-makers anticipate where competition will intensify, which OEM relationships may shift, and where niche application expertise can serve as a durable moat.
Market Dynamics: Regulation, Trade, and Technology Shifts
Market outcomes in this sector are increasingly shaped by oversight, classification, and definitional clarity as much as by pure demand growth. Safety monitoring remains a persistent factor. In 2025, NHTSA safety recalls affected Valeo Thermo+ auxiliary heaters installed in commercial buses, alongside electric auxiliary heaters in certain BMW models. These events illustrate how component reliability, integration complexity, and fleet operating conditions can quickly convert technical performance into reputational and compliance risk. For OEMs and Tier-1 suppliers, such developments reinforce the need for rigorous validation protocols, traceability, and service readiness.
Trade policy adds another layer of strategic complexity. In February 2026, US Customs classified auxiliary heater units under HTS 8419.50.50 with a 4.2 percent ad valorem duty rate. This classification has direct implications for landed-cost modeling, sourcing geography, and inventory placement. Companies that rely on cross-border components or finished-unit importation must revisit duty exposure, evaluate assembly localization options, and assess whether regional value creation can improve cost competitiveness while reducing tariff risk. Our report incorporates these trade dimensions into market-entry and supply-chain analysis so that commercial teams can quantify cost sensitivity and align procurement with logistics strategy.
Regulatory classification is also sharpening. The EPA CHDV program manual released in July 2025 explicitly defines an auxiliary heater as a supplementary heating system for the passenger compartment, engine, or both. This definition carries operational significance because it clarifies reporting boundaries, operational scope, and compliance expectations. Meanwhile, Federal Motor Vehicle Safety Standards 571.301 require compliance for auxiliary heating systems in school buses, as reflected in Nevada Minimum School Bus Standards for 2026. These requirements matter because they influence which applications demand more stringent safety engineering, which customer segments will tolerate higher validation costs, and where service and support models must be adapted to meet public-sector procurement expectations.
Beyond regulation, technology adoption is shifting demand composition. Webasto has reported increasing adoption of electric auxiliary heaters in commercial vehicles as fuel-powered vehicles are phased out. This trend signals a structural transition in the commercial segment that will influence heater architecture mix, component sourcing, and supplier roadmaps. Electric auxiliary heaters are not simply substitutes; they change thermal management logic, integrate more tightly with vehicle electrical systems, and may modify warranty requirements and service practices. Understanding the pacing of this transition is essential for firms deciding whether to invest in fuel-operated capacity, electric heating platforms, or hybrid offerings that hedge across multiple powertrain paths.
What the Report Delivers in Practice
The study is structured to move from strategic context to actionable intelligence. It opens with market sizing and growth dynamics, grounding executives in baseline and forecast valuations while establishing the 4.5 percent CAGR trajectory as the analytic spine for scenario work. From there, it progresses into segmentation-driven analysis that reveals how revenue is distributed across heater types, application categories, and regional markets. These characterizations are presented in a way that highlights where demand intensity, margin potential, and competitive pressure converge, without flattening the market into overly simplified aggregates.
The competitive section profiles key participants and evaluates their offerings, recent developments, and strategic focus areas. It incorporates product launch activity, trade-show positioning, and technology direction to help readers infer where investment is flowing and which segments may face greater rivalry. The dynamics section integrates regulatory, trade, and technology factors into a single operating lens, so that compliance risk, duty exposure, and electrification transition are treated as interrelated business drivers rather than isolated footnotes. The report also addresses concentration metrics and supplier influence to inform negotiation posture and partnership strategy.
Throughout, the analysis is designed for practical use. Commercial teams can leverage segmentation context to prioritize geographies and applications. Engineering and product teams can align heater architecture roadmaps with application requirements and electrification trends. Procurement and supply-chain leaders can factor duty classification, recall risk, and supplier concentration into sourcing and inventory strategies. Executives can combine the forecast scaffolding with regulatory and competitive intelligence to time investments, define market-entry sequencing, and calibrate portfolio commitment against uncertainty.
How to Use This Intelligence
The emphasis of this research is on decision readiness. The market outlook provides the numerical foundation, but the strategic value lies in how that foundation connects to real operating choices. Firms evaluating capacity expansion can use segmentation and regional insights to determine whether to invest broadly or concentrate resources in the most favorable demand corridors. Suppliers weighing product architecture can use the technology-transition signals and recent launch patterns to decide whether to expand electric offerings, refine fuel-operated platforms, or pursue modular systems that can be configured across multiple vehicle categories. OEM-adjacent businesses can use the recall and compliance context to strengthen validation, service readiness, and documentation processes that reduce downstream risk.
For market-entry planning, the report’s combination of concentration data, competitive profiles, and regulatory detail helps identify where incumbents are strong, where customer requirements may be underserved, and where classification or duty exposure alters the cost equation enough to influence localization choices. For portfolio strategy, the interplay between passenger car and commercial vehicle applications, along with the shifting balance between air-based and water-based heater types, supports a more precise allocation of engineering and commercial resources than aggregate market size alone would allow.
Where to Go Next
This overview provides the strategic frame, but the full intelligence package contains the segment-level detail, competitive analysis, regulatory mapping, and scenario scaffolding required to convert direction into execution. To access the complete market study, including the segmentation structures, supplier positioning, and operating-context analysis that underpin the 2026-2032 outlook, visit the source report page. There you will find the full dataset, qualitative insights, and decision-support materials needed to align your strategy with the market’s next phase of growth.
For detailed analysis of this topic, please visit the official page: Automotive Auxiliary Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


