



PW Consulting: Mobile App Testing Market Hits $7.7B in 2025, Projected 17.09% CAGR to $23.23B by 2032

The Mobile Application Testing Services Market: A Strategic Imperative for 2026
The digital ecosystem of 2026 no longer tolerates performance gaps, security lapses, or fragmented user experiences. As mobile applications become the primary interface for commerce, healthcare, finance, and enterprise operations, the discipline of validating these applications has evolved from a post-development checkpoint to a continuous, strategic capability. Our latest Mobile Application Testing Services Market research captures this inflection point. It provides decision-makers with a structured, forward-looking view of market trajectory, competitive positioning, and operational dynamics that will shape procurement, partnership, and investment choices throughout the forecast horizon.
The market has already demonstrated a clear upward momentum. Measured in billions of USD, valuation climbed from 3.5 in 2020 to 7.7 in 2025, reflecting sustained enterprise investment in quality engineering and the mainstream adoption of structured testing programs. Projections extend this arc to 8.72 in 2026, 10.61 in 2027, and onward to 23.23 by 2032. Sustained at a compound annual growth rate of 17.09 percent across the 2026 to 2032 forecast period, this expansion signals more than incremental demand. It reflects a structural reallocation of operational budgets toward testing ecosystems that can keep pace with device fragmentation, regulatory scrutiny, and user expectations for seamless performance. The figures themselves tell a story of maturation, but the strategic implications lie beneath the surface—in how service models are reorganizing, where cost structures are concentrating, and which operational capabilities will separate resilient providers from commoditized vendors.
Game Testing Service Market
Decoding the Structural Drivers
Several interlocking forces are reshaping demand. Labor remains the primary operational cost in mobile application testing services, with specialized human expertise in manual and automated testing driving day-to-day economics. Labor regulations in key regions continue to influence how organizations build, scale, and source QA teams, making workforce strategy as critical as technology selection. At the same time, compliance requirements are no longer peripheral considerations. Testing for GDPR, HIPAA, and PCI-DSS in mobile environments requires dedicated frameworks that protect data privacy and security across regulated sectors such as healthcare and finance. Enterprises are increasingly mandating ISO 29119-aligned processes to standardize quality assurance and mitigate risk, embedding testing standards directly into procurement criteria.
Infrastructure trends are equally consequential. Cloud-based device labs and real-device infrastructure have become standard for scalable testing, allowing teams to manage device fragmentation and frequent OS updates without accumulating heavyweight in-house hardware fleets. Consumer expectations continue to escalate: users now demand consistent performance across a widening array of screen sizes, network conditions, and operating system versions. This reality raises the cost of post-launch defects and amplifies the value of comprehensive testing programs that catch issues before they reach production. Together, these dynamics create a market in which testing services are evaluated not only on defect detection rates but also on compliance readiness, deployment speed, and the ability to absorb volatility in device and platform landscapes.
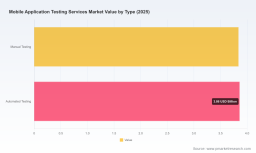
Demand is distributed across a balanced set of service categories and delivery models. Manual and automated approaches each hold substantial share, reflecting a pragmatic blend in which exploratory, UX-sensitive validation coexists with repeatable, high-velocity automation pipelines. The application spectrum spans native, web, and hybrid environments, each introducing distinct validation challenges around platform-specific behaviors, cross-browser consistency, and integrated architecture complexity. Regional activity reflects similarly diversified engagement, with testing demand concentrated across major economic corridors and emerging adoption zones. While headline figures illuminate the scale of the opportunity, the operational reality is more nuanced: procurement teams must weigh service depth, tooling integration, compliance coverage, and geographic delivery capacity against their own development cadence and risk profile. These are precisely the trade-offs our research quantifies and contextualizes.
Inside the Research: Practical Intelligence for Decision Makers
This report is designed as an operational reference rather than a high-level survey. It maps the market across the dimensions that matter to strategy, procurement, and investment teams, translating macro trends into actionable decision inputs.
The analysis covers market sizing and forward projections with a clear view of how growth compounds across the forecast window. It breaks down the market by testing type, by application category, and by region so that readers can align their own footprint with broader demand patterns without getting lost in fragmented metrics. The segmentation structure is paired with concentration analysis that shows how market share distributes across leading participants, offering a realistic picture of competitive saturation and whitespace. Total market concentration indexed by CR3 and CR5 highlights the extent to which leadership is consolidated or dispersed, helping stakeholders gauge incumbent influence and entry dynamics.
Beyond sizing, the report delivers practical content that supports execution. It examines how service providers structure offerings across functional, performance, security, usability, accessibility, and localization testing. It evaluates automation maturity, real-device and cloud-based testing capabilities, and the role of AI-assisted quality engineering in accelerating validation cycles. It also addresses procurement-relevant considerations such as outsourcing models, compliance alignment, certification standards, and the operational implications of labor-intensive QA workflows. For organizations comparing vendors, building internal centers of excellence, or assessing market entry, the study provides a structured lens for evaluating fit, scalability, and long-term defensibility.
Competitive Landscape: Who Shapes the Market and How
The mobile application testing services arena is defined by a diverse set of operators whose differentiating strengths span geography, delivery model, and technological specialization. Understanding how these players position themselves is essential for interpreting pricing dynamics, partnership options, and service reliability.
DeviQA, headquartered in Warsaw, Poland, focuses on end-to-end mobile app testing for iOS and Android. Its profile emphasizes functional, performance, security, and automation testing, with particular attention to AI-powered QA and outsourcing models. This positioning makes it relevant for organizations seeking integrated service delivery with an eye toward efficiency gains through intelligent automation. TestingXperts operates with global reach and regional hubs, including the Philippines, and delivers full-stack mobile testing that spans functional, usability, performance, security, localization, and cloud or real-device validation. Its emphasis on AI-led automation aligns with enterprises looking to scale testing coverage while managing cycle time. pcloudy offers a cloud-based testing platform that supports more than 5000 real devices for both manual and automated testing on Android and iOS, augmented by AI agents and integrations. Its platform orientation appeals to teams that prioritize device diversity, infrastructure elasticity, and tooling interoperability.
BrowserStack maintains a global footprint centered on real-device cloud testing for mobile apps across more than 2000 iOS and Android devices. Its support for automated testing via Appium and custom device labs positions it as a strong fit for engineering teams that require broad device coverage and programmable test execution. a1qa, based in Decatur, Georgia, provides mobile testing on real devices with functional, performance, and QA services, alongside crowdsourced and automation options. This hybrid model is useful for organizations balancing controlled QA environments with broader, scenario-rich validation. Qualitest, headquartered in London, delivers end-to-end mobile and web testing that incorporates security, performance, and accessibility, with a focus on AI-powered quality engineering. Its breadth makes it relevant for enterprises seeking unified assurance across multiple digital touchpoints.
Testriq, operating from Mumbai, India, emphasizes iOS and Android QA with performance testing, security pen-testing, and ISO 29119-compliant services. Its standards-aligned approach supports clients in regulated or risk-sensitive contexts. TestMatick, with a New York base and a Ukraine office, verifies apps under real-life conditions and leverages AI-driven automation, an approach that resonates with teams prioritizing realistic usage simulation and automation-led efficiency. ScienceSoft, based in McKinney, Texas, covers the full range of mobile app testing including functional, performance, security, usability, and accessibility, supported by ISTQB-certified engineers. Its certification-oriented talent model appeals to organizations that value formalized QA competency and consistent service quality.
Taken together, these players illustrate a market that rewards specialization without sacrificing breadth. Providers differentiate through real-device scale, automation maturity, compliance expertise, geographic delivery capacity, and the ability to combine human judgment with AI-enhanced workflows. For buyers, the strategic question is not simply who offers the lowest cost but which provider can integrate into existing development pipelines, meet sector-specific compliance demands, and sustain quality as application portfolios grow more complex.
Strategic Implications for 2026 Decision Making
Entering 2026, organizations must treat mobile application testing not as a discretionary expense but as a core enabler of product reliability, regulatory compliance, and customer retention. Several strategic implications emerge from the current market trajectory.
- Budget allocation should reflect the blended nature of demand. As manual and automated testing both hold meaningful share, investment plans need to support exploratory validation and repeatable automation in proportion to release cadence, user sensitivity, and risk exposure.
- Compliance readiness is becoming a procurement discriminator. With GDPR, HIPAA, and PCI-DSS requirements shaping testing for regulated applications, buyers should prioritize providers that can demonstrate structured privacy and security validation rather than treating compliance as a downstream checklist.
- Infrastructure strategy directly affects scalability. The normalization of cloud-based device labs and real-device infrastructure means that organizations can expand coverage without proportionate hardware investment, but they must still evaluate tool integration, data security, and device representativeness.
- Labor economics remain central. Because specialized QA labor accounts for the primary operational cost, workforce planning—whether through in-house hiring, outsourced partnerships, or managed services—should be modeled alongside automation roadmaps to avoid bottlenecks and cost escalation.
- Standards adoption is a signal of operational maturity. ISO 29119 alignment and ISTQB-certified engineering capabilities offer tangible indicators of process discipline, which matters when quality assurance must be auditable and repeatable across multiple product teams.
- Competitive selection should weigh delivery model fit. Some providers emphasize platform scale and real-device coverage, others focus on AI-assisted automation, and still others build advantage through compliance depth or regional delivery capacity. The right choice depends on the organization’s release rhythm, risk profile, and integration requirements.
Why This Research Matters Now
Market growth at a 17.09 percent CAGR through 2032 is not merely a statistical headline; it is a signal that testing services are moving from supportive function to strategic investment area. As valuation expands from 8.72 in 2026 toward 23.23 by 2032, the stakes for selecting the right testing strategy, provider, and operating model rise in tandem. Enterprises that delay structured evaluation risk higher defect exposure, slower release cycles, and weaker compliance posture. Those that act early can align procurement with demand patterns, optimize cost structures, and build quality capabilities that compound over time.
Mobile Application Testing Services Market
This research captures the market at a moment when device diversity, regulatory pressure, and user expectations are all intensifying simultaneously. It is designed to help leaders navigate that complexity with clarity. The complete study provides the detailed segmentation, concentration metrics, competitive profiles, and forward projections needed to support procurement decisions, partnership strategies, internal capability planning, and investment assessments. For decision-makers who need more than surface-level market color, the full report offers the depth required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Mobile Application Testing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


