



PW Consulting Report: Hemodialyzer Market to Hit $6.3 Billion by 2032, 6.5% CAGR

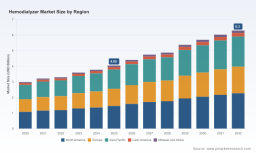
Strategic Blueprint for the Hemodialyzer Market: Navigating a $6.3 Billion Horizon Through 2032
The global hemodialysis ecosystem stands at a decisive inflection point. As patient volumes expand, reimbursement frameworks tighten, and membrane technologies diverge toward higher solute clearance, corporate strategy can no longer rely on legacy volume assumptions or static procurement models. Our newly released market intelligence study on hemodialyzers supplies the analytical architecture required to convert structural tailwinds into executable decision pathways. Covering a historical window from 2020 through 2025 and projecting forward to 2032, the analysis translates macro-level expansion into actionable intelligence for product planning, procurement, pricing architecture, and competitive positioning.
The overarching trajectory is unambiguous. Market value, measured in USD billions, has consistently advanced across the past half-decade and is projected to sustain that momentum through the end of the forecast period. Base-year positioning in 2025 translates into a 2026 opening that sets the stage for a measured yet compounding expansion cycle, culminating in a multibillion-dollar endpoint by 2032. The implied compound annual growth rate across the forecast horizon signals a market that is not merely scaling but progressively re-rating itself around clinical performance, membrane selection, and therapy modality differentiation. For executives, this is not a story of passive demand growth; it is a signal that product architecture, supply continuity, and clinical value propositions will increasingly determine share capture.
Why This Study Matters for 2026 Decision-Making
The 2026 operating environment introduces a layered set of strategic variables that demand more than top-line market sizing. Reimbursement calibration, regulatory classification pathways, water-quality compliance standards, and raw-material cost structures are reshaping the economics of dialyzer procurement and therapy configuration. Our study is engineered to place each of these forces into a single decision-ready framework so that leadership teams can move from awareness to action without stitching together fragmented inputs.
Dialyzer Market
For procurement and supply-chain leaders, the analysis provides the segmentation lenses needed to evaluate where demand is consolidating, where alternative membrane configurations are gaining traction, and how regional deployment patterns influence inventory planning. For commercial and R&D teams, the study maps the divergence between high-flux platforms and lower-flux alternatives, giving product strategists a clearer understanding of where clinical differentiation, therapy expansion, and portfolio alignment are likely to create durable advantage. For corporate development and investor-facing teams, the concentration profile of the competitive landscape offers a benchmark for assessing consolidation risk, partnership logic, and market-entry realism.
Crucially, the study avoids static projection and instead frames growth as a function of therapy adoption, membrane material economics, and regulatory-driven product classification. This allows decision-makers to test scenarios: what happens if expanded solute removal therapies scale faster in outpatient settings? What happens if reimbursement adjustments alter facility economics and shift purchasing behavior? The research is built to support those stress tests with structured evidence rather than anecdotal narrative.
Market Scale, Trajectory, and the Investment Signal
The historical arc establishes a clear baseline. Between 2020 and 2025, market value climbed in a stepwise pattern, reflecting both steady dialysis volume expansion and incremental upgrades in device selection. The 2025 base year anchors the analysis in a market that has already absorbed years of incremental demand and is now positioned for the next phase of structural expansion. From that base, the 2026 forecast opens a meaningful growth step, and the sequential trajectory through 2032 maps a market that continues to widen rather than plateau.
This path matters because it reframes hemodialyzers from commoditized disposables into clinically and economically differentiated inputs. As therapies evolve toward broader solute removal profiles and higher-efficiency modalities, the value captured by each procedure is increasingly linked to the membrane, the device class, and the compatibility of the delivery system. The study highlights that market growth is not solely a volume story; it is also a composition story. The mix shift toward higher-performance configurations is a critical variable for pricing strategy, contract negotiation, and product roadmap prioritization.
For executives, the strategic takeaway is straightforward: planning around a single aggregate figure obscures the real decision points. What matters is the convergence of therapy trends, reimbursement dynamics, and product-class differentiation, all of which determine where margin, share, and operational resilience will be won or lost.
Segment Architecture and Decision Value
The report dissects the market along multiple strategic axes that directly inform commercial, procurement, and clinical-strategy discussions. Type-based segmentation distinguishes among high-flux dialyzers, low-flux dialyzers, and other device configurations, giving R&D and commercial teams a structured view of where performance-based differentiation is concentrated and where price-sensitive purchasing may dominate. This distinction is particularly relevant as therapy protocols continue to evaluate trade-offs between clearance targets, membrane compatibility, and cost-per-procedure economics.
Application-focused analysis clarifies the dominant clinical context in which hemodialyzers are deployed, anchoring demand patterns to the core hemodialysis procedure environment. This lens matters because outpatient facility economics, session frequency, and modality mix directly influence procurement volume, device lifespan assumptions, and contract structures. Understanding how the application environment shapes usage is foundational for forecasting demand stability and evaluating whether growth is being driven by volume expansion, therapy upgrade, or both.
Regional segmentation is presented as a geographic demand map rather than a static share table, enabling supply-chain and market-entry teams to see where deployment intensity, clinical infrastructure, and purchasing environments diverge. This regional perspective supports more precise capacity planning, localization decisions, distributor strategy, and risk assessment around logistics or regulatory variation. The study intentionally preserves this segmentation at a strategic level so that readers can identify where to focus commercial attention without being distracted by superficial percentage-based breakdowns.
Hemodialyzer Market
In parallel, the analysis integrates raw-material context, emphasizing that polyethersulfone-based membrane systems constitute the primary material foundation for high-flux configurations, with cost behavior tied to medical-grade extraction and processing requirements. For procurement and product-cost strategists, this linkage between membrane material and device economics is essential for scenario modeling around input-cost volatility, supplier qualification, and margin protection.
Competitive Landscape: Scale, Differentiation, and Consolidation Signals
The competitive environment reflects both entrenched incumbents and specialized players pursuing differentiated membrane technology, therapy compatibility, and regional distribution strength. Market concentration metrics indicate that a relatively small group of leading participants commands a substantial share of total industry value, while a broader field of manufacturers competes on product design, membrane quality, and therapeutic alignment. This dual structure has direct implications for pricing power, partnership opportunity, and entry feasibility.
Fresenius Medical Care AG & Co. KGaA remains a dominant force in high-flux device supply and high-volume hemodiafiltration-compatible configurations, with reported dialyzer distribution volumes that underscore its scale advantage and global reach. Baxter International Inc. continues to position around advanced therapy membranes and expanded solute removal platforms, including class II device profiles associated with broader clearance targets. Nipro Corporation has advanced its ELISIO membrane platform with a focus on middle-molecule toxin removal, reinforcing the competitive relevance of membrane engineering as a differentiation vector. Asahi Kasei Corporation supplies high-flux product lines that align with performance-oriented dialysis workflows, while B. Braun Melsungen AG maintains a presence through polyethersulfone-based high-flux configurations.
Toray Industries, Inc. contributes advanced membrane technology to the high-flux segment, and Nikkiso Co., Ltd. supports the ecosystem through delivery-system compatibility that intersects with dialyzer usage. Outset Medical, Inc. represents a different competitive angle, integrating hemodialyzer components into a consolidated hemodialysis platform and illustrating how device-plus-system designs can alter procurement and adoption dynamics. Medica S.p.A. offers both high-flux and low-flux polyethersulfone options for global distribution, and Vantive US Healthcare, LLC extends the THERANOVA device family through distribution and sales activity aligned with expanded solute removal therapy.
The competitive base also includes regional and specialized manufacturers such as Kawasumi Laboratories, Inc., JMS Co., Ltd., Shandong Weigao Group Medical Polymer Co., Ltd., Allmed Medical Care Holdings Limited, Farmasol, WEGO Group, and Dialife SA, each contributing to supply diversity, regional coverage, and segment-specific product positioning. For strategic planners, the relevant insight is not simply who is present, but how product architecture, therapy compatibility, and geographic reach shape competitive resilience. Scale players can pressure pricing and supply reliability; specialized players can win on membrane performance, clinical fit, or regional responsiveness.
Industry Dynamics Shaping the 2026 Operating Environment
Multiple external forces are compressing decision timelines and raising the cost of strategic lag. On the regulatory side, hemodialyzers associated with expanded solute removal profiles are classified under Class II with special controls, a designation that shapes product development pathways, documentation burden, and market-access timing. This classification environment means that product differentiation must be paired with regulatory readiness; clinical promise alone does not guarantee commercial velocity.
On the standards side, water-quality and reprocessing requirements continue to anchor operational compliance. AAMI-aligned expectations for bacterial counts and endotoxin thresholds in dialysate preparation and device reprocessing create a compliance floor that affects facility operations and, indirectly, device selection and service models. For manufacturers and suppliers, these standards reinforce the importance of consistency, traceability, and compatibility with reprocessing or water-treatment workflows.
Reimbursement dynamics add another layer of strategic pressure. Updated ESRD PPS payment parameters for 2026 adjust the base rate and recalibrate how dialysis service payments relate to device usage in outpatient settings. Because reimbursement logic influences facility economics, it also influences procurement behavior, contract negotiation, and the willingness of providers to adopt higher-cost, performance-differentiated devices. Strategy teams that ignore the reimbursement-to-purchasing link risk misreading demand durability and pricing tolerance.
In parallel, raw-material cost behavior remains a sensitive variable for high-flux manufacturing, particularly where medical-grade polyethersulfone extraction drives input economics. This connects directly to margin planning, supplier diversification, and procurement hedging. Recent corporate activity reinforces the competitive intensity of this environment: broader commercialization of high-volume hemodiafiltration-compatible systems, launches optimized for middle-molecule toxin removal, introductions of expanded solute removal devices under HDx-oriented therapy frameworks, and catalog expansions of polyethersulfone-based high-flux and low-flux configurations all indicate that firms are actively competing on clinical utility, therapy compatibility, and global availability.
What the Report Delivers: Operational Intelligence, Not Just Market Sizing
This study is structured to support execution rather than simply describe the market. It combines historical baselines, forward projections, segmentation lenses, competitive profiling, and dynamic factor analysis into a decision framework that can be used across commercial, procurement, R&D, and corporate strategy functions. The report's value lies in its ability to connect market expansion to the operational questions that determine performance: which device classes are gaining strategic relevance, where demand is being shaped by therapy evolution, how competitive concentration affects pricing and negotiation leverage, and which regulatory or reimbursement shifts deserve active monitoring.
Readers will find structured coverage of the market's expansion path, the composition of demand across device types and application contexts, and the geographic distribution of opportunity and risk. Competitive profiles are presented not as static company summaries but as strategic snapshots that highlight scale, product focus, and recent commercialization activity. The study also integrates the compliance, reimbursement, and raw-material forces that influence both supply economics and purchasing behavior. By tying these elements together, the report gives decision-makers a coherent basis for scenario planning, portfolio alignment, and market-entry evaluation.
What Remains Inside: Accessing the Full Strategic Picture
The overview presented here is deliberately designed to establish analytical credibility while reserving the complete segmentation detail, regional deployment patterns, application-level demand structures, and precise market-value breakdowns for the full report. Those components are essential for procurement modeling, product-roadmap calibration, contract strategy, and competitive benchmarking, but they are most useful when examined in the full analytical context rather than as isolated figures.
For teams ready to move from directional insight to actionable planning, the complete study provides the depth required to support quantitative scenario work, regional prioritization, and competitive positioning decisions. The aggregate trajectory tells leaders that the market is expanding and re-rating around performance; the full report tells them exactly where to concentrate resources, which segments justify closer scrutiny, and how the competitive field is likely to behave as therapy formats, reimbursement rules, and membrane economics continue to evolve.
In a market moving toward a multi-billion-dollar endpoint over the forecast period, the organizations that outperform will be those that treat hemodialyzers as a strategic interface between clinical performance, purchasing economics, and regulatory reality. This study is built to help leadership make that transition with discipline, precision, and a clear line of sight from market intelligence to operational decision-making.
For detailed analysis of this topic, please visit the official page: Hemodialyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


