



PW Consulting: Hemoperfusion Market Hits $987.6M, 12.45% CAGR to 2032

The Hemoperfusion Market in 2026: Strategic Intelligence for Executive Decision‑Making
A PW Consulting Market Research Introduction
Healthcare leaders and medical device strategists are operating in an environment where extracorporeal blood purification is transitioning from supportive intervention to central therapeutic modality. Our latest Hemoperfusion Market study is designed to convert that structural shift into actionable intelligence for 2026 planning cycles. Rather than delivering generic trend commentary, this report provides a disciplined framework for capital allocation, portfolio positioning, and competitive readiness.
The purpose of this preview is straightforward. We want you to understand the analytical rigor behind the study, see how macro momentum connects to on‑the‑ground business decisions, and recognize the practical tools embedded in the research. At the same time, we deliberately hold back the most granular figures here, because the full strategic value lies in the complete segmentation architecture, scenario modeling, and competitive mapping available in the published report.
Why 2026 Is a Defining Year for Hemoperfusion Strategy
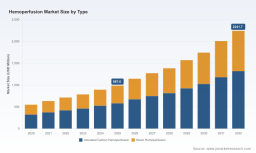
The market has already crossed a meaningful inflection point. Over the 2020–2025 historical window, the industry expanded from roughly $550.15 million to $987.6 million, reflecting sustained demand for advanced toxin and metabolite clearance technologies. That pace is not slowing. Our forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 12.45% . Current-year market size is evaluated at approximately $1,145.02 million , with continued growth anticipated through the end of the forecast horizon as adoption broadens across critical care, hepatology, and toxicology settings.
For executives, the strategic implication is clear: 2026 is not simply another year of incremental growth. It is a decision window. Organizations that wait for the next cycle of mature consensus often expose themselves to pricing pressure, crowded distribution channels, and reactive product roadmaps. The companies that move now are doing so with a better map of where demand is concentrated, how regulatory pathways are evolving, and which technological platforms are gaining clinical credibility.
This study was built with that decision window in mind. It connects historical performance to forward-looking scenarios so you can evaluate not only what the market looks like today, but how the trajectory may unfold through 2032 and what that implies for manufacturing, partnerships, and commercial execution.
What the Research Delivers: Practical Intelligence, Not Just Top‑Line Numbers
A market study is only useful if it changes how teams spend time and capital. Our hemoperfusion research was designed to support cross-functional planning rather than sit passively on a shelf. The report integrates the following operational components:
- Segment-level demand architecture: The analysis breaks the market down along the dimensions that matter for product strategy, procurement planning, and clinical positioning. This allows you to see where revenue concentration is forming and where whitespace opportunities may emerge.
- Historical and forecast continuity: By pairing a ten-year historical view with a forward-looking projection to 2032, the study enables trend validation instead of reliance on single-year snapshots. That continuity is essential when you are evaluating whether a growth signal is durable or cyclical.
- Competitive positioning framework: The report examines how leading participants differentiate through technology platform, clinical indication focus, and distribution strategy. The goal is to help you interpret competitive moves in context rather than in isolation.
- Regulatory and compliance navigation: Because sorbent hemoperfusion systems are classified as Class II medical devices under 21 CFR 876.5870, with Premarket Approval or PDP requirements for hepatic coma and metabolic disturbance indications, regulatory strategy is not a side note. It is part of the commercial equation. The study addresses these dynamics so that compliance planning is incorporated into market entry and expansion decisions.
- Scenario-oriented planning inputs: The research is structured to support sensitivity discussions around adoption trajectories, indication mix, and regional execution priorities. This makes the output useful for both strategic planning and operational forecasting.
Each component is designed to answer a specific executive question: Where should we compete? What indications deserve the strongest commercial focus? Which technological approaches are most defensible? And how do regulatory and reimbursement realities shape the speed and shape of market entry?
Segmentation That Matters for Product and Commercial Strategy
The report’s segmentation is built to support decisions, not simply to describe the market. The starting point is the technology and material dimension, where the study examines the relative commercial footprint of Activated Carbon Hemoperfusion and Resin Hemoperfusion . These categories reflect different adsorbent behaviors, manufacturing considerations, and clinical utilization patterns, which means they carry distinct implications for R&D prioritization, supply chain strategy, and customer education.
From an application perspective, the research captures how clinical demand is distributed across indications including Hepatic Encephalopathy , Autoimmune Diseases , Drug Overdose , Specific Intoxications , and Others . This is critical because application mix directly influences procurement cycles, clinical evidence requirements, and the way a product story is positioned within hospital formularies and specialty departments. A portfolio that performs well in one indication may need a very different adoption plan in another.
The geographic dimension further sharpens the picture. The study maps demand across major regions including North America , Europe , Asia Pacific , Latin America , and Mideast and Africa . Regional analysis matters because market access patterns, institutional procurement behavior, and clinical adoption pathways differ materially from one geography to another. A strategy that assumes uniform global demand will almost always misallocate resources. By contrast, region-specific interpretation helps executives prioritize launch sequencing, distributor partnerships, and clinical engagement efforts.
Throughout the segmentation analysis, the report maintains a consistent discipline: it shows the structure that supports strategic choice without reducing the market to simplified rankings. For the complete quantitative breakdown across each segmentation axis, the published study provides the full detail necessary for internal modeling and investment justification.
Competitive Landscape: Five Players Shaping the Market
No market analysis is complete without a credible view of the firms setting the pace. In hemoperfusion, the competitive landscape is defined by a mix of specialized innovators, established healthcare companies, and firms with deep polymer and blood-contact material expertise. The study focuses on five companies whose strategic positioning has meaningful implications for the broader market:
Disposable Hemoerfusion Cartridge Market
Spectral Medical Inc.
Headquartered in Toronto, Canada, Spectral Medical is focused on Toraymyxin™, a therapeutic hemoperfusion device designed for endotoxin removal in endotoxic septic shock. Its clinical emphasis reflects a broader industry movement toward targeted sorbent therapies in critical care. Our analysis examines how this focus influences clinical adoption, indication positioning, and the regulatory context surrounding high-acuity therapeutic use.
Jafron Biomedical Co., Ltd.
Based in Zhuhai, Guangdong, China, Jafron Biomedical develops the HA series of disposable hemoperfusion cartridges for blood purification in renal, liver, and intoxication treatments. The company’s disposable cartridge model illustrates an important commercial dynamic: modularity, ease of use, and cost-conscious procurement can be decisive in emerging adoption environments. The report places this strategy within the larger context of regional demand and affordability-driven purchasing.
Baxter International Inc.
Deerfield, Illinois-based Baxter is engaged in integrated extracorporeal blood purification and hemoperfusion systems as part of its renal care portfolio. Its presence underscores the role of broader portfolio integration in competitive positioning. When hemoperfusion fits into a larger platform strategy, the commercial narrative often shifts from single-product performance to system-level clinical value, service capability, and hospital workflow compatibility. This study examines that integration angle in depth.
Asahi Kasei Corporation
Tokyo-based Asahi Kasei brings a strong orientation toward resin-based hemoperfusion technologies and polymer chemistry for blood purification applications. For a market where adsorbent material performance directly affects product efficacy and competitive differentiation, this expertise is strategically significant. Our analysis addresses how material science leadership translates into product positioning and long-term defensibility in a technology-driven category.
CytoSorbents Corporation
CytoSorbents, based in Monmouth Junction, New Jersey, focuses on CytoSorb® hemoadsorption cartridges for cytokine and toxin removal in critical care. Its position highlights the growing attention to immunomodulation and toxin clearance in acute care settings. The report evaluates this positioning as part of the broader competitive conversation around which clinical benefits are most credible, most repeatable, and most commercially actionable.
Together, these companies represent a cross-section of strategic approaches: indication-specific therapeutics, disposable platform expansion, portfolio integration, material science leadership, and critical care-focused adsorption. The report goes beyond company-level description to examine how these strategies interact, where they compete directly, and where each is more likely to shape downstream purchasing behavior.
Recent Developments and Regulatory Dynamics
Market intelligence must be current to be credible. One notable recent event is Spectral Medical’s May 2026 Premarket Approval submission to the U.S. FDA for the Toraymyxin™ hemoperfusion device to treat endotoxic septic shock. From a strategic standpoint, PMA activity in this category is not a narrow regulatory milestone; it signals momentum in high-acuity indications and draws attention to the broader intersection of clinical evidence, regulatory clearance, and commercialization timing.
At the same time, the regulatory environment continues to shape how products move through the pipeline. Sorbent hemoperfusion systems are classified as Class II medical devices under 21 CFR 876.5870, with PMA or PDP requirements for hepatic coma and metabolic disturbance indications. That regulatory architecture influences not only product approval timing but also evidence generation strategy, label positioning, and the resourcing needed to compete in more tightly regulated indications. Companies that underestimate those requirements can misjudge both time-to-market and commercial scope.
Our study incorporates these regulatory dynamics so that market analysis remains grounded in real pathway constraints rather than abstract adoption curves. This is especially important for firms evaluating entry into indications where clearance requirements and clinical expectations are closely linked.
What This Means for Enterprise Strategy in 2026
The central question for leadership teams is how to translate market momentum into durable advantage. Based on the direction of this research, several strategic priorities stand out:
- Clarify the indication battleground. The application mix in this category is not uniform, and commercial success will depend on where a company chooses to focus clinical evidence, sales engagement, and service support. Broad claims rarely outperform focused, defensible positioning.
- Align product design with adoption economics. Whether the opportunity lies in disposable cartridges, integrated systems, or specialized therapeutic devices, the purchasing environment is shaped by procurement cycles, facilities’ workflow preferences, and cost-conscious evaluation. Design choices and commercial packaging should reflect that reality.
- Treat regulatory strategy as competitive strategy. Because indications such as hepatic coma and metabolic disturbance carry specific regulatory requirements, the approval pathway is not merely compliance work. It is a strategic determinant of how quickly a product can scale and where it can credibly compete.
- Plan around concentration and competition without overgeneralizing. The market is not a monolith, and competitive intensity varies by segment and geography. Understanding where concentration is high and where the field remains more open helps companies choose whether they should pursue differentiation, scale, partnership, or selective entry.
- Use the forecast as a scenario tool, not a promise. The 2026–2032 outlook provides a framework for thinking about trajectory, but its real value lies in supporting sensitivity analysis. Good strategy accounts for multiple demand paths, not a single assumed future.
Why the Full Study Is Designed for Action, Not Just Awareness
This preview has outlined the architecture of the analysis, the market momentum behind it, and the competitive and regulatory forces shaping 2026 decision-making. The goal has been to demonstrate depth without giving away the exact data points and detailed breakdowns that your internal teams will need to act with confidence. That is intentional.
Hemoperfusion Market
In practice, the most valuable insights are often the ones that require full segmentation detail, structured company evaluation, and cross-indication interpretation. Those are the materials that support board discussion, R&D prioritization, partnership evaluation, and commercial planning in a disciplined way. The executive preview can show you the logic of the market; the complete study gives you the numbers and the structured view needed to turn that logic into a real plan.
For organizations preparing for the rest of 2026 and beyond, the strategic question is no longer whether hemoperfusion is expanding, but where to position, how to move, and what evidence and compliance commitments will shape the outcome. PW Consulting’s Hemoperfusion Market research is built to help leaders answer those questions with precision.
Begin With the Full Intelligence Package
The complete market study provides the detailed segmentation architecture, competitive mapping, regulatory interpretation, and scenario inputs needed to support concrete 2026 decisions. If your organization is evaluating product strategy, market entry, partnership options, or commercial prioritization in hemoperfusion, the full report is the appropriate foundation for that work. This preview is intended to show that the analysis is grounded, structured, and ready for executive use, while leaving the most actionable detail available in the published intelligence.
For detailed analysis of this topic, please visit the official page: Hemoperfusion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


