



PW Consulting: Magnesium Carbonate Market Hits USD 307.71 Million in 2025, Poised for 4.7% CAGR Growth Through 2032

Strategic Intelligence in the Magnesium Carbonate Market: Navigating Growth Through 2032
Executive Overview
The global magnesium carbonate market stands at a pivotal juncture. As of 2025, the sector has demonstrated steady resilience, recovering from minor fluctuations observed in the early 2020s to establish a robust revenue baseline. For enterprise leaders and strategic planners, understanding the trajectory of this essential industrial mineral is no longer optional; it is a critical component of supply chain security, product development, and competitive positioning.
This article serves as a strategic precursor to the comprehensive Magnesium Carbonate Market Research Report published by PW Consulting. Our analysis covers the historical performance from 2020 through 2025 and projects market behavior through the forecast period ending in 2032. The objective is to equip stakeholders with the macroscopic perspective needed to allocate capital efficiently and anticipate regulatory shifts. However, the granular data required for precise operational modeling is reserved for the full intelligence subscription.
Magnesium Carbonate Market
Market Trajectory and Growth Dynamics
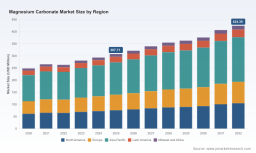
The market has exhibited a consistent upward trend over the past half-decade. Revenue valuations have progressed from approximately 248.5 million USD in 2020 to an estimated 307.71 million USD in 2025. This growth reflects the material's entrenched position in pharmaceuticals, personal care, and industrial manufacturing. Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion, albeit at a measured pace typical of mature commodity markets.
Key macroeconomic indicators derived from our modeling include a projected valuation of 321.45 million USD in 2026, escalating to 424.39 million USD by 2032. This progression implies a Compound Annual Growth Rate (CAGR) of 4.7 percent over the forecast horizon.
- Historical Stability: The market navigated post-pandemic supply chain adjustments between 2020 and 2023, stabilizing at 281.02 million USD by 2023.
- Forecast Momentum: Growth is expected to accelerate slightly in the late forecast period, with significant valuation jumps observed in the 2030 to 2032 window.
- Revenue Scale: All valuations are denominated in USD Millions, providing a standardized metric for cross-regional comparison.
While these headline figures provide a top-down view of market health, they do not reveal the underlying drivers of regional disparity or application-specific demand spikes. Understanding where the growth originates requires a deeper dive into segmentation that only the full report provides.
Segmentation Insights: Type and Application
Magnesium carbonate is not a monolithic commodity. Its utility varies significantly based on physical properties, specifically the distinction between light and heavy grades. Light magnesium carbonate, known for its high porosity and oil absorption capabilities, typically commands a different market dynamic compared to heavy magnesium carbonate, which is often preferred for specific industrial densities and pharmaceutical fillers.
Our analysis indicates that both types contribute substantially to the overall revenue pool. Light magnesium carbonate maintains a significant share of the global revenue, driven by its versatility in personal care and specialty chemical applications. Heavy magnesium carbonate complements this by serving specific industrial and technical requirements. The interplay between these two types dictates pricing strategies and inventory planning for manufacturers.
On the demand side, the application landscape is diverse. The pharmaceutical sector remains a cornerstone consumer, utilizing the material for antacids, laxatives, and tablet excipients. Simultaneously, the rubber and plastic industry leverages magnesium carbonate as a functional filler to enhance durability and processing characteristics. Personal care and cosmetics represent a high-value segment where purity standards are stringent, while the remaining broader industrial applications provide a stable baseline demand.
Calcium Carbonate Market
Note: Precise revenue splits for each type and application segment are proprietary data points within our full database. Stakeholders requiring specific volume or value allocations for these segments to build financial models are encouraged to access the complete segmentation tables in the final report.
Regional Landscape and Trade Flows
Geographically, the market is distributed across five key regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region typically exhibits the highest aggregate volume due to the concentration of manufacturing capacity and raw material availability. North America and Europe maintain mature markets with high demand for high-purity pharmaceutical and food-grade variants.
Trade dynamics play a crucial role in shaping regional supply. For instance, natural magnesium carbonate imports into Japan from China have shown significant valuation in recent trade data, highlighting the interdependence of Asian supply chains. Meanwhile, regulatory frameworks in the United States continue to influence market entry costs and classification standards.
- North America: A mature market with strong regulatory oversight regarding chemical safety and purity.
- Europe: Focuses on high-value specialty grades, with Germany serving as a hub for production and trading.
- Asia Pacific: Dominates in terms of volume and raw material processing, particularly involving magnesite derived from natural sources.
- Rest of World: Emerging demand centers in Latin America and Africa offer niche opportunities for industrial expansion.
Detailed regional revenue contributions and growth rates are critical for determining market entry strategies. Our full report breaks down the specific valuation and forecast for each region, allowing clients to assess local competitiveness without relying on industry averages.
Competitive Landscape and Key Players
The magnesium carbonate market is characterized by a moderately fragmented structure with a concentration of expertise among specialized manufacturers. The top three players hold a combined market share of approximately 23.5 percent, while the top five entities control around 28.0 percent of the revenue. This suggests that while large players exist, there is significant room for specialized niche providers and traders.
Several key companies define the competitive edge through product purity, capacity expansion, and supply chain integration.
Leading Manufacturers and Traders
- Dr. Paul Lohmann GmbH & Co. KGaA (Germany): A premier producer offering high-purity light, heavy, medium heavy, and specialty grades. Their focus spans pharmaceutical, food, and industrial applications, setting a benchmark for quality consistency.
- Kyowa Chemical Industry Co., Ltd. (Japan): Known for pharmaceutical-grade and high-purity light and heavy magnesium carbonate. Their recent product catalog releases emphasize enhanced purity focus for food additives and personal care.
- Konoshima Chemical Co., Ltd. (Japan): Produces multiple grades including plate-shaped variants, catering to specific chemical and industrial use cases that require unique morphological properties.
- Lehmann & Voss & Co. KG (Germany): A significant supplier and trader. Recent updates include enhanced technical selling capabilities and supply chain optimizations for mineral fillers, positioning them as a key logistics and sourcing partner.
- Grecian Magnesite S.A. (Greece): A major producer leveraging natural magnesite. Their recent commissioning of a second X-ray-based mineral processing line at Yerakini Mines signals a strong commitment to capacity expansion and processing efficiency.
- Yingkou Magnesite Chemical (China): A large-scale producer utilizing natural magnesite, playing a critical role in the global supply volume, particularly for industrial grades.
- Others: Additional players such as Naikai Salt Industries, SCORA S.A.S., and Buschle & Lepper S.A. contribute to the ecosystem with specific focuses on food, nutraceutical, bakery, and refractory applications.
The competitive dynamic is not just about production volume. It is about the ability to navigate regulatory changes and supply chain disruptions. The recent developments observed in late 2025, such as portfolio updates and processing line commissions, indicate that incumbents are actively fortifying their positions against potential market volatility.
Regulatory and Industry Context
External factors significantly influence market fluidity. Regulatory status varies by jurisdiction and application, affecting everything from import duties to product certification.
In the United States, magnesium carbonate is listed under the Harmonized Tariff Schedule Chapter 25, with no specific duties applied in the current framework, facilitating relatively smooth trade flows for imported grades. However, compliance remains key. The material was delisted from U.S. color additive certification requirements in recent regulatory updates, simplifying its use in certain cosmetic applications. Conversely, it remains approved in Codex Alimentarius standards as INS 504(i), ensuring its continued legitimacy in global food supply chains.
Raw material economics also factor into strategic planning. Conservation policies, such as depletion allowances for magnesite and magnesium carbonate, can impact cost structures for domestic producers in regions like the U.S. Understanding these fiscal nuances is essential for accurate margin forecasting.
Our report integrates these regulatory and raw material factors into a holistic market view, analyzing how policy shifts in 2026 and beyond might alter cost bases or demand elasticity.
Strategic Value for 2026 Decision-Making
For C-suite executives, procurement officers, and strategy analysts, the Magnesium Carbonate Market Report offers more than just numbers. It provides a framework for action. The period from 2026 to 2032 is expected to see evolving demands in high-purity sectors alongside steady industrial consumption.
Why this intelligence matters now:
- Supply Chain Resilience: With capacity expansions occurring in Europe and production scaling in Asia, knowing where supply is tightening or easing helps mitigate procurement risk.
- Product Portfolio Alignment: As regulations shift, such as changes in color additive certifications or food safety standards, companies must align their product offerings with compliant grades. Our analysis highlights which grades are gaining regulatory favor.
- Investment Timing: The forecast suggests a notable acceleration in market valuation toward the end of the decade. Identifying the catalysts for this growth allows investors to time market entry or capacity expansion correctly.
- Competitive Benchmarking: Knowing the market concentration and the strategic moves of key players like Grecian Magnesite or Kyowa Chemical allows firms to position themselves defensively or offensively.
The data provided in the summary above serves as a validation of market health. However, the specific drivers—such as exact growth percentages per application segment, detailed regional supply deficits, or proprietary pricing models—are contained within the full intelligence suite. Relying on aggregate data alone can lead to suboptimal strategic decisions in a market where purity premiums and regional logistics costs vary widely.
Conclusion
The magnesium carbonate market is poised for steady growth, underpinned by essential demand in pharmaceuticals, industrial manufacturing, and personal care. With a projected CAGR of 4.7 percent and a total market value expected to exceed 424 million USD by 2032, the opportunity for strategic expansion is clear.
However, success in this market requires more than a view of the top-line numbers. It demands an understanding of the interplay between light and heavy grades, the nuances of regional trade flows, and the strategic maneuvers of key competitors. The PW Consulting Magnesium Carbonate Market Research Report is designed to provide this depth.
We invite stakeholders to utilize this overview as a foundation for their strategic planning. For the detailed segmentation data, comprehensive competitor profiles, and actionable forecasts required to navigate 2026 and beyond, we recommend accessing the full report. This ensures that your decisions are based on complete intelligence rather than partial visibility.
PW Consulting remains committed to delivering clarity in complex markets. For further inquiries or to acquire the full dataset, please contact our research team.
For detailed analysis of this topic, please visit the official page: Magnesium Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


