



PW Consulting: Ball Mill Mining Market Hits $4.35B in 2025, Projected to Reach $6.86B by 2032

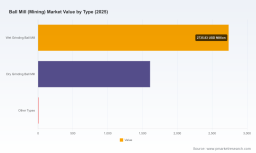
Ball Mill (Mining) Market 2026: Navigating the Efficiency Imperative in a $4.6 Billion Industry
The global mining equipment landscape is undergoing a structural transformation, and at the heart of this shift lies the ball mill. As the workhorse of mineral processing, the ball mill remains indispensable for reducing ore to fine particles suitable for downstream extraction. Yet, the operational context surrounding this machinery is changing rapidly. Rising energy costs, stricter environmental regulations, and the relentless pursuit of throughput optimization are reshaping procurement strategies, capex planning, and long-term fleet management for mining enterprises worldwide.
PW Consulting’s latest market research on the Ball Mill (Mining) Market is designed to cut through this complexity. Built on a rigorous historical dataset spanning 2020 through 2025 and extended with a comprehensive forecast period through 2032, this report provides the strategic intelligence required to make high-stakes decisions in 2026 and beyond. The market has demonstrated consistent momentum, with overall industry revenue climbing from 3171.89 million USD in 2020 to an estimated 4353.5 million USD by the base year of 2025. The forward trajectory points to continued expansion, positioning the sector at a projected 4606.46 million USD in 2026, with growth compounding toward 6859.45 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 6.9 percent, reflecting sustained investment in mining infrastructure, the commissioning of new processing plants, and the modernization of aging grinding circuits.
For executives, engineers, and procurement leaders, these aggregate figures serve as a critical baseline. They signal that demand for grinding equipment is not merely cyclical but structurally supported by the global need for processed minerals across industrial, technological, and energy-transition applications. However, aggregate size alone does not dictate strategy. The true value of this research lies in its ability to translate macro trends into actionable frameworks, helping organizations allocate capital, evaluate vendor partnerships, and anticipate regulatory or supply-chain disruptions before they impact operations.
The Strategic Value of Granular Intelligence for 2026 Decision-Making
2026 represents a pivotal planning year for mining organizations. Capital allocation decisions made now will determine operational competitiveness over the next several years, particularly as companies balance throughput targets with escalating energy costs and compliance requirements. The PW Consulting report is structured to support these decisions with field-ready analysis rather than abstract commentary. Readers will find detailed breakdowns of equipment types, end-use applications, and regional deployment patterns, all contextualized within the broader market trajectory.
The research dissects the market across multiple dimensions that matter directly to procurement and engineering teams. Equipment segmentation covers wet grinding ball mills, dry grinding ball mills, and other specialized configurations, allowing readers to understand where demand is concentrating and how technological preferences are evolving. Application-level analysis examines use cases across metal mining, mineral mining, and other processing verticals, highlighting where throughput requirements, liberation size targets, and circuit configurations differ. Geographic coverage spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing a global view of where development activity, mine expansions, and equipment replacement cycles are most active.
Importantly, the report does not simply present data points in isolation. Each segment is examined through the lens of operational relevance, helping decision-makers understand why certain configurations are favored in specific contexts, how application requirements drive specification choices, and which geographic markets are experiencing the most intense competition for supply and installation capacity. This approach ensures that readers can map market intelligence directly onto their own asset planning, vendor negotiations, and risk management frameworks.
Competitive Landscape: Established Leaders and Emerging Pressures
The ball mill market is characterized by a moderately concentrated competitive environment, with the top three players accounting for approximately 33.5 percent of market share and the top five collectively capturing around 48.2 percent. This structure creates a landscape where established multinational suppliers compete on technology, reliability, and global service networks, while regional and specialized manufacturers carve out positions through cost efficiency, customization, and responsiveness to local project requirements. Understanding this dynamic is essential for organizations evaluating supplier partnerships, negotiating procurement contracts, or assessing the availability of spare parts and technical support over the lifespan of a grinding circuit.
Several core companies define the current competitive baseline. Metso, headquartered in Finland, has strengthened its position through its Premier and Select horizontal ball mill offerings, emphasizing energy-efficient grinding solutions that can deliver up to 30 percent energy savings compared with conventional ball mills. This focus on efficiency aligns with broader industry mandates and appeals to operators seeking to reduce operating expenditures while maintaining throughput. FLSmidth, based in Denmark, complements this landscape with high-throughput ball mills and its Tower Mill technology for secondary and fine grinding. The company’s push to replace conventional ball mills in iron ore beneficiation, with documented energy reductions in the 25 to 50 percent range, underscores a strategic emphasis on alternative grinding architectures that can outperform traditional designs in specific applications.
KHD Humboldt Wedag, operating from Germany, continues to serve the market with traditional ball mill designs and upgrade packages for existing grinding circuits, targeting stable and efficient performance in mining environments. Sepro Mineral Systems, from Canada, addresses small and medium capacity operations with tyre-drive rotary grinding mills suitable for ball, rod, and pebble charges, offering a practical solution for operators where flexibility and manageable scale are priorities. On the capacity and throughput side, CITIC Limited in China supplies large-capacity ball mills for mining and mineral processing, with an emphasis on high throughput and reliability. Hongxing Machinery, also based in China, provides standard and energy-saving ball mills for ore re-crushing in mineral processing, reflecting the continued importance of cost-competitive equipment in high-volume segments.
Recent market developments illustrate how competitive and project dynamics are evolving in real time. In September 2025, Deccan Gold Mines Limited launched the Altyn Tor Gold Project in Kyrgyzstan, incorporating a ball mill as part of its gold extraction processing infrastructure. This type of project execution signals sustained demand for grinding equipment in gold and base metal operations, particularly where new facilities are being commissioned or existing circuits are being expanded. In July 2025, Gold Rock Projects introduced a new ball mill designed specifically for gold producers, equipped with digital monitoring sensors for real-time performance tracking and automated load control. This development highlights the growing integration of digital instrumentation and automation into grinding equipment, enabling operators to optimize mill performance, reduce manual intervention, and respond more quickly to changes in feed characteristics or circuit conditions.
Competitive pressure is also coming from adjacent technologies. Metso reported record sales of stirred mills in 2025, with more than 20 Vertimill units sold, demonstrating sustained demand for energy-efficient alternatives to conventional ball mills. This trend does not diminish the role of the ball mill, but it does reinforce the need for operators to evaluate the full spectrum of grinding options when designing or upgrading circuits. Decision-makers must weigh capital cost, energy consumption, maintenance requirements, and product size distribution against the specific demands of their ore bodies and processing goals.
Market Dynamics: Efficiency, Regulation, and Supply Chain Volatility
The operational environment for ball mill procurement and deployment is shaped by a convergence of technical, regulatory, and macroeconomic forces. Energy efficiency mandates and sustainability initiatives across the mining sector are accelerating the adoption of energy-efficient grinding systems and automation. Organizations are increasingly scrutinizing the total cost of ownership of grinding equipment, recognizing that energy consumption during operation can dominate lifecycle costs. The projected 25 to 50 percent energy reduction achievable when replacing conventional ball mills with more efficient alternatives has become a compelling value proposition, particularly for operators facing rising power prices or operating in regions with strict carbon and emissions expectations.
Regulatory frameworks are adding further complexity. OSHA noise exposure limits and the EU Occupational Safety and Health Framework Directive establish strict permissible exposure levels for ball mill operations, conditions that are frequently exceeded without mitigation measures. These requirements are driving interest in engineering controls, enclosure improvements, and operational protocols that reduce noise and vibration at the source. At the same time, compliance pressures are encouraging adoption of ISO 14001 environmental management systems, as mining companies seek to standardize their approach to environmental performance, hazard control, and continuous improvement. Equipment suppliers that can support these compliance objectives through design features, documentation, and service integration are likely to gain preference in competitive tenders.
Supply chain volatility presents another critical consideration. Steel grinding media raw material costs account for 55 to 70 percent of manufacturing costs for forged balls used in ball mills, and these costs have experienced volatility of over 25 percent year-on-year in recent years. Such fluctuations directly affect consumable expenses, which are a significant component of grinding circuit operating costs. Operators must factor media cost volatility into their budgeting, negotiate procurement agreements with appropriate flexibility, and evaluate whether certain mill designs or operating strategies can reduce media consumption or extend media life. The interplay between equipment selection, operating parameters, and consumable costs is a central theme in the report’s analysis, helping readers build more resilient cost models.
Forged Steel Grinding Balls Market
Why This Research Matters Now
The ball mill market is not defined solely by equipment sales; it is shaped by the intersection of ore characteristics, processing objectives, energy economics, regulatory compliance, and competitive technology alternatives. The 6.9 percent CAGR reflected in the forecast period signals that demand will continue to grow, but growth alone does not guarantee optimal outcomes for any individual organization. The strategic question for 2026 is not whether the market is expanding, but how to position within it with the right equipment specifications, supplier relationships, and operational strategies.
Ball Mill (Mining) Market
This research provides the analytical foundation to answer that question. It combines historical validation with forward-looking projections, embeds competitive and project-level developments in context, and addresses the operational dynamics that influence procurement and performance. By connecting market size trends with segmentation insights, regulatory drivers, and supply-chain realities, the report equips readers to make decisions with greater confidence and precision.
For organizations planning capital expenditures, evaluating grinding circuit upgrades, or preparing for new project commissions, the full report offers the depth required to move beyond general market awareness into targeted strategy. Explore the complete analysis, including detailed segmentation, competitive profiles, and operational dynamics, by accessing the full market research at the source page.
For detailed analysis of this topic, please visit the official page: Ball Mill (Mining) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


