



PW Consulting: Photocatalyst Market Hits $2.2B in 2025, Forecasts 9.6% CAGR to $4.18B by 2032

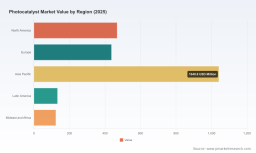
The Photocatalyst Market in 2026: A Strategic Compass for Industrial Transition
The global photocatalyst market stands at a pivotal inflection point. After a decade of incremental adoption driven by niche environmental applications, the sector is now accelerating under the combined weight of regulatory pressure, urban air-quality mandates, and next-generation construction standards. Our latest market research delivers a comprehensive, forward-looking assessment of this landscape, designed specifically to equip corporate strategists, R&D directors, and investment committees with the operational intelligence needed to navigate decision-making in 2026 and beyond.
By consolidating five years of historical performance with a seven-year forecast horizon, the study maps how demand is structurally shifting across material classes, end-use sectors, and regional ecosystems. More importantly, it translates macro trajectories into actionable strategic frameworks—covering supply-chain resilience, regulatory compliance pathways, competitive positioning, and innovation roadmaps. This is not a static sizing exercise. It is a decision-support architecture for enterprises that must anticipate where capital, technology, and policy will converge over the next cycle.
A Market Accelerating Under Structural Tailwinds
Photocatalysis has evolved from a laboratory-scale environmental concept into a commercially embedded technology set. The sector’s valuation trajectory over the past half-decade reflects a clear acceleration, with revenue compounding steadily from the early 2020s through the current base year. That momentum is projected to intensify as the forecast window unfolds, supported by a compound annual growth rate that places the industry among the faster-growing segments within advanced materials and environmental technologies.
The underlying drivers are multifaceted and mutually reinforcing. Stricter indoor-air VOC and NOx emission standards worldwide are pushing facility operators, architects, and municipal authorities toward photocatalytic air-purification and self-cleaning materials. Simultaneously, the European Green Deal’s circular-economy provisions are channeling subsidies into sustainable construction materials that incorporate photocatalytic glazing and surface treatments. These policy signals are not isolated; they are compounding with corporate sustainability commitments, urbanization pressures, and a growing recognition that passive environmental remediation can deliver measurable operational savings over asset lifecycles.
Precious Metal Catalyst Market
Yet growth is not uniform, and the strategic implications vary sharply by material type, application architecture, and geographic footprint. This is precisely where high-level headlines fall short and granular, structured analysis becomes essential. Our research dissects the market’s composition without exposing the margin for guesswork, allowing leadership teams to evaluate where their portfolios align with the steepest growth vectors and where exposure to slower-moving segments requires defensive repositioning.
Photocatalyst Market
From Macro Trajectories to Operational Strategy
The study is structured to bridge the gap between top-line market direction and on-the-ground execution. Rather than presenting a single aggregate figure, the report builds a layered view of demand dynamics, pricing behavior, and technology substitution patterns across the forecast horizon. It examines how input-cost volatility—particularly within high-purity titanium dioxide feedstock supply chains, where production remains concentrated among a limited number of global suppliers—shapes margin structures and procurement strategies for downstream formulators and coating manufacturers.
Supply-chain visibility is a recurring theme. The analysis maps the sensitivity of photocatalytic product economics to upstream raw-material availability, logistics bottlenecks, and regional production capacity. It also evaluates how vertical integration moves by key feedstock and intermediate suppliers influence stability of supply and cost predictability for industrial buyers. For procurement and operations teams, these insights translate into more resilient sourcing frameworks and better-informed make-versus-buy decisions for specialty formulations.
On the demand side, the report traces how application adoption curves diverge across sectors. Air purification, water purification, and self-cleaning surfaces each follow distinct commercialization rhythms, shaped by local regulatory timelines, public-sector procurement cycles, and building-material integration requirements. Anti-fogging and anti-soiling coatings, alongside other emerging use cases, occupy a different risk-reward profile, typically requiring longer validation periods but offering higher differentiation potential once performance thresholds are met. The study outlines the commercial milestones, testing protocols, and certification pathways that govern market entry, helping R&D and product management teams sequence development pipelines against realistic adoption windows.
The forecast framework extends through the end of the decade and into the early 2030s, enabling scenario planning under varying assumptions for regulation, feedstock costs, and regional investment intensity. By modeling how different policy or cost environments could alter demand pacing, the report equips strategy teams to stress-test capital allocation, capacity expansion, and partnership choices well ahead of market inflection points.
Competitive Architecture and the Players Shaping the Next Cycle
The competitive landscape in photocatalysis is defined by a blend of material science specialists, large chemical conglomerates, and application-focused innovators. Concentration metrics indicate that the top three and top five participants command a meaningful share of commercial activity, underscoring the importance of understanding not just who leads today, but how incumbency advantages, differentiation strategies, and partnership ecosystems are evolving.
Kronos Worldwide, Inc. remains a specialist in photocatalytic titanium dioxide grades tailored for self-cleaning surfaces and building materials, positioning its portfolio around architectural and infrastructure demand. Cristal Global, operating through its CristalACTiV platform, has advanced ultrafine titanium dioxide formulations for photocatalytic coatings and NOx abatement applications, with recent product development centered on air-quality improvement use cases. TOTO Ltd. supplies photocatalytic coatings spanning self-cleaning surfaces as well as air and water purification, with a strong footprint in construction and healthcare environments. Ishihara Sangyo Kaisha, Ltd. contributes high-purity titanium dioxide photocatalysts aimed at environmental and industrial applications, while Nippon Soda Co., Ltd. develops and supplies photocatalytic formulations and binders that enable downstream integration.
On the broader materials and environmental catalysis side, BASF SE provides photocatalytic materials for air purification and environmental catalysis, leveraging its scale and cross-sector distribution capabilities. In the innovation frontier, Puralytics LLC has developed PuraMesh photocatalyst technology for advanced oxidation and water/air purification, while Nanoptek Corp. supplies visible-light titania photocatalysts and pigments that address performance limitations in lower-light conditions. Daicel Miraizu continues as a manufacturer of photocatalytic materials and coatings, and the International Photocatalyst Standards Test Centre in the UK serves as an independent testing and certification provider, underpinning market credibility through ISO-aligned evaluation protocols.
Recent corporate activity reinforces the strategic direction of the sector. In early 2026, Cristal Global advanced its CristalACTiV TiO2 products for NOx abatement applications targeting air-quality improvement, signaling continued emphasis on pollution-mitigation endpoints. Around the same period, Tronox highlighted photocatalytic applications within its specialty TiO2 products in its sustainability reporting, while also advancing vertical integration in its TiCl4 supply chain to stabilize TiO2 production. These moves illustrate a broader pattern: leading participants are aligning product development with regulatory tailwinds, while simultaneously working to insulate production from feedstock volatility.
The report examines how these competitive dynamics translate into market access barriers, partnership opportunities, and differentiation strategies. It evaluates where scale, where formulation expertise, and where application validation create durable advantages, and where new entrants or collaborative models may compress incumbency moats over the forecast period.
Why 2026 Is a Decision Window, Not Just a Forecast Year
For corporate decision-makers, 2026 functions as a strategic checkpoint. The convergence of tighter emission standards, subsidy mechanisms for sustainable construction, and evolving testing and certification expectations is reshaping the criteria by which photocatalytic products win commercial adoption. Enterprises that treat this year as a passive continuation of prior trends risk misaligning product roadmaps, sourcing strategies, and go-to-market priorities with the market’s actual direction.
Notable structural forces now shaping that direction include the ongoing influence of environmental compliance on specialty TiO2 product portfolios, with sustainability reporting and regulatory expectations encouraging broader adoption of photocatalytic NOx abatement technologies. In parallel, European frameworks are directing financial support toward circular-economy-aligned building materials, strengthening the economic case for photocatalytic glazing and surface solutions. At the same time, global indoor-air quality standards are tightening, expanding the addressable base for photocatalytic air-purification and self-cleaning materials. Regulatory approvals from bodies such as the European Chemicals Agency have also enabled the commercial launch of new photocatalytic products for air purification, widening the field for innovation-led entrants while raising the bar for compliance-ready product design.
These conditions create a market environment where strategic timing matters as much as technical capability. Companies that understand the interplay between feedstock cost dynamics, regional regulatory pacing, and application-specific certification requirements are better positioned to prioritize investments, negotiate supply agreements, and structure partnerships. The study is built to surface those interdependencies clearly, giving leadership teams a shared analytical baseline for cross-functional planning.
What the Report Delivers for Strategy, R&D, and Commercial Teams
The research is organized to support a wide range of internal use cases. For strategy and corporate development teams, it provides a market-level orientation that ties growth trajectories to competitive positioning, enabling more informed evaluation of adjacency opportunities, M&A targets, and geographic expansion priorities. For R&D and product teams, it maps technology substitution patterns, formulation considerations, and performance-testing expectations, helping calibrate development timelines against market readiness. For commercial and sales leadership, it outlines application-specific demand drivers, procurement contexts, and the regulatory and certification factors that influence buying decisions in construction, environmental services, and industrial settings.
The report also includes practical coverage of market-concentration dynamics, supply-chain sensitivity, and recent corporate developments that shape near-term competitive behavior. It integrates sector-level signals around regulation, raw-material availability, and sustainability reporting trends, translating them into implications for sourcing, pricing, and product positioning. By combining historical context, forecast direction, and qualitative intelligence on the companies and institutions actively shaping the market, the study offers a consolidated reference point for decision-making across functions.
Importantly, the analysis is designed to remain useful beyond the immediate planning cycle. Because photocatalytic adoption is influenced by long-duration assets such as buildings, infrastructure, and industrial facilities, today’s product and sourcing choices have multi-year consequences. The forecast horizon and scenario frameworks included in the research help organizations connect near-term actions to longer-term outcomes, reducing the risk of short-horizon optimization that undermines competitive positioning later in the decade.
Accessing the Full Intelligence Suite
Our Photocatalyst Market study is intended for teams that need more than directional commentary. It provides a structured, data-informed foundation for evaluating where the market is heading, which actors are shaping the pace of change, and how enterprise strategy should respond in 2026 and through the coming forecast years. The complete report includes detailed segmentation analyses, competitive profiles, regulatory and supply-chain assessments, and forecast scenarios that together form a comprehensive decision-support toolkit.
To explore the full segmentation detail, company-level positioning, regional demand architecture, and scenario-based forecasts, request access to the complete market research. The full intelligence suite is available through our official research portal, where strategy, procurement, and innovation teams can retrieve the complete dataset and analytical modules needed to ground 2026 planning in a rigorous, forward-looking view of the photocatalyst market.
For detailed analysis of this topic, please visit the official page: Photocatalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


