



PW Consulting: Cockpit and Flight Data Recorder Market Hits $170M in 2025, 5.8% CAGR to $257M by 2032

Strategic Imperatives in the Cockpit Voice and Flight Data Recorder Market: Navigating Growth and Regulatory Shifts Through 2032
The aviation safety ecosystem stands at a pivotal juncture. As aircraft design philosophies evolve and regulatory bodies tighten mandates around data retention and crashworthiness, the Cockpit Voice and Flight Data Recorder market is experiencing a structural realignment that will define procurement strategies, product development roadmaps, and competitive positioning for the next decade. Our latest market research offers a comprehensive, data-driven blueprint for executives, sourcing directors, and engineering leaders who must make capital allocation and compliance decisions in 2026 and beyond.
This publication arrives at a moment when the intersection of technological innovation and regulatory compliance is no longer a peripheral concern, but a central boardroom priority. The insights contained within are designed to transform uncertainty into actionable intelligence, enabling stakeholders to anticipate demand shifts, evaluate supplier capabilities, and align investment timing with the market’s most consequential inflection points.
Market Trajectory: A Decade of Calculated Expansion
Tracing the historical arc from 2020 through 2025 reveals a market that has consistently demonstrated resilience and steady upward momentum, even amid global supply chain disruptions and shifting fleet utilization patterns. The sector has progressed from a baseline valuation in the early 2020s to a substantially expanded footprint by 2025, reflecting sustained airframe deliveries, replacement cycles, and the gradual integration of next-generation recording architectures across both commercial and defense platforms.
Looking forward across our forecast period, the trajectory points toward continued growth, underpinned by heightened safety mandates, fleet modernization programs, and the ongoing proliferation of digital flight data streaming capabilities. The compound annual growth rate projected for this window signals a durable expansion narrative, one that will reward organizations capable of aligning their product portfolios and supply chain strategies with emerging compliance requirements. Critically, the projected valuation milestones across successive forecast years illustrate a market that is not merely expanding in nominal terms, but evolving in complexity, demanding more sophisticated integration, certification readiness, and lifecycle support capabilities from manufacturers and integrators alike.
For enterprise decision-makers, this growth profile carries strategic weight. It suggests that the market will accommodate new entrants and incumbent expansions alike, but that the distribution of opportunity will be uneven. Organizations that treat the recorder segment as a commoditized afterthought risk ceding ground to competitors who recognize it as a high-value, regulation-sensitive domain with significant barriers to entry and long-term revenue visibility.
Regulatory Catalysts Reshaping Demand Profiles
The single most potent force currently restructuring procurement pathways is the regulatory environment. Throughout 2024 and 2025, authorities across major aviation markets moved to codify extended recording durations and enhanced data accessibility standards. A landmark development in early 2026 saw the finalization of a rule mandating twenty-five-hour cockpit voice recorder retention for newly manufactured aircraft across multiple operational categories, with compliance timelines anchored to production dates in mid-2025. This ruling does not merely extend a specification; it fundamentally alters the engineering requirements for manufacturers designing for the commercial airliner, business jet, and commuter segments.
Complementary legislative actions, including provisions embedded in broader aviation reauthorization frameworks, have extended similar twenty-five-hour capability requirements to larger transport-category aircraft and established retrofit compliance horizons extending toward the end of the decade. These mandates create a dual-layer demand structure: an immediate pull from new production lines adapting to revised certification baselines, and a deferred but substantial pull from in-service fleets that must be upgraded or replaced to remain compliant. International standardization efforts have reinforced this trajectory, with global aviation bodies advancing proposals to harmonize flight recorder data download interfaces, reduce analysis friction, and improve cross-manufacturer interoperability. Such initiatives signal a longer-term shift toward data-centric safety architectures that will influence procurement criteria well beyond the current forecast horizon.
For organizations evaluating market entry, product line expansion, or supplier partnerships, the regulatory calendar is not a peripheral detail. It is a scheduling mechanism that dictates certification timelines, production slot allocation, retrofit campaign planning, and ultimately, revenue realization. The strategic implication is clear: companies that map their development cycles and capacity investments against these regulatory milestones will secure competitive advantage, while those that treat compliance as an after-the-fact engineering task will face costly redesigns and delayed market access.
Aerospace and Marine Data Recorders Market
Product Segmentation and Engineering Evolution
The market’s product architecture spans distinct recorder categories, each carrying different engineering demands, certification pathways, and end-user value propositions. Traditional flight data recording units continue to serve as the backbone of operational monitoring and accident investigation, while cockpit voice recording systems have undergone a generational leap in capacity and reliability. The emergence of combined voice and flight data recorder solutions reflects a broader industry preference for integrated, weight-optimized, and simplified installation architectures, particularly in platforms where space, power, and maintenance access are tightly constrained.
Engineering sophistication in this segment has accelerated markedly. Modern recorder families now emphasize extended recording durations, enhanced crashworthiness and fire resistance, faster data retrieval through advanced interface protocols, and optional onboard streaming or rapid-retrieval capabilities that reduce post-event analysis timelines. Ethernet-enabled download pathways, integrated rapid-retrieval information processing systems, and modular designs that accommodate multi-platform certification are increasingly becoming baseline expectations rather than premium differentiators. For integrators and airframe manufacturers, these features translate into reduced certification complexity, streamlined maintenance workflows, and improved alignment with fleet-wide data management strategies.
The implication for market participants is that product differentiation is shifting from standalone recorder specifications toward ecosystem compatibility. Suppliers that can demonstrate seamless integration with existing avionics suites, provide clear retrofit pathways, and offer lifecycle support aligned with extended operational use cases will capture disproportionate share in a market where total cost of ownership and compliance assurance weigh heavily in purchasing decisions.
Cockpit Voice and Flight Data Recorder Market
Competitive Architecture: Who Holds the Edge
The competitive landscape is defined by a concentrated group of established aerospace and defense technology firms that have invested heavily in recorder platforms, certification portfolios, and OEM relationships. Industry analysis indicates a market structure where a relatively small number of participants command a substantial share of revenue, reflecting the high technical barriers, lengthy certification cycles, and long-term supply agreements that characterize this domain. Such concentration rewards companies with proven track records in airworthiness certification, production scalability, and global aftermarket support.
Among the organizations shaping this competitive environment, several stand out for their product architectures and strategic positioning. Honeywell Aerospace has solidified its presence through combined recorder platforms engineered for commercial airliners and business jets, with certification coverage that spans multiple aircraft categories and recording durations aligned with the latest mandates. Curtiss-Wright Defense Solutions contributes through its recording technology divisions, including collaborative development of next-generation recorder series and proprietary systems designed for commercial aviation applications. Universal Avionics has advanced the segment through its fifth-generation recorder line, emphasizing combined unit configurations, Ethernet download options, and modular rapid-retrieval capabilities that align with modern fleet data management needs.
L3Harris Technologies maintains a strong footprint through its recorder and survival recorder families, including series designed for widely deployed airframes with supplemental type certificate coverage on platforms such as the Boeing 737NG and integrated rapid-retrieval systems. HENSOLDT brings European certification expertise and a portfolio spanning combined recorders, standalone flight data units, and voice recording models certified to recognized industry standards. Flight Data Systems has carved a position around lightweight combined recorder designs that meet stringent crashworthiness and fire-resistance requirements while offering optional rapid-retrieval integration. Safran extends its influence through helicopter and fixed-wing recorder solutions, reflecting the diversification of platform requirements across rotorcraft and general aviation segments. Acron Aviation has emerged as a notable player through its recorder series offering extended audio and flight data retention, alongside strategic recognition as an approved solution for major airframer programs and a platform for continuous online procurement of certified avionics components.
The strategic takeaway for procurement and planning teams is that supplier selection increasingly hinges on more than unit pricing. Certification breadth, retrofit readiness, production capacity, global support infrastructure, and alignment with forthcoming data interface standardization all factor into long-term value. Organizations that conduct structured supplier evaluations against these criteria will be better positioned to secure reliable supply, navigate certification dependencies, and capitalize on retrofit and replacement cycles.
Where 2026 Decision-Makers Must Focus
As enterprises calibrate their strategies for the current year and beyond, several priority areas demand focused attention. First, regulatory mapping must become a continuous function rather than a periodic compliance exercise. The staggered compliance dates across new production and retrofit mandates require organizations to sequence procurement, engineering, and fleet planning activities with precision. Second, product evaluation frameworks should incorporate data accessibility, interface compatibility, and aftermarket support as core criteria, reflecting the longer-term shift toward integrated safety data ecosystems.
Third, supply chain resilience warrants heightened scrutiny. The concentration of market share among a limited set of manufacturers underscores the importance of qualifying alternate sources where feasible, securing multi-year agreement structures, and stress-testing production capacity against anticipated demand surges driven by retrofit campaigns and fleet renewal programs. Fourth, forward-looking investment decisions should account for the possibility that standardization initiatives around data download interfaces and interoperability will create new value pools in software, analytics, and service delivery, extending the commercial relevance of recorder platforms beyond hardware sales.
Organizations that embed these considerations into their strategic planning will not only mitigate compliance risk but also unlock opportunities to influence specification development, secure preferred supplier status, and align product roadmaps with the market’s most consequential growth vectors.
What the Full Study Delivers
Our complete market research publication provides a granular, actionable foundation for the decisions outlined above. The report constructs a multi-year market size framework anchored to historical performance data and extended through a detailed forecast horizon, enabling precise scenario planning and investment timing analysis. It decomposes demand across major geographic markets and application segments, illuminating where growth concentration is forming and how regional aviation activity, fleet composition, and regulatory adoption patterns shape local opportunity profiles.
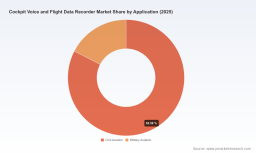
The study delivers deep segmentation analysis by recorder type, clarifying the relative commercial weight of flight data recorders, cockpit voice recorders, and combined systems, while mapping product architecture trends, certification requirements, and technological adoption curves across each category. Application-level examination distinguishes between civil aviation and military aviation demand drivers, including fleet renewal cycles, operational mandates, and platform-specific engineering requirements that influence procurement timing and specification preferences.
A dedicated competitive profiling section evaluates the strategic posture, product capabilities, certification footprints, and recent developments of the leading manufacturers, providing a structured basis for supplier benchmarking, partnership evaluation, and competitive positioning analysis. The report also integrates regulatory trackers, recent product launches, partnership announcements, and procurement developments, offering a continuously updated view of the forces that are actively reshaping purchasing requirements and market access conditions.
For executives seeking to validate capital allocation, guide engineering investment, or refine market entry strategies, the full study translates macro-level trends into specific, segment-level intelligence that can be operationalized across procurement, product management, and strategic planning functions. The most consequential details, including precise regional revenue distributions, application-level valuation breakdowns, and company-specific market share estimates, are reserved for the complete report to ensure that stakeholders receive unfiltered, decision-ready intelligence when they engage directly with the analysis.
The Strategic Case for Early Engagement
The Cockpit Voice and Flight Data Recorder market will not be defined solely by airframe production volumes or cyclical procurement patterns. It will be shaped by the interplay of regulatory mandates, engineering standardization, supplier concentration, and the growing expectation that safety recorders function as integral nodes within broader aviation data architectures. Organizations that act early to align their strategies with these forces will secure advantages in specification influence, supply assurance, and market positioning that will compound as the forecast period unfolds.
This research publication is designed to provide the evidentiary foundation and analytical structure necessary to make those decisions with confidence. By combining historical validation, forward-looking modeling, competitive mapping, and regulatory tracking into a single integrated framework, it equips decision-makers with the clarity required to navigate a market that rewards preparedness and penalizes ambiguity. The complete dataset, segment-level breakdowns, and detailed company assessments are available through the full report, offering the depth required to translate strategic intent into executed action.
For detailed analysis of this topic, please visit the official page: Cockpit Voice and Flight Data Recorder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


