



PW Consulting: Non-Destructive Testing Instruments Market to Reach $30.7B by 2032, 9.3% CAGR

Strategic Imperatives in the Non-Destructive Testing Instruments Market: Navigating Growth Through 2032
The global landscape for non-destructive testing instruments is undergoing a profound transformation, driven by escalating safety mandates, infrastructure aging, and the rapid integration of digital technologies. As industrial sectors worldwide prioritize asset integrity and operational reliability, the demand for advanced inspection solutions has accelerated beyond historical trajectories. Our latest comprehensive analysis, Non-Destructive Testing Instruments Market, provides a critical roadmap for stakeholders aiming to align their strategies with the compounding opportunities projected through 2032. This article outlines the strategic value of this research, synthesizing macroeconomic indicators, competitive dynamics, and emerging industry shifts to underscore why informed decision-making is paramount in the current fiscal year and beyond.
For enterprise leaders, investors, and product strategists, the overarching market narrative is defined by sustained expansion and evolving technological prerequisites. Historical data reveals a consistent upward momentum, with the market valuation climbing from 11.6 billion USD in 2020 to an estimated 16.5 billion USD by 2025. This trajectory is not merely a reflection of post-pandemic recovery but indicative of a structural shift in how industries approach quality assurance and risk mitigation. The forecast period anticipates a robust compound annual growth rate of 9.3 percent, propelling the market valuation toward 18.62 billion USD in 2026 and surpassing the 30 billion USD threshold by 2032. Such figures underscore a fertile environment for capital allocation, product development, and strategic partnerships. However, realizing value within this ecosystem requires navigating a complex web of regional variances, technological bifurcation, and regulatory tightening that only deep-dive intelligence can adequately decode.
Deconstructing the Market Architecture
A superficial glance at aggregate numbers offers limited strategic utility. True competitive advantage lies in understanding the granular mechanics that drive revenue streams across different modalities, end-user sectors, and geographic territories. The research provides a multi-dimensional segmentation analysis that illuminates where growth is concentrated and which sub-markets are maturing versus those poised for disruption.
Technological Modalities and Adoption Curves
The industry is characterized by a diverse array of testing methodologies, each serving distinct operational needs and capital constraints. Ultrasonic testing continues to command significant attention, reflecting its versatility in detecting internal flaws across a wide range of materials without causing damage. Radiographic testing maintains its relevance, particularly in scenarios demanding high-resolution imaging for complex geometries. Simultaneously, magnetic particle testing, eddy current testing, and emerging alternative types cater to specialized applications where surface defects, conductivity variations, or specific material properties are the primary concern.
Non-Destructive Testing Instruments Market
The strategic nuance here is not just in identifying the dominant techniques but in understanding the shifting cost-benefit analyses that influence procurement decisions. High upfront costs associated with advanced instruments, such as phased array ultrasonic and digital radiography systems, remain a barrier for small and medium enterprises. Yet, the pressure on component and sensor pricing is reshaping the affordability landscape. Our analysis dissects these pricing dynamics, average selling price trends, and the subtle trade-offs between capital expenditure and long-term inspection efficacy, enabling organizations to forecast budget requirements and technology roadmaps with precision.
Sectoral Demand Drivers
Demand for NDT instruments is inextricably linked to the operational intensity and safety criticality of downstream industries. The oil and gas sector remains a pillar of consumption, driven by the need to monitor pipelines, refineries, and offshore structures under harsh conditions. Power generation facilities, encompassing both traditional and renewable energy assets, rely heavily on inspection technologies to ensure grid stability and prevent catastrophic failures. Aerospace applications impose the most rigorous standards, where the margin for error is non-existent and regulatory compliance is absolute. Manufacturing, as a broad category, continues to expand its footprint, integrating NDT into production lines for real-time quality control. Other applications further diversify the revenue base, capturing niche but high-growth opportunities in automotive, rail, and marine sectors.
The report delves into the specific demand catalysts within each vertical, highlighting how operational downtime costs, regulatory penalties, and the push for predictive maintenance are reshaping procurement behaviors. By mapping these application-specific drivers, decision-makers can identify high-engagement segments and tailor their value propositions accordingly.
Geographic Value Distribution
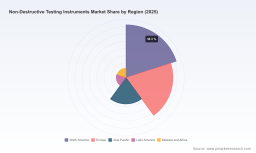
Regional dynamics play a pivotal role in shaping market opportunities. North America and Europe represent mature markets with established regulatory frameworks and high adoption rates of advanced technologies. Asia Pacific, while currently reflecting a different scale of valuation, is emerging as a critical growth engine fueled by rapid industrialization, infrastructure development, and increasing awareness of quality standards. Latin America and the Middle East and Africa contribute distinct regional profiles, often tied to resource extraction, energy projects, and localized manufacturing hubs.
The research avoids generic regional summaries, instead providing a nuanced view of how economic policies, trade dynamics, and local industrial priorities influence market penetration. Understanding these geographic nuances is essential for multinational corporations seeking to optimize their distribution networks and for regional players aiming to capture cross-border opportunities.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated structure, with a select group of leading entities commanding a significant share of total revenue. The top three competitors account for approximately 65.5 percent of the market, while the top five collectively hold around 82.2 percent. This concentration indicates the presence of established incumbents with strong technological portfolios, extensive service networks, and deep customer relationships. However, the remaining market share is distributed among a diverse array of specialized firms, creating a dynamic environment where innovation and niche expertise can disrupt traditional hierarchies.
Profiles of Key Industry Participants
The competitive arena is populated by organizations that have carved out distinct identities through technological specialization, geographic reach, and service integration. Mistras Group, Inc., headquartered in Princeton Junction, New Jersey, stands as a leading provider of NDT instruments and field inspection solutions, offering ultrasonic and advanced testing equipment tailored for industrial applications. Olympus Corporation, based in Shinjuku, Tokyo, is a major manufacturer focusing on ultrasonic phased array and thickness measurement systems, leveraging decades of imaging and sensing expertise.
Nikon Metrology NV, located in Tricht, Belgium, supplies X-ray and computed tomography instruments that cater to precision NDT applications, appealing to sectors where detailed internal visualization is paramount. Sonatest Ltd, operating from Hertfordshire, UK, produces portable ultrasonic and eddy current NDT instruments, addressing the need for field-deployable and flexible testing solutions. Acuren Corp., based in Markham, Ontario, Canada, provides advanced NDT equipment and inspection services, with a specialization in phased array and digital radiography instruments that bridge hardware and expertise.
Eddyfi Technologies, from Quebec City, Quebec, develops eddy current and remote NDT instruments specifically designed for pipeline and industrial use, emphasizing reliability in critical infrastructure monitoring. Zetec Inc., situated in San Jose, California, manufactures eddy current and magnetic particle NDT instruments, serving a broad customer base with robust and proven technologies. YXLON International GmbH, headquartered in Hamburg, Germany, produces X-ray NDT instruments and modules, contributing to the radiographic testing ecosystem with high-performance solutions. Fischer Technology Inc., located in Windsor, Connecticut, supplies coating thickness and material analyzers used in NDT contexts, addressing surface measurement and material verification needs. TWI Ltd, based in Cambridge, UK, provides advanced NDT testing instruments and systems for research and industrial use, acting as a bridge between cutting-edge development and practical deployment.
Recent Corporate Developments and M&A Activity
The competitive landscape is further shaped by a series of strategic moves that signal shifting priorities and consolidation trends. In April 2026, NDT Systems launched the BondHub Imaging Bond Tester with C-scan imaging capability, a product release that enhances composite inspection capabilities and reflects the growing emphasis on advanced imaging for non-metallic structures. This development underscores the industry's pivot toward multi-modal inspection tools that deliver actionable data faster.
Earlier in the forecast window, SGS introduced a new AI-driven inspection platform in November 2025, designed to enhance NDT accuracy through machine learning algorithms and automated defect recognition. This launch highlights the accelerating integration of artificial intelligence into inspection workflows, promising to reduce human error and increase throughput. In October 2025, Bureau Veritas executed an acquisition of a regional competitor to expand its advanced ultrasonic testing capabilities, a move that illustrates the strategic value of consolidating technological strengths and expanding service footprints.
Intertek entered a strategic partnership in September 2025 with a technology firm to develop a remote digital NDT inspection platform, signaling the industry's embrace of connectivity and remote monitoring. Such collaborations are becoming increasingly common as organizations seek to leverage external expertise and accelerate digital transformation. Additionally, Previan Technologies realigned Eddyfi Technologies and NDT Global as independent industrial-technology leaders in June 2026, a corporate restructuring that aims to sharpen focus and enhance agility within specialized segments of the market.
X-ray Non-destructive Testing Equipment Market
Industry Dynamics and Headwinds
Regulatory Evolution and Compliance Costs
Regulatory frameworks are tightening, with direct implications for both equipment suppliers and inspection service providers. The new ISO 9712-2025 standard, issued by ISO Technical Committee 135 in January 2026, increases the certification renewal frequency for NDT personnel to every three years, mandating compulsory retraining on advanced methods. This shift ensures that the workforce remains proficient with evolving technologies but also introduces recurring compliance costs and administrative burdens. Similarly, the EN 4179:2026 standard establishes updated minimum requirements for the qualification and certification of NDT personnel in aerospace applications, reinforcing the sector's demand for highly credentialed inspectors.
These regulatory changes elevate the importance of instrumentation that supports efficient training, certification, and documentation. Instruments that integrate with digital record-keeping systems or offer intuitive interfaces for complex procedures gain a competitive edge in an environment where compliance is non-negotiable. Furthermore, certification renewal changes in 2026 require more frequent retraining, driving up labor costs for qualified NDT personnel, as noted by industry sources in late 2025. This labor cost pressure incentivizes the adoption of tools that maximize inspector productivity and reduce the time required per inspection.
Cost Pressures and Adoption Barriers
Despite the favorable growth outlook, cost remains a pivotal factor influencing market penetration, particularly among smaller enterprises. The high upfront cost of advanced NDT instruments, including phased array ultrasonic and digital radiography systems, continues to limit adoption among small and medium enterprises. This barrier creates a bifurcation in the market, where large industrial players can accelerate their digital and advanced testing transformation, while smaller entities may rely on traditional methods or shared service models.
On the pricing front, averaged selling price trends for ultrasonic testing techniques showed increases through 2024, with ongoing pressure from component and sensor pricing in 2025. These dynamics suggest that manufacturers are navigating a delicate balance between maintaining margins and offering competitive pricing in a supply-constrained environment. Our analysis examines how these cost structures affect downstream pricing strategies and the total cost of ownership for end-users, providing clarity on where economies of scale can be leveraged and where value-added services can offset hardware costs.
Strategic Value of the Research for 2026 Decision-Making
In an environment defined by rapid technological change, regulatory evolution, and intense competitive maneuvering, access to granular, forward-looking intelligence is a strategic necessity. This research equips decision-makers with the analytical framework required to navigate uncertainty and capitalize on emerging opportunities.
Capital Allocation and Investment Strategy
For investors and corporate strategy teams, the forecast trajectory offers a compelling basis for portfolio decisions. The projected growth from 18.62 billion USD in 2026 to over 30 billion USD by 2032 indicates sustained demand across multiple cycles. Understanding which segments are expanding at higher rates, which technologies are gaining share, and which geographic regions are accelerating adoption allows for targeted investment in high-potential areas. The report's segmentation analysis helps identify where capital can be deployed with the highest return potential, whether in product innovation, market expansion, or strategic acquisitions.
Product Development and Technology Roadmapping
For manufacturers and technology developers, the research provides critical insights into the evolving requirements of end-users. The shift toward AI-driven platforms, remote digital inspection capabilities, and advanced imaging solutions signals where R&D efforts should be concentrated. By analyzing recent product launches and corporate realignments, organizations can benchmark their own innovation pipelines and identify gaps in the market. The discussion of cost pressures and pricing trends further informs go-to-market strategies, helping companies position their offerings to address both the premium segment seeking cutting-edge performance and the cost-conscious segment requiring accessible solutions.
Market Entry and Competitive Positioning
For companies considering market entry or expansion, the competitive landscape analysis offers a realistic assessment of the barriers and opportunities. The concentration of market share among top players highlights the importance of differentiation, whether through technological novelty, specialized application focus, or regional expertise. The profiles of key companies and recent strategic developments reveal the tactics that incumbents are employing to defend and grow their positions. Armed with this knowledge, new entrants can identify underserved niches, form strategic alliances, or develop disruptive business models that challenge the status quo.
Risk Management and Regulatory Compliance
For operators and service providers, the regulatory updates represent both a challenge and an opportunity. The increased frequency of certification renewals and the heightened requirements for advanced methods underscore the need for robust training programs and compliant instrumentation. The research integrates these regulatory dynamics into the broader market context, helping organizations anticipate compliance costs, plan workforce development, and select tools that streamline certification and documentation processes. By proactively addressing these factors, companies can mitigate operational risks and maintain their competitive standing in regulated industries.
Conclusion: The Path Forward
The Non-Destructive Testing Instruments Market is at an inflection point, where historical growth patterns are being amplified by technological innovation, regulatory tightening, and the imperatives of asset integrity across critical industries. The data landscape reveals a market on a robust growth trajectory, yet the true value for decision-makers lies in the strategic insights that connect macroeconomic trends to actionable business implications. This research serves as a comprehensive guide for navigating the complexities of the market, offering the depth and precision required to make informed investments, drive product innovation, and secure a resilient competitive position.
To fully capitalize on the opportunities outlined in this analysis, stakeholders are encouraged to access the complete report. The full study provides the detailed segmentation data, granular regional breakdowns, company-level assessments, and forward-looking scenarios that form the backbone of a winning strategy. By integrating this intelligence into your planning processes, you can transform market uncertainty into a structured pathway for sustainable growth and leadership in the years ahead.
For detailed analysis of this topic, please visit the official page: Non-Destructive Testing Instruments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


