



PW Consulting: Arts & Crafts Market Hits $56.26B in 2025, 5.6% CAGR to $82.38B by 2032

Unlocking Strategic Value in the Arts and Crafts Market: A 2026 Executive Briefing
The global arts and crafts industry is entering a decisive inflection point. As organizations navigate a landscape shaped by post-pandemic normalization, shifting consumer behaviors, and evolving supply chain dynamics, the ability to anticipate market trajectories has become a critical differentiator. PW Consulting’s latest comprehensive research on the Arts and Crafts Market delivers the analytical rigor and forward-looking intelligence required to transform uncertainty into executable strategy. This briefing outlines the structural forces reshaping the sector, examines the competitive architecture, and demonstrates how decision-makers can harness our 2026–2032 forecast framework to secure sustainable growth in an increasingly fragmented landscape.
Macro Trajectory and Structural Demand Signals
The sector has demonstrated remarkable resilience over the past half-decade, defying broader macroeconomic headwinds that constrained discretionary spending in adjacent consumer categories. Drawing on a rigorous historical baseline spanning 2020 through 2025, our analysis maps a consistent expansion trajectory that sets the foundation for sustained momentum across the forecast horizon. The market has steadily grown from a baseline valuation in the early 2020s to a substantially elevated valuation by 2025, reflecting robust demand across both retail and commercial channels.
This upward trajectory is projected to continue through the end of the decade, with total market valuation anticipated to reach new milestones by 2032. The compound annual growth rate of 5.6 percent underscores a steady, compounding expansion rather than a speculative spike. For executives, this implies that arts and crafts is transitioning from a cyclical lifestyle segment into a structurally supported consumer and commercial category. The persistence of demand is further validated by independent spending indicators, which confirm that consumer outlays for non-essential creative products remained resilient throughout 2025 despite cooling labor markets and lingering inflationary pressures. This divergence from broader discretionary trends suggests deep-seated behavioral shifts: creative engagement is increasingly viewed as a core wellness and community-building driver rather than a discretionary luxury.
Yet macroeconomic stability alone does not dictate strategic advantage. The operational environment is being reshaped by material sourcing constraints, regulatory scrutiny, and channel fragmentation. Nearly a quarter of global manufacturers experienced production schedule delays during 2025 as supply chain disruptions impacted imported raw materials. Simultaneously, a significant portion of consumers reported dissatisfaction with non-certified products sourced through unverified digital marketplaces. These friction points reveal a market that is simultaneously expanding and maturing, where quality assurance, compliance readiness, and supply chain transparency are rapidly becoming competitive moats rather than baseline operational requirements.
Segmentation Architecture and Application Dynamics
Understanding where value concentrates is essential for resource allocation, product positioning, and channel strategy. Our research dissects the market across multiple structural dimensions, revealing distinct demand pools that operate under different velocity and margin profiles. In the product taxonomy, traditional creative mediums continue to command the largest share of revenue, anchored by painting and drawing applications that reflect enduring consumer preference for accessible, expressive formats. Sewing and fabric-based activities represent the next major pillar, benefiting from the sustained DIY and home textile revival. Paper crafts, kid-focused creative kits, specialized arts and crafts tools, and a broader category of ancillary offerings complete the ecosystem, each with unique seasonal patterns, demographic affinities, and retail pathway requirements.
The application split further clarifies strategic priorities. Personal use dominates overall consumption, reflecting the sector’s deep roots in hobbyist, educational, and mindfulness-driven engagement. Commercial applications, while smaller in relative scale, represent a high-value growth vector where institutional procurement, retail merchandising, and professional-grade material specifications create distinct pricing and service expectations. Companies that treat personal and commercial demand as interchangeable risk diluting their value proposition. Instead, successful operators are designing bifurcated product architectures, distribution partnerships, and compliance frameworks that align with the specific purchasing criteria of each application vertical.
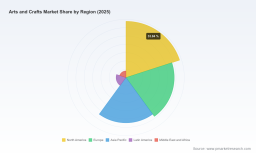
Geographic distribution tells a parallel story of maturity and emerging opportunity. North America and Europe continue to anchor substantial portions of total revenue, supported by established retail infrastructure, strong brand recognition, and mature consumer education around creative products. Asia Pacific presents a structurally significant footprint, driven by expanding middle-class participation, localized manufacturing capabilities, and accelerating digital commerce penetration. Latin America and the Middle East and Africa, while smaller in absolute terms, reflect incremental growth vectors where population demographics, informal retail networks, and rising disposable income create early-stage expansion potential. Crucially, these regional profiles are not static; they are being reshaped by cross-border commerce, localized product adaptation, and shifting regulatory environments, requiring executives to move beyond one-size-fits-all geographic assumptions.
Competitive Landscape and Strategic Positioning
The industry’s competitive architecture is characterized by a moderate concentration profile, with the top three players collectively holding a modest share of total market revenue and the top five firms extending that footprint only slightly further. This fragmented baseline indicates that scale alone is insufficient for durable advantage. Instead, differentiation is increasingly driven by brand trust, product innovation cadence, channel agility, and compliance readiness.
Several established players exemplify the strategic postures defining the current cycle. Crayola LLC maintains a dominant position in the children’s creative expression segment, leveraging iconic product architecture and recent campaign-driven innovation such as its 2025 launch of a newly positioned 64-count crayon box designed to reinforce brand heritage while stimulating renewed retail velocity. Faber-Castell AG anchors its positioning in premium art and graphic materials, emphasizing professional drawing instruments and marker systems that cater to both serious hobbyists and educational institutions. STAEDTLER Mars GmbH & Co. KG operates across a broad spectrum of drawing and coloring instruments, with a long-standing reputation for precision engineering and durable creative tools. F.I.L.A. Group extends its footprint through modeling clays, crayons, and related creative products, with brand portfolios that bridge educational and artistic use cases. Newell Brands Inc. operates as a diversified portfolio player, integrating writing instruments, markers, and craft supplies across multiple recognized brand assets, enabling cross-category bundling and broad retail distribution.
These enterprises illustrate two divergent but complementary strategic playbooks. The first prioritizes category leadership within high-visibility product families, using brand equity, packaging innovation, and campaign-led demand generation to defend share and drive trial. The second emphasizes portfolio breadth, channel leverage, and operational scale to capture share across multiple sub-segments and retail formats. For market entrants and mid-tier operators, the strategic implication is clear: competing on volume alone against entrenched portfolios is inefficient. Sustainable positioning requires a clearly defined value narrative, whether anchored in premium material quality, educational alignment, demographic targeting, or supply chain reliability.
Operational Realities and Compliance Imperatives
Strategic planning in this sector must account for a growing layer of operational complexity. Regulatory frameworks are becoming more explicit, particularly in the United States, where manufacturers must align with chronic toxicity labeling requirements and toy safety standards before products reach retail shelves. Compliance is no longer a back-office function; it is a market access prerequisite that directly influences shelf eligibility, retailer confidence, and consumer trust. Organizations that embed regulatory readiness into product development cycles gain a distinct advantage in speed-to-market and risk mitigation.
Quality assurance is equally decisive. The proliferation of unverified online retail channels has introduced significant variability in product authenticity and material safety. Consumer dissatisfaction with non-certified supplies has become a material reputational and retention risk, particularly in categories where parents, educators, and professional creators prioritize predictable performance and safe material composition. Companies that invest in certification transparency, traceability systems, and channel vetting protocols are better positioned to defend margin integrity and reduce returns, while also building the trust capital necessary to expand into higher-value application segments.
Supply chain resilience represents a third operational imperative. Imported material dependencies have exposed production schedules to volatility, forcing manufacturers to reassess sourcing diversification, inventory buffers, and lead-time planning. The firms that treat supply continuity as a strategic capability, rather than a tactical procurement function, will be better equipped to protect launch calendars, maintain retail availability, and respond to demand spikes without compromising margin structure.
How This Research Converts Intelligence into Execution
PW Consulting’s Arts and Crafts Market report is engineered for decision-makers who require more than high-level trend commentary. The study integrates historical performance, forward-looking forecasts, and granular segmentation analysis into a single strategic framework designed to inform product roadmaps, channel investment, pricing architecture, and competitive positioning. Readers will gain access to structured evaluations of market sizing across multiple time horizons, enabling scenario planning that accounts for both base-case momentum and structural inflection points.
Arts and Crafts Market
The report provides a detailed segmentation map that clarifies how revenue distributes across product types, application contexts, and regional demand pools. Rather than presenting static share figures in isolation, the analysis ties each segment to underlying demand drivers, purchasing behavior patterns, and channel dynamics, allowing stakeholders to identify where incremental investment is likely to yield the strongest returns. Competitive profiling extends beyond corporate descriptions to examine strategic posture, product architecture, and market signaling, giving executives a practical lens for benchmarking their own positioning against incumbent playbooks.
Operational context is embedded throughout. Regulatory expectations, consumer quality perceptions, and supply chain friction points are evaluated not as peripheral risks but as strategic variables that influence product design, channel selection, and go-to-market timing. By connecting market structure to execution realities, the research enables teams to prioritize initiatives that are both commercially attractive and operationally feasible.
For organizations evaluating market entry, category expansion, or portfolio optimization, the study offers a structured basis for opportunity sizing and risk assessment. For incumbent players, it provides a diagnostic framework to pressure-test growth assumptions, identify vulnerable share pockets, and align innovation pipelines with the segments most likely to compound value over the forecast period.
Worldwide Harbor Craft Market
Strategic Imperatives for 2026 and Beyond
The next phase of growth in the arts and crafts sector will be defined by how effectively organizations translate market visibility into disciplined execution. Several priorities stand out. First, companies must calibrate portfolio investment to segment velocity rather than historical familiarity, recognizing that demand dynamics differ sharply between personal and commercial applications, as well as across product families. Second, brand trust and compliance readiness must be treated as revenue-enabling assets, particularly as channel fragmentation increases and consumer scrutiny around product safety intensifies. Third, supply chain design should be aligned with market expansion goals, ensuring that sourcing strategies, inventory planning, and launch sequencing can sustain availability during periods of demand acceleration.
Finally, competitive positioning requires honest segmentation of the playing field. With market concentration remaining moderate, the opportunity for targeted share capture exists, but it will accrue to organizations that define a clear value proposition, execute consistently across the chosen channel mix, and invest in the operational foundations that protect margin and reputation over time.
The full scope of our 2026–2032 analysis extends far beyond the directional signals outlined here. Detailed segmentation trajectories, competitive benchmarking, regional demand mapping, and scenario-based revenue pathways are available in the complete report. Executives seeking to convert market momentum into measurable strategic advantage are encouraged to access the full research suite, where the underlying intelligence is structured to support board-level planning, product strategy, and commercial execution with precision.
For detailed analysis of this topic, please visit the official page: Arts and Crafts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


