



PW Consulting: Aircraft Piston Engines Market to Hit USD 7,152.97M by 2032 at 5.2% CAGR

Navigating the Sky: Strategic Intelligence for the Aircraft Piston Engines Market (2026-2032)
The global aviation landscape is undergoing a subtle yet profound transformation. While much attention dominates the headlines regarding sustainable aviation fuels and electric propulsion, the heartbeat of general aviation remains steadfastly dependent on the internal combustion piston engine. For stakeholders, investors, and strategic planners, understanding the trajectory of this mature yet evolving market is not merely an academic exercise—it is a critical component of risk mitigation and growth strategy for the 2026 fiscal year and beyond.
PW Consulting is proud to introduce our comprehensive market intelligence report on the Aircraft Piston Engines Market. This document serves as a strategic compass for navigating the complexities of engine manufacturing, aftermarket support, and regulatory compliance over the forecast period extending to 2032. By synthesizing historical data with forward-looking projections, this study provides the granularity required to make informed capital allocation and product development decisions.
Market Trajectory and Historical Context
The resilience of the piston engine sector is evident when examining the revenue trends over the past half-decade. From 2020 to 2025, the market demonstrated a consistent upward trajectory, recovering from global supply chain disruptions and ramping up to meet renewed demand in general aviation. Revenue figures have climbed steadily, reflecting both increased production rates and healthy pricing power within the supply chain.
Looking forward, the market is projected to expand from an estimated 5,270 million USD in 2026 to approximately 7,153 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2 percent throughout the forecast period. This rate suggests a market that is not only recovering but maturing, driven by replacement cycles, fleet expansion in emerging economies, and technological upgrades in existing airframes. For decision-makers, these top-line figures validate the sector as a stable investment vehicle with predictable long-term returns, though the allocation of these revenues across different segments requires deeper analysis provided in our full report.
Segmentation Dynamics: Types, Applications, and Geography
Understanding where value is generated within the market is crucial for targeting investments. The market is divided into distinct categories based on engine architecture, operational application, and regional demand. While specific percentage splits are detailed within the proprietary sections of our study, the structural composition reveals key preferences among manufacturers and operators.
In terms of engine type, the market is anchored by Horizontally Opposed, Inline, and Radial configurations. The dominance of certain architectures often correlates with specific aircraft categories, influencing supply chain requirements and manufacturing capabilities. Similarly, the application landscape is diversified across Training, Aerial Work, and Private and Recreational segments. The training sector, for instance, remains a critical volume driver due to the perpetual need for pilot certification, whereas aerial work demands durability and specific performance metrics. Private and recreational use continues to be a significant contributor, fueled by hobbyist enthusiasm and personal aviation ownership.
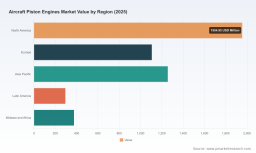
Geographically, the demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, economic conditions, and fleet ages that dictate consumption patterns. Our analysis highlights how regional discrepancies in certification standards and economic growth rates create varied opportunities for engine manufacturers and service providers.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established legacy manufacturers and innovative entrants focusing on alternative fuel capabilities. The market concentration, indicated by a CR5 of 26.2 percent, suggests a moderately fragmented industry where niche players can still carve out significant market share through specialization.
Lycoming Engines, based in Williamsport, Pennsylvania, remains a cornerstone of the industry. Their production of four-, six-, and eight-cylinder piston engines up to 400 horsepower supports a vast array of general aviation, training, and commercial aircraft. Notably, their engines power over half of the world's general aviation fleet, establishing a reputation for reliability that creates high switching costs for operators.
Continental Aerospace Technologies, headquartered in Mobile, Alabama, competes closely with a focus on advanced designs. They manufacture piston engines capable of running on both Jet-A and avgas, accumulating over 12 million flight hours. Their recent moves highlight a strategic pivot towards fuel flexibility and certification in new sectors.
Aircraft Piston Engines Market
BRP-Rotax, located in Austria, serves a specialized niche by developing engines for light sport, ultralight, and training aircraft. Their focus on the lower end of the weight and power spectrum allows them to dominate segments where traditional general aviation engines are too large or costly.
DeltaHawk Engines, based in Racine, Wisconsin, represents the innovative frontier. They manufacture FAA-certified jet-fuel-burning piston engines, such as the DHK180 and DHK6A350. By enabling the use of heavy fuel in piston engines, they address logistical advantages in remote operations and reduce dependency on traditional avgas supplies.
Recent Developments and Technological Shifts
The period leading into 2026 has seen significant activity regarding product launches and certifications that will shape the next cycle of market growth. These events signal a shift towards fuel flexibility and expanded operational envelopes.
In July 2025, Piper Aircraft, Inc. announced the Piper Seminole DX, powered by DeltaHawk's FAA-certified DHK4A180 180-hp heavy fuel engine. The order book opened at EAA AirVenture 2025, marking a tangible entry of heavy-fuel piston technology into multi-engine training and commercial applications. This development is particularly significant given the regulatory backdrop. FAA certification flight testing for the Piper Seminole DX with the DeltaHawk engine commenced in November 2025, with certification expected in Q3 2026. This timeline suggests that full market availability and subsequent fleet integration will accelerate demand in the latter half of the forecast period.
Continental Aerospace Technologies achieved a milestone in April 2026 by receiving EASA approval for the CD-170R Jet-A piston engine for rotorcraft applications. This marks the first certified Jet-A FADEC-controlled helicopter piston engine. By bridging the gap between fixed-wing efficiency and rotary-wing operational needs, this certification opens a new revenue stream that was previously inaccessible to piston engine manufacturers.
Jet Engines Market
Simultaneously, DeltaHawk Engines achieved FAA Type Certification for the DHK180 jet-fuel piston engine in June 2025, with the first flight occurring in a Van's RV-14. This certification validates the technical viability of heavy-fuel piston engines in experimental and general aviation categories, encouraging further adoption among builders and operators seeking fuel security.
These technological strides are supported by broader industry data. The General Aviation Manufacturers Association (GAMA) reported that piston airplane deliveries increased by 4.2 percent in 2024 to 1,772 units. This uptick in unit shipments provides a strong foundational demand signal for engine manufacturers, indicating that airframe production is aligning with engine supply capabilities.
Strategic Implications for 2026 Decision-Makers
For executives and planners preparing budgets and strategies for 2026, several implications arise from this landscape. First, the reliance on avgas remains a strategic vulnerability for many operators, making the adoption of Jet-A capable engines a potential risk mitigation strategy. The certifications achieved by Continental and DeltaHawk in 2025 and 2026 provide viable alternatives that should be evaluated against total cost of ownership and logistics.
Second, the fragmentation of the market means that partnership opportunities exist beyond the top tier. With a CR5 of only 26.2 percent, there is room for specialized manufacturers to thrive, particularly in training and aerial work segments where specific power-to-weight ratios are prioritized over raw horsepower. Supply chain resilience is also paramount; understanding the geographic distribution of demand helps in positioning inventory and service centers to minimize downtime.
Finally, regulatory timelines are critical path items. The expected FAA certification for the Piper Seminole DX in Q3 2026 is a catalyst that could spur orders in the training and commuter segments. Stakeholders should align their procurement and hiring strategies to anticipate the ripple effects of this certification on maintenance training and parts inventory.
Report Scope and Methodology
This strategic insight is derived from a robust methodology that combines primary research with extensive secondary data analysis. The full report offers a deep dive into the factors influencing market growth, including regulatory frameworks, technological innovations, and economic indicators.
Readers of the complete study will gain access to detailed segmentation analysis that breaks down market value by region, type, and application, allowing for precise market sizing. The competitive profiling extends beyond basic company statistics to include strategic positioning, recent M&A activity, and product pipeline assessments. Furthermore, the report addresses the constraints and challenges facing the industry, such as fuel availability, emission standards, and supply chain bottlenecks.
Our analysis covers the forecast period from 2026 to 2032, providing a long-term view that supports capital expenditure planning and technology roadmap development. Whether you are a manufacturer looking to expand your portfolio, an investor assessing market entry barriers, or an operator optimizing fleet composition, the data contained herein is tailored to support those specific objectives.
Conclusion
The Aircraft Piston Engines Market stands at a inflection point where traditional reliability meets modern fuel flexibility. The growth projected through 2032 is not merely a reflection of historical trends but a result of active innovation in engine technology and expanding operational scopes. For organizations aiming to lead in this sector, access to granular, verified data is the differentiator between reactive management and proactive strategy. This report provides the foundation necessary to navigate the coming years with confidence.
For detailed analysis of this topic, please visit the official page: Aircraft Piston Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


