



PW Consulting: Dry Ice Machine Market to Reach $344.8M by 2032, 5.5% CAGR

Navigating the Cold Front: Strategic Insights for the Dry Ice Machine Market Through 2032
The global industrial landscape is undergoing a silent but significant transformation, driven by the need for sustainable cleaning solutions, stringent cold chain requirements, and the relentless pursuit of operational efficiency. At the heart of this shift lies the Dry Ice Machine Market. As enterprises face increasing pressure to adopt eco-friendly technologies while maintaining rigorous safety standards, understanding the trajectory of dry ice production and blasting equipment becomes not just an option, but a strategic imperative. Our latest market research provides a comprehensive roadmap for stakeholders looking to capitalize on these emerging opportunities between 2026 and 2032.
In an era where data transparency dictates competitive advantage, decision-makers require more than surface-level estimates. They need a granular understanding of how market forces interact, how regulatory frameworks evolve, and where the capital flows are heading. This introduction serves as a high-level overview of the intelligence contained within our full study, designed to equip senior leadership with the context needed to interpret the broader market signals before diving into the specific methodologies and breakdowns available in the complete report.
Macro Economic Trajectory and Growth Signals
Historical data suggests a resilient upward trend for the dry ice machine sector, reflecting broader industrial adoption rates and the substitution of traditional abrasive cleaning methods with cryogenic alternatives. Our analysis tracks revenue performance from 2020 through the base year of 2025, establishing a solid foundation for forecasting the period extending to 2032. The market has demonstrated consistent expansion, moving from a valuation of approximately 163.15 million USD in 2020 to a projected 215.0 million USD by 2025. This trajectory underscores a mature yet accelerating adoption curve.
Dry Ice Machine Market
Looking forward, the forecast period indicates sustained momentum. The market is expected to reach 231.45 million USD in 2026, climbing steadily to 344.8 million USD by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 5.5 percent over the forecast horizon. Such a rate suggests a balanced expansion where technological innovation meets steady demand across key verticals. For investors and manufacturers, this CAGR signals a stable environment for capital deployment, albeit one that requires careful monitoring of regional nuances and operational costs.
It is crucial for strategists to recognize that these aggregate figures mask complex underlying drivers. The revenue growth is not uniform across all product categories or geographic zones. While the top-line numbers indicate a healthy market, the distribution of value across different machine types and application sectors varies significantly. Our full report dissects these variations to reveal which specific segments are outpacing the average growth rate and which are facing headwinds due to saturation or regulatory constraints.
Segmentation Landscape: Types and Applications
The market is diversified across several machine types, each catering to distinct production needs and output specifications. The landscape includes pellet dry ice production machines, block dry ice production machines, and slice dry ice production machines. Each type serves a unique function within the supply chain, influencing everything from storage logistics to end-user application efficiency. Understanding the revenue contribution of each category is essential for manufacturers deciding where to focus R&D resources.
Dry Ice Market
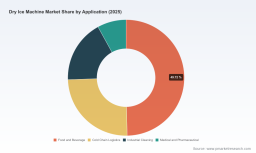
Similarly, the application sector drives significant demand variance. Key verticals include food and beverage, cold chain logistics, industrial cleaning, and medical and pharmaceutical uses. The food and beverage sector often leads in volume due to the critical need for temperature control during processing and transport, while industrial cleaning sees strong uptake due to the environmental benefits of dry ice blasting over sand or chemical blasting. Medical applications, though smaller in volume, command high compliance standards that impact machine specification requirements.
However, precise revenue splits and percentage contributions for these segments are sensitive competitive intelligence. In our complete market study, we detail exactly how these segments compare in terms of market share and growth velocity. Access to this level of detail allows procurement officers and product managers to benchmark their internal portfolios against the broader industry standard. Without this granular view, companies risk misallocating resources to slower-growing niches while missing high-potential opportunities in emerging applications.
Regional Market Dynamics and Distribution
Geographic distribution plays a pivotal role in shaping market strategy. The global landscape is divided into key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique mix of regulatory environments, industrial density, and cold chain infrastructure maturity. Historically, North America and Asia Pacific have shown robust activity, reflecting strong industrial bases and varying degrees of adoption in logistics and cleaning sectors.
Europe continues to maintain a significant presence, driven by strict environmental regulations that favor dry ice blasting over chemical alternatives. Meanwhile, emerging markets in Latin America and the Middle East and Africa represent areas of potential expansion, though they come with distinct infrastructural challenges and varying raw material availability. The interplay between these regions creates a complex trade flow and supply chain dynamic that affects pricing and availability of equipment.
Detailed regional revenue figures and growth rates are central to our full analysis. These metrics help multinational corporations determine where to prioritize sales channels and where local manufacturing might offer a competitive edge against imports. For a precise understanding of which regions are contributing the most to the global revenue pool and how their growth rates compare to the global average, stakeholders are encouraged to refer to the complete regional breakdown provided in the full report. This ensures that expansion strategies are grounded in accurate local market intelligence rather than generalized assumptions.
Competitive Landscape and Key Incumbents
The market features a mix of established players and specialized innovators, operating across multiple continents. Concentration levels indicate a moderately fragmented environment, with the top three companies holding approximately 24.6 percent of the market and the top five reaching 26.2 percent. This structure suggests that while there are dominant forces, there is still room for niche players to compete on technology or regional specialization.
Key companies shaping the industry include Cold Jet, LLC based in San Marcos, Texas, known for advanced dry ice production pelletizers and blasting equipment focusing on energy-efficient CO2 utilization. CRYONOMIC in Belgium offers hydraulic drive solutions for crystal-hard pellets and sticks in semi-automated industrial settings. ASCO Carbon Dioxide Ltd from Switzerland specializes in automatic pelletizers capable of multiple thicknesses for food-grade and industrial use. Other notable entities include Artimpex nv and IceTech in the United States, Alfred Kärcher SE & Co. KG in Germany, TOMCO2 Systems, Aquila Triventek, and Ziyang Sida Cryogenic Machine Co., Ltd. in China.
Recent industry movements highlight the dynamic nature of this competition. For instance, Cold Jet has been particularly active, launching a new line of dry ice blasting machines for the food processing industry in August 2025, followed by the introduction of the PR750H industrial pelletizer in November 2025 and the PE 80 High-Efficiency Pelletizer in February 2026. These launches demonstrate a clear focus on efficiency and versatility across pellet sizes. Meanwhile, CRYONOMIC appointed Multico svl. as a distributor for Romania in November 2025, and ICS exhibited at Auto Exotica 2026 in April, signaling ongoing efforts to expand distribution networks and brand visibility in specific verticals like automotive.
Competitor profiling in our full report goes beyond product listings. It analyzes market positioning, recent strategic moves, and the implied focus areas based on public announcements. For investors, understanding the cadence of product launches and distribution expansions provides clues about where each company sees the highest growth potential. This intelligence is vital for partnership due diligence or for identifying acquisition targets that align with long-term strategic goals.
Critical Market Dynamics and Operational Considerations
Beyond pure economics, the dry ice machine market is heavily influenced by regulatory and operational factors that impact total cost of ownership and deployment feasibility. Safety and compliance are not merely checkboxes; they are structural components of the market that define where and how equipment can be utilized. Our research integrates these dynamics to provide a realistic view of market barriers and facilitators.
Regulatory Frameworks and Safety Protocols
Operators must navigate a complex web of safety standards when deploying dry ice production and blasting equipment. A primary requirement is the use of equipment only in properly ventilated spaces that comply with local and national regulatory standards. This constraint impacts facility design and limits the types of environments where dry ice blasting can be implemented without significant infrastructure upgrades.
Exposure limits are another critical factor. Guidelines often dictate that exposure to dry ice must follow specific occupational safety standards, such as maintaining CO2 levels below certain thresholds over an 8-hour workday with continuous monitoring. For example, adherence to OSHA guidelines regarding 5,000 ppm limits requires facilities to invest in monitoring systems, adding to the capital expenditure associated with dry ice technology adoption.
Transportation and logistics also face strict oversight. All dry ice transportation containers must meet DOT regulations for hazardous materials labeling and emission controls. This affects the downstream logistics of companies utilizing dry ice for shipping or cleaning, influencing the choice of production machines that can integrate smoothly with compliant packaging and distribution workflows. Additionally, safety protocols for blasting equipment include the use of insulated containers and compliance with federal regulations on hazardous materials, ensuring that both operators and the environment are protected during industrial cleaning processes.
Raw Material Economics and Supply Chain Volatility
The economics of dry ice production are intrinsically linked to the availability and pricing of CO2 feedstock. Raw material expenses remain subject to fluctuations in CO2 supply, which can be influenced by seasonal demand in other sectors, such as beverages or welding, and broader industrial production cycles. This volatility introduces a variable cost element that manufacturers must factor into their pricing models and long-term contracts.
Current sector analysis indicates that average pellet prices can range significantly, reflecting the interplay between supply constraints and regional demand spikes. For machine operators, this means that the efficiency of the production machine—measured in yield and energy consumption per pound of dry ice—is a critical metric for profitability. Machines that optimize CO2 utilization can mitigate some of the impact of raw material price swings, offering a competitive advantage to operators who invest in higher-efficiency technology.
Our full report delves into the sensitivity analysis regarding raw material costs and how they impact the overall market revenue projections. By understanding the correlation between CO2 pricing trends and machine utilization rates, businesses can develop more robust financial models. This level of insight is necessary for forecasting operational budgets accurately and avoiding margin erosion during periods of supply tightness.
Strategic Implications for 2026 and Beyond
For enterprises operating in or adjacent to the dry ice machine market, the period from 2026 to 2032 offers both challenges and opportunities. The projected growth suggests that demand will not vanish, but the competition for market share will intensify. Success will depend on the ability to interpret data correctly, anticipate regulatory shifts, and align product offerings with the specific needs of high-growth applications.
Strategic decision-makers should consider the following implications based on the macro trends identified:
- Technology Investment: With new product launches focusing on high-output and multi-size capabilities, R&D should prioritize flexibility and energy efficiency to match evolving customer requirements in food processing and industrial cleaning.
- Compliance Integration: Safety regulations are tightening. Equipment that integrates monitoring and ventilation compliance features directly into the production system may gain preference in regulated industries like pharmaceuticals and food safety.
- Regional Strategy: While global growth is steady, regional disparities require tailored approaches. Distributors and sales teams need localized data to identify regions where infrastructure supports dry ice adoption versus those hindered by supply chain or regulatory hurdles.
- Supply Chain Resilience: Given the volatility in CO2 feedstock prices, partnerships with reliable gas suppliers and investment in machines with high conversion efficiency will be key to maintaining margins.
Ultimately, navigating this market requires more than a glance at the headline CAGR. It demands a deep dive into the segmentation splits, competitive maneuvers, and regulatory undercurrents that define the daily operations of the industry. Our comprehensive market research report is designed to provide that depth. It offers the specific breakdowns, detailed company profiles, and forward-looking risk assessments necessary to build a resilient strategy.
To access the full suite of data, including precise regional valuations, detailed application segment sizes, and complete competitive benchmarking, we invite you to review the full publication. The insights contained within are crafted to support informed decision-making, ensuring that your organization is prepared to lead rather than follow in the evolving landscape of dry ice production and blasting technology.
For detailed analysis of this topic, please visit the official page: Dry Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


