



PW Consulting: Digital Content Market Hits $191.55B in 2025, Projected to Reach $761.75B by 2032

Navigating the Surge: A Strategic Framework for the Digital Content Market Through 2032
The global digital content ecosystem is undergoing a structural transformation that demands immediate strategic attention. As we move deeper into the 2026 fiscal cycle, enterprise leaders face a complex intersection of accelerating addressable demand, evolving regulatory expectations, and rapid technological substitution across creation, distribution, and monetization layers. At PW Consulting, we have synthesized multi-year historical performance with forward-looking structural indicators to deliver a comprehensive assessment of how this market will evolve through 2032, and what disciplined capital allocation and capability investment require in response.
The opportunity set is substantial, but it is not uniformly distributed. Organizations that continue to treat content as a tactical output channel will find themselves outpaced by competitors who recognize it as a core infrastructure investment. This research note outlines the macroeconomic trajectory, competitive fault lines, regulatory friction points, and operational leverage points that should shape board-level discussion in the coming quarters.
Market Trajectory and the 2026 Inflection Point
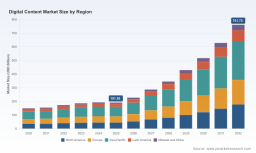
The historical record from 2020 through 2025 reveals a market that experienced rapid expansion followed by a period of measured correction and consolidation. Revenue climbed from a baseline of 149.4 billion USD in 2020 to a peak near 193.12 billion USD in 2024, before settling at approximately 191.55 billion USD in 2025. This 2025 adjustment reflects a combination of macroeconomic recalibration, platform-level monetization optimization, and early cost-reduction pressures from automation adoption. Rather than signaling demand erosion, this phase represents a maturation inflection where volume-driven growth gives way to value-driven growth.
Looking forward, the forecast period from 2026 through 2032 projects a sustained upward arc, starting at 227.63 billion USD in 2026 and scaling toward 761.75 billion USD by 2032. The implied compound annual growth rate of 5.1 percent over the forecast horizon may appear measured on the surface, yet it understates the structural reallocation occurring beneath the aggregate figure. Growth will not be evenly distributed across formats, channels, or geographies. Certain content modalities will capture disproportionate share as production economics shift, while legacy consumption patterns face compression from agentic workflows and AI-native generation pipelines.
For decision-makers, the critical takeaway is timing. Entering new content investment cycles without segmentation intelligence risks capital misallocation into formats or platforms that will face margin erosion within the forecast window. Conversely, organizations that align capability building with the segments showing durable monetization resilience can capture both top-line expansion and operating leverage.
What the Research Delivers: Actionable Intelligence Beyond the Headline
This study is designed as a decision-support instrument, not a static size-and-growth summary. It translates market architecture into operational implication across multiple planning horizons. The report framework is organized to answer four questions that recur in boardrooms and strategy functions alike: where is value accumulating, who controls the enabling infrastructure, what constraints will reshape cost and compliance structures, and how should a portfolio of content initiatives be sequenced.
The segmentation architecture maps content types, application environments, and regional demand profiles to identify where scale advantages and growth momentum diverge. Rather than presenting undifferentiated totals, the analysis isolates structural drivers such as production cost curves, audience engagement durability, platform dependency risk, and monetization pathway maturity. This allows strategy teams to distinguish between segments that are expanding on the strength of fundamental consumption shifts and those that are temporarily inflated by promotional cycles or platform subsidy dynamics.
The competitive landscape review examines the strategic positioning, technology roadmaps, and ecosystem leverage of leading platform and creation-oriented players. The assessment focuses on how each organization is shaping the supply side of content production, the degree to which integrated toolchains are creating switching costs, and where emerging interoperability or licensing models may alter competitive moats. This lens is particularly important for enterprises evaluating partnership structures, vendor consolidation, or build-versus-buy decisions for content operations.
The report also incorporates cross-cutting industry dynamics that influence execution risk. Regulatory developments around accessibility, content transparency, and platform accountability are not peripheral compliance issues; they are becoming design constraints that affect development timelines, cost structures, and market access. By mapping these requirements against current capability maturity, the research enables teams to forecast implementation burden and prioritize remediation or redesign efforts before they become growth bottlenecks.
Finally, the study integrates recent commercial and intellectual property developments that signal how the infrastructure layer of content delivery, rights management, and creator compensation is being reconstituted. These developments matter because they alter the downstream economics of distribution and monetization, influencing how value is captured once content reaches end users.
Digital Notes Market
Competitive Architecture and the Battle for Creation Leverage
The competitive field is increasingly defined by organizations that can compress the distance between idea, production, and distribution while preserving quality and brand consistency. Several platform-scale players are extending their influence through integrated creation suites that combine workflow tooling, storage, versioning, and AI-assisted generation within a single operational environment.
Microsoft Corporation has positioned its suite around productivity and content operations, embedding creation, storage, and management capabilities across familiar interface environments. Its strategy emphasizes continuity between professional documentation, presentation, and video editing workflows, which reduces friction for enterprise content teams that already operate within its productivity ecosystem. The integration of assistant-oriented creation features further accelerates draft-to-final timelines for internal and external content assets.
Digital Content Market
Alphabet Inc. has pursued a parallel path through collaborative workspace tooling and video production assistance, emphasizing AI-supported editing and management within cloud-native environments. Its approach leverages widespread adoption of its collaboration and communication infrastructure, aiming to make content creation a natural extension of daily operational workflows rather than a separate production discipline.
Adobe Inc. continues to anchor its position in professional-grade content creation, with a focus on high-fidelity visual production, compositing, and managed asset workflows. The integration of generative capabilities into its core creative environment is reshaping production economics by reducing manual iteration cycles, particularly for creative teams working under cost and turnaround pressure. Adobe's trajectory signals a market where professional creation tools are becoming more accessible through AI augmentation, expanding the producer base while simultaneously raising the bar for differentiated output quality.
Canva Inc. has expanded its relevance beyond lightweight graphic design into broader content generation, including video and conversational, agentic design workflows. Its recent introduction of a foundation-model-driven design layer reflects a broader industry shift toward prompt-mediated production with layered, editable outputs. This lowers the skill threshold for content creation, which expands participation but also intensifies competition for audience attention in already saturated channels.
Beyond these established players, the infrastructure and rights-management layer is beginning to attract targeted innovation. Recent patent activity and structured commercial intake initiatives from emerging infrastructure-oriented providers indicate growing attention to verified content delivery, stateful media handling, and rights-controlled access. These developments suggest that the market is moving toward more explicit mechanisms for tracking delivery, enforcing access conditions, and aligning creator compensation with verifiable consumption. For content-dependent enterprises, this infrastructure evolution may eventually influence platform selection, licensing strategy, and revenue-sharing expectations.
Structural Dynamics Shaping Cost, Compliance, and Content Design
Market growth does not occur in a regulatory vacuum. A series of accessibility and content-accountability mandates is reshaping how digital content must be designed, deployed, and monitored. In the United States, accessibility standards adopted by federal health and justice agencies established expectations aligned with web content accessibility guidelines at a defined compliance level for web and mobile content. This creates a durable design requirement that affects user interface decisions, media asset preparation, and testing workflows across content operations.
In parallel, the European accessibility framework introduced compliance obligations for digital products and services, including websites and applications, with deadlines that have already come into force for relevant organizations. For companies operating across multiple jurisdictions, these requirements introduce a multi-layered compliance map that must be reconciled during product and content development rather than retrofitted afterward. Failure to internalize these constraints early can lead to rework, delayed launches, and elevated assurance costs.
Beyond accessibility, content accountability expectations are expanding. Policy guidance from child health and development authorities has emphasized the importance of transparent metrics around content intended for younger audiences, signaling a likely trajectory toward more structured reporting and content governance in specific segments. For platforms and brands with significant youth-facing content exposure, this introduces an additional governance and disclosure layer that should be factored into operating models.
Production economics are also shifting. Recent industry analysis from a major creative software provider highlights growing demand for AI-augmented workflows aimed at reducing creation time and cost. This is not merely a productivity narrative; it is a structural pressure on the cost base of content production. Teams that successfully integrate assisted generation, asset reuse, and automated iteration can expand output volume without proportionate headcount growth. Teams that do not adapt risk margin compression as production expectations rise while budget constraints remain tight.
Strategic Priorities for 2026 Decision-Making
Translating these dynamics into action requires a disciplined approach that balances growth ambition with execution realism. The following priorities should anchor near-term planning.
- Align content investment with segment-level resilience rather than aggregate market momentum, since growth concentration varies materially across formats and application environments
- Evaluate creation and distribution toolchains for integration depth, switching cost exposure, and AI workflow compatibility, recognizing that vendor selection increasingly shapes long-term operating economics
- Build accessibility and content governance requirements into design and development cycles from the outset, treating them as product constraints rather than retrospective compliance tasks
- Assess licensing, rights management, and delivery-verification developments as potential sources of future monetization structure, particularly where content distribution depends on third-party platforms or partner networks
- Sequence capability investments so that AI-assisted production enhances differentiation rather than merely compressing cost, since lower production barriers will intensify competition for audience attention
- Monitor competitive moves in both creation tooling and delivery infrastructure, because shifts in either layer can alter the economics of content reach, retention, and revenue capture
The 2026 planning cycle is not simply a matter of forecasting demand; it is a matter of positioning portfolios, partnerships, and operating models against a market that is expanding while simultaneously reorganizing itself around automation, regulation, and infrastructure change. Organizations that approach the market with segmented intelligence, compliance-aware design, and strategic clarity on where value will accrue will be better placed to convert growth into durable advantage.
The complete analysis, including detailed segmentation trajectories, competitive positioning matrices, and regional demand breakdowns, is available through our full Digital Content Market research release. We encourage strategy and commercial leadership teams to review the full dataset to inform capital allocation, platform strategy, and content operating model decisions for the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Digital Content Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


