



PW Consulting: Tubular Steel Wind Tower Market Hits $8.31B in 2025, 7.3% CAGR to 2032

Navigating the Steel Skeleton of Wind Energy: Strategic Insights for the Tubular Steel Wind Tower Market 2026-2032
Executive Preface: Why This Intelligence Matters Now
The global energy transition is no longer a theoretical trajectory; it is a supply chain imperative. As wind farm developers push for higher capacity factors and greater hub heights, the demand for robust tubular steel wind towers has entered a critical inflection point. Our latest comprehensive study, covering historical performance from 2020 through 2025 and a detailed forecast extending to 2032, provides the analytical rigor required to navigate this complex landscape. This article serves as a strategic preview of that research, designed to equip corporate strategy teams, procurement leaders, and investors with a clear understanding of the market forces at play.
In 2026, decision-making cannot rely on outdated assumptions. The market has demonstrated consistent growth, with revenue figures climbing from approximately 5.84 billion USD in 2020 to a projected 8.66 billion USD in 2026. Looking further ahead, the trajectory points toward 13.61 billion USD by 2032. This represents a compound annual growth rate of 7.3 percent over the forecast period. These numbers are more than statistics; they represent the scale of capital deployment required to meet renewable energy targets. However, understanding the aggregate size is only the starting point. The true value of this report lies in dissecting the underlying drivers, constraints, and competitive maneuvers that will determine market share in the coming years.
Readers should note that while this overview highlights the strategic framework, specific segmentation breakdowns, detailed regional revenue figures, and proprietary competitive scoring are reserved for the full report. This approach ensures that stakeholders who require actionable intelligence for precise investment or sourcing decisions have a compelling reason to engage with the complete dataset.
Market Resilience and Growth Trajectory
The period from 2020 to 2025 established a foundation of stability despite global supply chain disruptions. The market size expanded from 5.84 billion USD to 8.31 billion USD over this historical window, reflecting a steady uptake in wind energy infrastructure. The forecast period from 2026 to 2032 anticipates a continuation of this momentum, with the market expected to breach the 10 billion USD threshold by 2028 and reach 13.61 billion USD by the end of the forecast horizon.
Several macro factors support this outlook. First, the ongoing repowering of older wind farms requires replacement towers that meet modern standards for height and durability. Second, new project approvals in key markets are driving demand for onshore installations, which remain the dominant application type within the tubular steel segment. While offshore wind presents a high-growth opportunity, the sheer volume of onshore deployments continues to anchor the market size.
However, growth is not linear. Project developers must contend with significant variability in input costs. Steel constitutes a substantial portion of tower construction expenses, and volatility in raw material pricing between 660 and 890 USD per ton observed in recent years continues to ripple through project budgets. This cost sensitivity makes accurate forecasting and strategic sourcing essential for maintaining margin integrity. Our report analyzes how these cost structures influence bidding strategies and project viability across different regions.
Structural Segments and Technical Trends
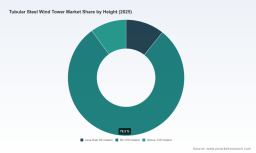
Understanding the market requires looking beyond total revenue to the technical specifications that drive demand. The industry is currently defined by a preference for mid-to-high hub heights. Towers in the 80 to 120 meters range represent a significant portion of the market value, as they offer the optimal balance between energy capture efficiency and transportation logistics. Towers below 80 meters are seeing reduced relative demand as turbines grow larger, while structures above 120 meters are gaining traction for specific high-wind sites, often requiring specialized engineering solutions.
Innovation in tower design is also reshaping the competitive landscape. Traditional tubular steel designs are being augmented by hybrid models. For instance, recent product launches have introduced hybrid steel towers that combine modular segmented steel with tubular sections to achieve higher hub heights without compromising structural integrity. These technological shifts are not merely engineering feats; they alter the supply chain requirements and open new avenues for manufacturers who can adapt their production capabilities.
The report provides a granular analysis of how these technical segments evolve over the forecast period. It examines the trade-offs between cost, logistics, and performance for different tower heights and application types. By understanding these technical drivers, stakeholders can better anticipate future demand patterns and align their production capacities accordingly.
Competitive Landscape and Concentration
The tubular steel wind tower market is characterized by a high degree of concentration. The top three players command a significant share of the market, while the top five entities further consolidate this position. This concentration implies that market dynamics are heavily influenced by the strategic moves of a few key industrial players. Our research profiles several of these critical companies, analyzing their operational footprints, product portfolios, and strategic positioning.
In North America, companies such as Arcosa Wind Towers and Broadwind Energy remain pivotal. Arcosa focuses on manufacturing and supplying tubular steel towers for onshore wind farms across the region, leveraging its location in Dallas, Texas, to serve a broad domestic market. Broadwind Energy, based in Cicero, Illinois, produces tubular steel towers and repowering adapters for turbine OEMs in the United States, positioning itself as a key partner for turbine manufacturers seeking reliable supply chain integration.
Asia Pacific presents a different competitive dynamic, with strong manufacturing bases in South Korea and China. CS Wind Corporation, headquartered in Seoul, supplies tubular steel wind towers and has secured full supply contracts for major US wind projects, highlighting the global nature of modern wind supply chains. In China, Titan Wind Energy in Suzhou and Shanghai Taisheng Wind Power Equipment Co., Ltd. are specialized manufacturers serving both onshore and offshore applications. Qingdao Tianneng Heavy Industries Co., Ltd. is also noted for its emphasis on offshore capabilities, reflecting the region's push into deeper water wind resources.
Europe remains a hub for technological innovation and high-quality manufacturing. ENERCON GmbH, based in Aurich, Germany, provides tubular steel wind towers for its own turbine platforms and hybrid designs. The company's recent introduction of a Hybrid Steel Tower demonstrates the ongoing innovation in this space, aiming to combine the benefits of modular segmentation with the strength of tubular sections for higher hub heights.
The report dives deep into the financial health, capacity expansions, and strategic partnerships of these key players. It also examines recent developments, such as the launch of a new wind tower manufacturing facility in Yanbu, Saudi Arabia, by Al Yamamah Steel Industries in late 2025. This move signals an effort to expand local supply chains in the Middle East, reducing reliance on imported components and potentially altering regional logistics costs.
Regulatory Environment and Trade Dynamics
No strategic analysis of the tubular steel wind tower market is complete without a rigorous examination of the regulatory landscape. Trade policies and anti-dumping duties have become central variables in project economics, particularly in the United States. The US International Trade Commission has recently issued determinations in five-year sunset reviews for utility-scale wind towers from Canada, Indonesia, South Korea, and Vietnam. The commission determined that revoking antidumping duty orders on these imports would likely lead to the continuation or recurrence of material injury to the domestic industry. This decision reinforces the protective trade measures that have been in place, affecting sourcing strategies for developers who might have considered these regions for cost savings.
Furthermore, the US Department of Commerce has amended final determinations on anti-dumping duties for utility-scale wind towers from Spain, setting a rate of 28.55 percent. Such specific duty rates can dramatically alter the landed cost of imported towers, making domestic or non-tariffed supply options more attractive. Additionally, a new federal tariff of 25 percent on imported steel-derivative products, including wind towers, announced in 2025, is already threatening specific projects. Reports indicate that nine wind projects in British Columbia face increased costs due to this tariff, highlighting the cross-border implications of US trade policy on neighboring markets.
These regulatory factors create a complex matrix for compliance and risk management. Companies must navigate not only the direct costs of tariffs and duties but also the potential for retaliatory measures and supply chain disruptions. Our report provides a detailed mapping of these regulatory risks, offering insights into how different regions are affected and what mitigation strategies are being employed by leading market participants. Understanding the legal and political context is as crucial as understanding the technical specifications of the towers themselves.
Why You Need the Full Report
While this overview underscores the magnitude and complexity of the tubular steel wind tower market, it only scratches the surface of the intelligence available in our full study. The market is too dynamic, and the stakes too high, to rely on high-level summaries for critical decision-making. The full report offers a depth of analysis that transforms general market awareness into actionable strategy.
Access to the complete research enables stakeholders to benchmark their performance against detailed market size data segmented by region and application. It provides the specific revenue figures and growth rates for each segment, allowing for precise target setting and resource allocation. The competitive analysis goes beyond company profiles to include market share estimates, strategic moves, and potential vulnerabilities. This level of detail is essential for identifying partnership opportunities, assessing competitive threats, and planning capacity expansions.
Tubular Steel Wind Tower Market
Moreover, the report includes a comprehensive analysis of raw material trends, supply chain risks, and regulatory updates, providing a holistic view of the operating environment. For investors, this data supports valuation models and risk assessments. For manufacturers, it informs production planning and pricing strategies. For developers, it aids in procurement negotiations and project feasibility studies.
In a market projected to reach 13.61 billion USD by 2032 with a CAGR of 7.3 percent, the difference between success and missed opportunity often lies in the granularity of the data. The full report is designed to provide that granularity. We invite you to explore the complete study to unlock the full potential of these insights and ensure your organization is equipped with the intelligence needed to thrive in the evolving wind energy landscape.
Worldwide Wind Turbine Tower Market
For detailed analysis of this topic, please visit the official page: Tubular Steel Wind Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


