



PW Consulting: Sodium Hydrosulfide Market to Hit $620M by 2032 with 4.2% CAGR

Sodium Hydrosulfide Market Strategic Outlook 2026: Navigating Volume Growth and Regulatory Friction
The global sodium hydrosulfide market is entering a pivotal phase where steady volume expansion collides with tightening environmental oversight and fluctuating input costs. For industrial strategists, procurement leaders, and corporate development teams, the 2026 operating environment demands more than backward-looking revenue tracking. It requires a clear understanding of how regional supply architectures, type-specific demand shifts, and application-side procurement behaviors will evolve across the forecast horizon. Our latest Sodium Hydrosulfide Market research publication is engineered to deliver exactly that operational clarity. Drawing on a structured base year of 2025 and a historical review spanning 2020 through 2025, the report extends its analytical lens to 2026–2032, providing decision-makers with a defensible framework for capacity planning, contract negotiations, and competitive positioning.
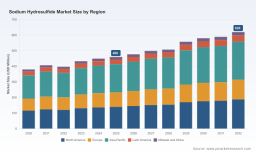
At the macro level, the market trajectory reflects measured but consistent growth. Revenue moved from 380.0 million USD in 2020 to 432.67 million USD in 2023, then continued its upward path to 449.38 million USD in 2024 and 460.0 million USD in 2025. The forecast arc projects this momentum through the end of the decade, with revenues expected to reach 476.99 million USD in 2026 and climb to approximately 620.0 million USD by 2032. This progression translates to a forecast period CAGR of 4.2 percent, a rate that signals durable demand rather than speculative surges. For executives, that growth profile carries a specific strategic implication: sodium hydrosulfide is not a niche volatile chemical, but a workhorse industrial input whose procurement and supply decisions compound over multi-year horizons. The report contextualizes these headline figures within the underlying demand engine, showing where volume is structurally accumulating and where margin exposure is intensifying.
Why 2026 Decision-Making Requires a Different Analytical Lens
The 2026 landscape is defined by a convergence of operational pressures that historical benchmarks alone cannot resolve. Sulfur-based chemical supply chains are navigating stricter transport protocols, closed-loop sulfur handling expectations, and low-emission production requirements. Environmental compliance under REACH and EPA frameworks is no longer a peripheral compliance cost; it is reshaping logistics economics, site selection logic, and supplier qualification standards. At the same time, raw material volatility remains a persistent threat to manufacturing economics. Price movements in sulfur dioxide, sodium hydroxide, and zinc—particularly for zinc-based production routes—can compress margins quickly during commodity spikes, making procurement timing and hedging strategy central to profitability.
Compounding these dynamics, market pricing signals are already showing sensitivity to broader commodity cycles. In the United States, pricing for sodium sulfide products, including sodium hydrosulfide, eased to 518 USD per metric ton in November 2025, reflecting a modest month-over-month decline and a more pronounced year-over-year pullback. While such movements can temporarily relieve procurement budgets, they also mask underlying structural risks: environmental scrutiny of sulfur dioxide emissions as a process byproduct, the generation of sulfite and thiosulfate residues in wastewater streams, and the operational hazards associated with transport and handling. These pressures are especially acute in Europe and North America, where regulatory intensity is reshaping acceptable sourcing models and pushing manufacturers to differentiate on safety, traceability, and environmental performance.
This is where the new report adds decision-grade value. Rather than presenting a flat growth curve, it breaks down the forces that will determine which companies capture share, which procurement teams secure supply resilience, and which operators navigate margin compression without sacrificing service quality. The analysis is designed for teams that must act in 2026 with incomplete visibility into the next seven years, giving them a structured way to test assumptions, prioritize investments, and align commercial strategy with evolving regulatory and operational realities.
What the Report Delivers: Operational Intelligence Over Abstract Trends
The publication is built around actionable modules that connect market structure to business decisions. It begins with a rigorous demand-and-supply framework that maps how sodium hydrosulfide flows across major industrial ecosystems and where procurement behavior is shifting. Instead of stopping at top-line projections, the report unpacks the structural drivers behind volume formation, helping readers understand which demand centers are expanding on fundamentals and which are being shaped by substitution risk, process optimization, or regional compliance costs.
A central strength of the study is its segmentation logic, which translates market complexity into operational categories that procurement, sales, and strategy teams can use directly. The analysis examines the liquid and solid forms of sodium hydrosulfide as distinct value propositions, reflecting the different handling requirements, end-user preferences, and application fit that define purchasing decisions. It also maps demand across core industrial uses, including pulp and paper processing, mining operations, leather and tanning workflows, and water treatment applications. For each segment, the report explores the operational rationale for adoption, the factors influencing specification requirements, and the procurement dynamics that will shape sourcing behavior over the forecast period. This structure allows readers to move quickly from high-level market size to the specific demand pockets most relevant to their portfolios.
Equally important, the report integrates a regulatory and operational risk overlay that many market summaries overlook. It evaluates how environmental compliance, transport constraints, and production-side emissions management are altering the economics of sodium hydrosulfide supply. Rather than treating regulation as a static barrier, the analysis frames it as a competitive variable: firms that invest early in safer handling, closed-loop sulfur systems, and lower-emission processes are building negotiating leverage and customer trust, while those that rely on legacy logistics models face rising friction. For buyers, this distinction influences supplier selection, contract structure, and total cost of ownership assessments. For producers, it shapes capital priorities and product positioning.
The forecast architecture is deliberately built for scenario use. Readers are given the analytical scaffolding to test how changes in raw material costs, regional compliance intensity, and application-side procurement timing could shift outcomes across the 2026–2032 window. This is not a single-point prediction exercise; it is a decision-support tool that helps teams prepare for multiple plausible paths, identify early warning signals, and align internal planning with market realities. The report is structured so that strategy, supply chain, and commercial teams can extract directly applicable insights without wading through disconnected data points.
Competitive Landscape: Consolidation, Differentiation, and the Race for Operational Credibility
The sodium hydrosulfide market is characterized by a moderately concentrated competitive structure, where scale, geographic reach, and application-specific expertise determine who can compete effectively across multiple end-use sectors. With a CR3 of 48.5 percent and a CR5 of 65.2 percent, the market shows meaningful concentration at the top, yet still leaves room for specialized players to win on purity, logistics reliability, and sector-focused service models. In this environment, competitive advantage is increasingly defined not just by output volume but by the ability to deliver consistent specification quality, compliant handling, and dependable supply across long procurement cycles.
Several leading suppliers anchor the market and illustrate the different routes to competitive relevance. Nouryon, based in Amsterdam, Netherlands, manufactures and supplies sodium hydrosulfide solution as a reactive sulfur chemical building block, serving mining, pulp and paper, and polymer production. Its positioning reflects the importance of integrating NaSH supply into broader chemical value chains where consistency and reactive performance matter. Solvay, headquartered in Brussels, Belgium, offers sodium hydrosulfide alongside high-grade sodium sulphide for industrial applications, including mining and chemical intermediates, emphasizing the role of multi-product portfolios in meeting diversified industrial demand. Tessenderlo Kerley, Inc., operating from Phoenix, Arizona, United States, produces and supplies sodium hydrosulfide solution with a focus on mining, the Kraft process, and leather dehairing, highlighting how application-specific expertise can anchor a supplier’s commercial footprint.
Regional specialization and product differentiation continue to shape the competitive field. Moleko, based in Australia, supplies high-purity ekoSURE Sodium Hydrosulfide solution for copper and molybdenum flotation, Kraft process operations, leather tanning, and specialty chemicals. In July 2025, Moleko officially launched a new brand identity for its high-purity sodium hydrosulfide solution, repositioning it as ekoSURE and emphasizing investments in purification technologies, traceability, and environmentally responsible production. That move is instructive: it signals a market where purity, documentation, and sustainability credentials are becoming commercial differentiators rather than optional enhancements.
In China, Shandong Aojin Chemical Technology Co., Ltd., located in Zibo City, Shandong, manufactures sodium hydrosulphide and sodium hydrosulfide for mining, paper making, leather processing, and textile production, illustrating the role of integrated regional manufacturing in serving multiple industrial sectors. Quadra Chemicals Ltd., based in Canada, supplies mining-grade sodium hydrosulfide solution for industrial and mining applications, reinforcing the importance of grade consistency and sector-focused distribution in markets where operational reliability is paramount. BOINTE ENERGY Co., Ltd., operating from Tianjin, China, functions as an active exporter and supplier of sodium hydrosulfide with logistics organized for global shipments, showing how export-oriented players compete on reach, coordination, and supply continuity. Together, these companies reflect a competitive landscape where geographic presence, product grade, application alignment, and logistics capability all influence market standing.
The report evaluates these players within a broader structural context, helping readers understand where concentration creates pricing and supply resilience dynamics, and where fragmentation leaves openings for differentiated entrants. It examines how suppliers are responding to the same operational pressures facing buyers—transport safety, emissions management, raw material exposure, and compliance burden—and how those responses are reshaping competitive advantage. For executives assessing partnerships, sourcing diversification, or market entry, this competitive mapping provides a practical foundation for evaluating who is positioned to sustain supply, who is investing in future-ready production, and where vulnerability may emerge under tighter regulatory or cost conditions.
Liquid Sodium Hydrosulfide Market
Turning Market Intelligence into 2026 Advantage
The strategic value of this research lies in its ability to connect market structure to executable decisions. For procurement teams, the report supports more informed sourcing strategies by clarifying where demand is structurally durable, where specification expectations are tightening, and where compliance and logistics risks will influence total cost of ownership. For producers and distributors, it offers a framework for prioritizing capacity, grade development, and regional positioning in a market where margin protection increasingly depends on operational discipline and differentiated service. For investors and corporate development groups, the analysis provides a grounded view of where consolidation pressures, application growth, and regulatory-driven barriers may shape future competitive dynamics.
The 2026–2032 outlook is not merely a projection exercise. It is a decision architecture for managing a chemical market that is growing at a steady pace while becoming more complex to serve. The report translates that complexity into structured insight: how the market is sized, how it is segmented, who competes and why, and which operational forces will matter most over the forecast period. By integrating historical performance, forward estimates, competitive mapping, and regulatory context into a single analytical package, the study gives teams a practical basis for aligning procurement, production, and commercial strategy with the realities of the next phase of market development.
Sodium Hydrosulfide Market
For organizations that need to move from high-level awareness to actionable intelligence, the full report provides the deeper segmentation detail, competitive benchmarking, and scenario-ready analysis necessary to support confident 2026 decision-making. The macro direction is clear; the strategic edge comes from understanding where to act, what to weigh, and how to prepare for the operational and regulatory shifts already reshaping the sodium hydrosulfide market.
For detailed analysis of this topic, please visit the official page: Sodium Hydrosulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


