



PW Consulting: Electronic Textiles Market to Hit $1,366.98M by 2032 at 19.3% CAGR

The Fabric of the Future: Why Electronic Textiles Demand Immediate Strategic Attention
The convergence of textile engineering and advanced electronics is no longer a speculative vision. It is a measurable commercial reality that is reshaping supply chains, product roadmaps, and consumer expectations across multiple industries. At PW Consulting, we have recognized that electronic textiles represent one of the most structurally transformative material categories of this decade. Our newly released Electronic Textiles Market research report is designed to help executives, product leaders, and investors navigate this complexity with clarity, precision, and actionable foresight.
This article serves as a strategic preview of the full study. It outlines the market trajectory, the operational and regulatory forces shaping development, the competitive architecture defining the space, and the specific analytical content readers will gain access to when they download the complete report. The objective is straightforward: to demonstrate why this intelligence matters for 2026 decision-making, while preserving the granular segmentation, pricing models, and operator-level benchmarking that form the core of the full publication.
A Market Compressing at an Unusual Velocity
The electronic textiles sector has transitioned from experimental prototyping to commercial scaling in a remarkably short window. Historical revenue data from 2020 through 2025 shows a consistent upward curve, with overall market size climbing from approximately 163 million USD at the start of the period to around 395 million USD by the base year. That trajectory reflects more than incremental growth; it signals a structural shift in how fabrics are being designed, manufactured, and integrated with electronic functionality. The forecast window extending through 2032 points toward a total addressable market approaching 1.37 billion USD, with a compound annual growth rate of 19.3 percent.
Worldwide Smart Medical Textiles Market
These figures are not merely headline numbers. They reflect the compounding effect of several intersecting forces: the miniaturization of electronic components, the proliferation of low-cost wireless sensor networks, and the growing demand for garments and surfaces that can monitor, communicate, regulate temperature, or deliver haptic feedback. The pace of expansion suggests that organizations delaying strategic engagement risk being structurally disadvantaged as integration standards solidify, supply chains mature, and customer expectations normalize around intelligent textiles.
What deserves particular attention is the manner in which growth is being distributed across innovation pathways. The market is not expanding uniformly. Certain product architectures and application domains are advancing faster than others, and the divergence between early commercializers and late followers is already visible in inventory positioning, partnership structures, and manufacturing readiness. Understanding which pathways are accelerating, which are plateauing, and why requires a level of granularity that only a dedicated, data-rich study can provide.
Structural Forces Reshaping the Electronic Textiles Landscape
The current market environment is defined by a tension between rapid innovation and the incomplete infrastructure required to support widespread commercial deployment. Several dynamics are particularly consequential for 2026 planning.
On the technology side, the miniaturization of electronic components and the spread of affordable smart wireless sensor networks are accelerating adoption across wearables, automotive interiors, and performance-facing smart surfaces. These enablers lower the physical and economic barriers to embedding functionality directly into fabrics. At the same time, advanced conductive yarns and specialized printing equipment remain primary bottlenecks for scalable, washable e-textile production. The gap between laboratory-grade prototypes and durable, repeatable manufacturing at commercial volumes is still a defining constraint, and companies that fail to account for it in their sourcing and product-development strategies will face consistent quality variance and margin pressure.
Regulatory and standardization activity is also entering a more mature phase. The IPC has established IPC-8921A as the primary standard for woven and knitted e-textiles integrated with conductive fibers and yarns, creating a clearer technical baseline for manufacturers and integration partners. In parallel, the Smart Textile Alliance launched an E-textile Connectivity taskforce in early 2026 to define industry connectivity standards for sustainable e-textiles. These developments are constructive, but the sector still faces a broader lack of comprehensive global standards and regulations, which continues to hinder consistent quality and safety across markets. For firms operating across regions or planning to scale internationally, navigating this fragmentation will be a critical competency.
Taken together, these forces create both urgency and optionality. Companies that act early can shape product architecture around emerging standards, secure access to constrained material inputs, and position themselves as preferred partners in ecosystems that are still forming. Those that wait will inevitably confront higher integration friction, narrower supplier choice, and more expensive compliance pathways.
The Competitive Architecture: Who Is Building the Value Chain
The electronic textiles market is not dominated by a single archetype of player. It is a multi-layered ecosystem in which material innovators, garment integrators, sensor developers, and contract manufacturers each occupy distinct positions along the value chain. Understanding this architecture is essential for evaluating partnership opportunities, acquisition targets, and competitive vulnerability.
On the materials and component side, several established and specialized firms are supplying the foundational inputs that make electronic textiles viable. Bekaert produces conductive fibers and yarns designed specifically for embedding electronics into textiles, enabling durable smart fabric solutions. Volt Smart Yarns supplies innovative conductive yarns and e-textiles for flexible, washable applications. Mitsufuji Corp and Toray Industries contribute advanced functional fibers and conductive yarns that support both durability and integration in smart garments. DuPont supplies advanced materials, silver nanowire solutions, and conductive technologies for flexible e-textiles, EMI shielding, and smart surfaces. Statex Production and Sales develops and supplies conductive and smart textile technologies for wearable electronics and industrial integration. Bally Ribbon Mills manufactures E-WEBBINGS conductive smart fabrics optimized for IoT integration in wearable and industrial applications. These material and component suppliers are often the quiet enablers of downstream product differentiation, and their capability sets frequently determine how far a downstream designer can push performance, washability, and production scalability.
A second cluster of players is focused on turning materials into finished or semi-finished intelligent products. AiQ Smart Clothing develops and commercializes AI-powered smart clothing and e-textiles with integrated sensors and connectivity for health monitoring, sports, and daily use. Hexoskin creates wearable smart shirts with embedded sensors for continuous health monitoring of heart rate, respiration, and activity. Sensoria manufactures smart socks and apparel with embedded sensors for running, training, and health analytics. EXO2 designs and produces smart fabrics with integrated electronics for health monitoring, performance tracking, and functional apparel. Xenoma creates hybrid smart textiles with embedded electronics for medical, military, and consumer uses. Interactive Wear specializes in fully integrated smart textiles for military, healthcare, and industrial applications. Ohmatex ApS focuses on printed smart textiles with conductive patterns for fashion, healthcare, and industrial uses. Sensing Tex develops e-textiles and smart fabrics with sensors for sports, healthcare, and lifestyle applications. These companies illustrate how rapidly the product frontier is expanding beyond niche fitness wear into clinical monitoring, defense, and lifestyle applications.
Performance apparel and lifestyle brands are also shaping the market through high-visibility integration and consumer-facing validation. Nike produces connected sportswear and smart textiles with embedded sensors for performance tracking and athlete feedback. Adidas offers performance sportswear and smart textiles with embedded sensors, heat regulation, and connectivity features for athletic applications. Schoeller Textil produces high-performance smart fabrics with enhanced durability and functionality for outdoor and technical applications. Textronics pioneers conductive yarns and e-textiles for athletic performance, healthcare monitoring, and embedded electronics. Their involvement signals that electronic textiles are increasingly judged not only on technical capability but also on wearability, aesthetics, and brand trust.
Thermal, haptic, and comfort-focused applications represent another distinct value-creation path. Gentherm develops heated and smart textiles using thermoelectric and conductive elements for automotive, medical, and consumer applications. Loomia develops smart fabric panels for heat, touch, haptic feedback, and wellness in apparel and automotive interiors. ThermoSoft International focuses on heated smart textiles for comfort, therapy, and functional apparel. These applications are particularly relevant where user experience, thermal management, and human-machine interaction intersect.
Finally, the manufacturing and integration layer remains critical. Jabil provides contract manufacturing and assembly for electronic components embedded in smart textiles and wearables, bridging the gap between design intent and repeatable production. The presence of capable contract manufacturers reduces the barrier for brands and startups that lack in-house assembly expertise, but it also concentrates valuable process knowledge in a smaller set of suppliers.
Recent activity underscores how quickly the ecosystem is formalizing. In March 2026, the Smart Textile Alliance launched an E-textile Connectivity taskforce to shape industry connectivity standards for sustainable e-textiles. In April 2026, Loomia released smart fabric panels for heat, touch, and haptic feedback integrated with e-textiles. Also in April 2026, IPC introduced new standards IPC-8921A and related requirements for woven and knitted electronic textiles integrated with conductive fibers. These milestones are not isolated news items; they are indicators of an industry moving from fragmented experimentation toward coordinated development. For strategists, they mark the moment when timing, alignment, and standards readiness begin to separate winners from followers.
How the Market Is Structured Across Types, Applications, and Regions
The electronic textiles market cannot be understood through a single lens. It is simultaneously a materials story, a product-design story, a use-case story, and a regional deployment story. The report maps these dimensions in detail, but a few structural observations are worth surfacing at the strategic level.
By product architecture, the market spans passive, active, and ultra categories. This classification is more than a taxonomy; it reflects different levels of embedded functionality, power requirements, integration complexity, and cost structures. The balance among these categories is shifting as designers choose between simpler sensing or conductive functions and more advanced, computation-enabled textiles. Understanding where value accrues along this spectrum, and which architectures command premium positioning, is central to product strategy.
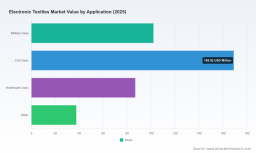
By application, the market extends across military uses, civil uses, healthcare uses, and other segments. Each application domain carries distinct procurement rhythms, performance requirements, regulatory expectations, and durability thresholds. Military deployments often prioritize robustness and mission-critical reliability. Healthcare applications emphasize measurement accuracy, biocompatibility, and clinical workflow integration. Civil uses span a broader consumer and industrial spectrum where comfort, aesthetics, and cost compete with functionality. The relative size and growth profile of these application pools determine where companies should concentrate go-to-market effort and where they can expect longer sales cycles or higher entry barriers.
Regionally, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Regional divergence matters because manufacturing footprints, supplier density, standards adoption, and end-customer preferences differ substantially. Companies evaluating expansion, sourcing, or partnership strategies need a region-by-region view that connects market size to operational reality rather than relying on aggregate numbers alone. The report provides that regional mapping without reducing it to simplistic share percentages, because strategic nuance is lost when complex markets are flattened into a single ranking.
Concentration data also offers an important strategic signal. The market currently exhibits a moderate level of concentration, with the top three players accounting for a meaningful combined share and the top five extending that footprint further. This structure suggests that while the field is still broad enough for new entrants and specialized innovators, scale, integration capability, and standards alignment are beginning to reward the most complete value-chain players. For competitors and investors alike, this is a moment when portfolio positioning and partnership strategy can meaningfully influence long-term market standing.
What the Full Report Delivers for 2026 Decision-Making
The complete PW Consulting Electronic Textiles Market study is built for practitioners who need more than narrative overview. It is structured to support concrete decisions in product planning, sourcing, partnership evaluation, market entry, and investment prioritization. The analysis integrates historical context, forward-looking projections, and operator-level detail so that readers can benchmark assumptions rather than rely on generic industry commentary.
The report begins with market sizing and trajectory analysis across the full forecast horizon, anchored in a base year of 2025 and extending through 2032. It translates historical performance into a credible growth pathway while identifying the assumptions, sensitivities, and demand drivers that shape the outlook. Rather than presenting numbers in isolation, the study places them in the context of component miniaturization, sensor proliferation, material constraints, and standardization progress, so that leadership teams can test how changes in any one factor might alter their own planning.
A major portion of the research is devoted to segmentation and segment dynamics. Readers will find structured analysis of the market by type, by application, and by region, with attention to the operational and commercial implications of each split. The objective is not to produce a static table of shares, but to explain where different architectures and use cases are gaining traction, where manufacturing or regulatory friction is slowing deployment, and how regional conditions influence both opportunity and execution risk.
Competitive intelligence is another core pillar. The report profiles the key companies shaping the market, including material suppliers, product developers, performance-apparel brands, thermal and haptic specialists, and contract manufacturers. Each profile is tied to the company’s specific offering in electronic textiles, allowing readers to assess where competitors are building capabilities, where gaps remain, and how the value chain may consolidate or reconfigure over time. This company-level detail supports benchmarking, partnership screening, and competitive positioning in a way that high-level market summaries cannot.
The study also integrates the most consequential recent developments and structural dynamics. It addresses the establishment of IPC-8921A as a primary standard for woven and knitted e-textiles integrated with conductive fibers and yarns, the launch of the Smart Textile Alliance E-textile Connectivity taskforce, and the practical implications of product launches such as Loomia’s smart fabric panels for heat, touch, and haptic feedback. These events are analyzed not as headlines but as inputs to strategic timing, compliance planning, and ecosystem alignment.
In addition, the report examines the persistent bottlenecks that shape commercial viability, including the limitations of advanced conductive yarns and specialized printing equipment for scalable, washable production, and the broader absence of comprehensive global standards and regulations for e-textiles, which continues to complicate consistent quality and safety across markets. By linking these constraints to real operating decisions, the study helps teams anticipate sourcing challenges, design-for-manufacturing requirements, and the compliance effort likely to be needed as standards mature.
Throughout, the emphasis is on actionable insight. The report is designed to help executives answer questions such as where to allocate R&D focus, which supplier relationships are likely to matter most, how different application domains compare in payback profile and execution complexity, and what a credible entry or expansion strategy should look like in a market that is growing quickly but still maturing in critical ways.
Electronic Textiles Market
Why This Intelligence Matters Now
Electronic textiles are crossing a threshold from promising technology to strategically unavoidable category. The combination of strong growth momentum, expanding application breadth, and the gradual formalization of standards is creating a window in which early, informed decisions can compound into durable advantage. Companies that treat the market as a peripheral innovation experiment risk being surprised by how quickly integration expectations, supplier dependencies, and customer requirements solidify.
At the same time, the market’s complexity demands discipline. Growth alone does not reveal where profitability will concentrate, which material inputs will become constrained, how regional conditions will shape execution, or which competitor moves will redefine competitive positions. Those questions require detailed segmentation, operator-level benchmarking, and a clear view of the forces that can accelerate or disrupt adoption.
This is precisely the gap the PW Consulting Electronic Textiles Market report is built to fill. It provides the macro trajectory, the structural analysis, the competitive mapping, and the current dynamic context that leadership teams need to make 2026 decisions with confidence. The preview above illustrates the scope and tone of the study, but the full report contains the depth, segmentation, and company-level intelligence that turn market awareness into operational advantage.
For executives, strategists, and investors ready to move beyond surface-level trends, the complete research offers a disciplined foundation for product planning, sourcing strategy, partnership selection, and market-entry design. The electronic textiles opportunity is real, but its value will be captured by those who understand it in detail. The full report is the instrument for that understanding.
For detailed analysis of this topic, please visit the official page: Electronic Textiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


