



PW Consulting: Benefits Admin Software Market Hits $200M in 2025, Forecasts 10.23% CAGR to 2032

Strategic Imperatives in the Modern Benefits Administration Software Market: A 2026 Outlook
The benefits administration software market is undergoing a structural transformation driven by regulatory complexity, workforce expectations, and the rapid infusion of artificial intelligence into core HR technology stacks. As organizations navigate post-pandemic benefits redesign, rising healthcare inflation, and evolving compliance requirements, the strategic function of benefits administration software has expanded far beyond enrollment and payroll reconciliation. It now sits at the intersection of employee experience, financial stewardship, and risk management. Our latest Benefits Administration Software Market research was commissioned to cut through the noise and provide enterprise decision-makers with a rigorous, forward-looking framework for evaluating vendor selection, technology investment, and competitive positioning through 2032.
This article previews the strategic architecture of that study. Rather than offering surface-level vendor lists or incremental trend commentary, the report delivers a disciplined market model, competitive intelligence, and operational benchmarking designed to inform capital allocation, digital transformation roadmaps, and compliance strategy. What follows is a guided introduction to the market forces, segmentation logic, competitive dynamics, and content architecture embedded in the full research package. The core quantitative estimates, granular regional and application splits, and detailed company scoring matrices are intentionally reserved for the complete deliverable, ensuring that executives who engage with the source report receive actionable, decision-grade intelligence rather than recycled summary data.
The Macro Trajectory: Why Benefits Administration Software Is Entering a New Growth Cycle
The global benefits administration software market has demonstrated durable expansion over the past half-decade, with total revenue climbing steadily as enterprises migrated from manual, spreadsheet-driven processes to integrated, cloud-enabled platforms. Looking across the historical tracking window and forward forecast horizon, the market has entered a phase of accelerated monetization tied to digital transformation mandates, compliance automation, and payroll-to-HR system consolidation. The research models a compound annual growth rate of 10.23 percent across the forecast period, reflecting sustained demand for platforms that can simultaneously manage enrollment, eligibility verification, carrier connectivity, and regulatory reporting at enterprise scale.
Several structural drivers underpin this trajectory. First, regulatory complexity continues to raise the cost of non-compliance. Employers face escalating exposure to penalties tied to minimum essential coverage, HIPAA-mandated data security controls, and state-level continuation coverage requirements. These obligations are not static; they intensify with inflation indexing and evolving enforcement expectations, creating a persistent need for software that can automate compliance logic rather than rely on manual interpretation. Second, the financial burden of administering benefits through generalized HRIS platforms has prompted organizations to evaluate dedicated benefits solutions that deliver greater workflow precision, carrier integration depth, and ROI clarity. Third, employee expectations around self-service, mobile accessibility, and personalized benefit selection have shifted administrative software from a back-office utility into a frontline retention and engagement tool.
Within the forecast timeline, market expansion is projected to accelerate in the latter years, with total revenue expected to surpass the 300 million threshold by the close of the decade and approach the 400 million mark by 2032. This growth path reflects more than incremental adoption. It signals a maturation cycle in which mid-market and large enterprise buyers are consolidating fragmented vendor relationships, upgrading legacy systems, and embedding benefits workflows into broader workforce management architectures. The strategic implication for 2026 decision-makers is clear: the window for optimizing benefits technology is narrowing, and the cost of deferred modernization is rising in both compliance risk and operational friction.
Market Segmentation Logic and Strategic Dimensions
Effective vendor evaluation and investment planning require a segmentation framework that aligns with how buyers actually purchase, deploy, and scale benefits technology. The research structures the market across multiple strategic axes, each designed to illuminate distinct purchasing behaviors, technology adoption patterns, and operational priorities.
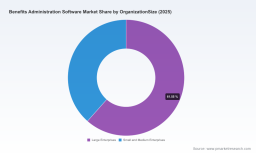
- Organizational scale continues to be a defining determinant of technology strategy. Large enterprises typically prioritize comprehensive integration, multi-carrier connectivity, and advanced compliance automation, while small and medium enterprises often seek streamlined onboarding, predictable pricing, and packaged self-service capabilities. The division of revenue between these segments reflects contrasting purchasing velocity, implementation complexity, and vendor preference.
- Deployment architecture remains a critical selection factor as buyers weigh agility against control. Cloud-based platforms dominate contemporary procurement decisions because they reduce infrastructure burden, accelerate feature updates, and enable broader user accessibility. However, on-premises and hybrid configurations retain relevance for organizations with stringent data governance requirements, legacy system dependencies, or specialized security protocols.
- Geographic distribution shapes both vendor strategy and buyer expectations. Regional dynamics influence compliance regimes, carrier ecosystems, compensation structures, and the maturity of digital benefits adoption. The research captures these variations to help organizations assess market opportunity, competitive intensity, and localization requirements across major economic zones.
Rather than presenting segmentation as a static data table, the report analyzes how these dimensions intersect. For example, it examines how cloud adoption compounds differently across organization sizes, how regional compliance burdens reshape feature prioritization, and how buyers typically sequence implementation priorities when migrating from HRIS-embedded benefits to dedicated administration platforms. This layered approach enables buyers to map their own operating profiles against broader market behavior and identify where their deployment strategy may expose them to inefficiency or competitive lag.
Competitive Dynamics and the Battle for Platform Relevance
The competitive landscape is concentrated yet diverse, with a mix of large HCM incumbents, specialized benefits administration providers, and emerging all-in-one workforce platforms competing on integration depth, compliance automation, user experience, and intelligent feature sets. The research provides detailed company profiles, capability assessments, and strategic positioning analysis to help buyers distinguish between vendors that offer genuine differentiation and those that rely primarily on brand recognition or bundled pricing.
Benefits Administration Software Market
Several established players anchor the market through broad HCM ecosystems that embed benefits administration within wider payroll, time, talent, and HR workflows. These platforms appeal to organizations seeking operational consolidation and unified data models. Their value proposition centers on end-to-end continuity, carrier integrations at scale, and compliance workflows designed to reduce manual oversight. At the same time, dedicated benefits administration specialists compete by emphasizing enrollment optimization, eligibility precision, member-facing self-service, and regulatory reporting rigor. Their advantage often lies in workflow specificity, carrier connectivity breadth, and the ability to tailor benefits experiences without forcing buyers into a full HCM replacement cycle.
A third competitive current is being shaped by platform companies that treat benefits as one module within a broader operational stack spanning IT provisioning, workforce management, and employee services. These offerings attract organizations pursuing operational simplification and unified dashboards, particularly when benefits administration must connect tightly to payroll, devices, access management, and cross-functional employee data flows. The strategic question for buyers is not whether a platform is broad or specialized, but whether its architecture aligns with the organization's implementation capacity, compliance risk profile, and long-term system consolidation plans.
The report also incorporates competitive intelligence around recent product momentum and innovation signals. For instance, the market has seen heightened activity around AI-driven personalization, mobile self-service enhancements, billing visibility improvements, and expanded carrier and partner connectivity. Recent updates from leading providers underscore a shift toward smarter administrative guidance, more transparent financial tracking, and conversational or recommendation-based tools that help employees navigate complex plan options. Separately, new market entrants and adjacent platform launches announced in early 2026 extend the competitive perimeter, particularly around AI-powered benefits administration targeting insurance agencies and healthcare operations contexts. These developments matter because they indicate where vendors are placing bets on differentiation and where buyers should expect feature escalation in the next procurement cycle.
Market concentration remains notable, with a substantial share of revenue held by a limited set of leading providers. This concentration has practical implications for negotiation leverage, integration roadmaps, and platform switching costs. Buyers must assess not only current capability but also the likelihood that a vendor will continue to invest in the specific workflows, compliance logic, and data interoperability their organization requires. The research addresses these issues through structured evaluation criteria that go beyond feature checklists and into strategic fit, scalability, and innovation cadence.
Regulatory Pressure, Cost Economics, and Operational Reality
No benefits administration technology evaluation is complete without a clear view of the regulatory and economic forces that shape both platform requirements and total cost of ownership. The research treats compliance not as a feature footnote but as a core design constraint that influences product architecture, implementation effort, and long-term administrative burden.
On the regulatory side, employers must contend with overlapping obligations that vary by organization size, workforce composition, and jurisdiction. Compliance workflows increasingly demand automated tracking for coverage adequacy, secure handling of protected health information, encryption standards, role-based access controls, and ongoing reporting for continuation coverage mandates at the state level. For applicable large employers, the financial stakes of coverage noncompliance can be substantial and are subject to inflation-indexed adjustments. These realities elevate the importance of software that embeds regulatory logic directly into enrollment, eligibility, and reconciliation processes rather than requiring manual monitoring outside the platform.
Worldwide Financial Wellness Benefits Market
On the cost side, the operational economics of benefits administration are prompting organizations to reassess how much administrative overhead is acceptable when benefits are processed through generalized HRIS environments. Dedicated benefits solutions are increasingly evaluated on their ability to reduce manual intervention, streamline carrier billing reconciliation, and improve the accuracy of deductions and eligibility determinations. The research incorporates this economic dimension by examining how buyers justify technology investment through efficiency gains, risk reduction, and improved employee experience outcomes, rather than treating software spend as an isolated administrative expense.
Together, these dynamics shape a market in which buyers are less interested in incremental feature expansion than in platforms that deliver measurable operational improvement, compliance assurance, and scalable employee engagement. The report's analysis reflects that shift, positioning benefits administration software as a strategic system rather than a tactical utility.
What the Report Delivers: A Framework for 2026 Decision-Making
The full Benefits Administration Software Market research was constructed to support concrete executive and procurement decisions. Its contents are organized to move from market structure to competitive reality to implementation planning, providing a comprehensive basis for investment strategy, vendor comparison, and digital roadmapping.
- Executive market overview and growth trajectory analysis that situates current market size within a multi-year forecast, giving leadership a calibrated view of where the market is heading and how quickly adoption is expected to evolve.
- Segmentation analysis across organization size, deployment model, and regional dynamics, designed to help buyers benchmark their own profile against market behavior and identify where their procurement priorities align with broader demand patterns.
- Competitive landscape assessment covering core providers, platform positioning, capability emphasis, and recent product developments, enabling side-by-side evaluation without relying on marketing narratives.
- Regulatory and operational context that frames compliance obligations, data security expectations, and cost-efficiency pressures as central selection criteria rather than peripheral considerations.
- Practical intelligence for vendor evaluation, including the types of workflow, integration, and automation capabilities that distinguish leading platforms in real implementation settings.
Throughout the report, data is used to support judgment rather than replace it. The analysis emphasizes where market momentum is strongest, which capabilities are becoming table stakes, and how competitive differentiation is increasingly tied to personalization, mobile usability, carrier connectivity, and AI-assisted administration. This framing helps organizations prioritize what to evaluate, what to negotiate, and what to validate during proof-of-concept or implementation planning.
Why 2026 Is a Pivotal Year for Benefits Technology Strategy
For 2026 planning cycles, benefits administration software decisions carry heightened strategic weight. The convergence of regulatory exposure, employee experience expectations, and platform consolidation economics means that organizations can no longer treat benefits technology as a static purchase. The market's growth trajectory, competitive intensity, and innovation cadence are all pointing toward a smaller number of platforms achieving outsized relevance for enterprises seeking efficiency, compliance assurance, and differentiated employee engagement.
At the same time, the abundance of vendor claims makes disciplined evaluation more important than ever. Buyers need a clear framework for separating integrated convenience from genuine benefits administration depth, for understanding where deployment architecture affects long-term cost, and for anticipating how regulatory and cost pressures will influence platform requirements over the forecast horizon. The research was designed to provide that framework.
The preview above outlines the analytical orientation, market logic, and competitive context embedded in the study. The full report expands on these themes with detailed market sizing, segmentation evaluation, vendor profiling, and forward-looking scenario analysis intended to support procurement strategy, budgeting, and enterprise technology planning. For decision-makers seeking a precise, evidence-based basis for allocating benefits technology investment in 2026 and beyond, the complete research offers the depth required to move from general awareness to confident action.
For detailed analysis of this topic, please visit the official page: Benefits Administration Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


