



PW Consulting: Glass-to-metal Seals Market to Reach $1.74B by 2032 with 4.34% CAGR

Inside the Glass-to-Metal Seals Market: A Strategic Intelligence Brief for 2026 Enterprise Decisions
The glass-to-metal seals market has entered a defining phase in 2026. After navigating a period of pronounced volatility through 2023 and 2024, the sector is now stabilizing around a clearer growth trajectory. Our latest research assessment, built on a comprehensive historical baseline spanning 2020 through 2025 and extended through a forecast window that reaches to 2032, offers decision-makers a structured view of how this critical hermetic sealing ecosystem is evolving. Rather than presenting a static snapshot, the study maps the interplay of material science, defense and aerospace procurement cycles, medical device miniaturization, and the broader push toward harsh-environment electronics. For executives evaluating capital allocation, supply chain resilience, or technology roadmaps, the report functions as a diagnostic instrument designed to separate durable growth signals from short-term market noise.
At the macro level, the market has demonstrated a compound annual growth rate of approximately 4.34 percent across the forward forecast period. This trajectory reflects a sector that is neither in a speculative boom nor in structural decline, but rather in a phase of disciplined, application-driven expansion. Revenue movements across the historical window reveal the kind of cyclical sensitivity that procurement and engineering leaders must now price into their planning. The 2020 baseline established a market size of roughly 1,254.4 million USD. Subsequent years recorded incremental gains, with 2021 reaching 1,337.89 million USD and 2022 climbing to 1,456.88 million USD. A meaningful contraction followed in 2023, when revenue pulled back to 1,420.93 million USD, before a sharp rebound in 2024 pushed the market to 1,578.11 million USD. The 2025 figure settled at 1,295.6 million USD, reflecting the kind of post-peak rationalization that commonly reshapes vendor strategies and customer buying patterns. Looking ahead, the forecast window traces a measured ascent: 1,329.88 million USD in 2026, progressing toward 1,444.75 million USD in 2027, holding near 1,442.17 million USD in 2028, then gaining momentum again to 1,530.31 million USD in 2029, 1,626.75 million USD in 2030, 1,666.82 million USD in 2031, and ultimately 1,743.89 million USD in 2032.
These numbers matter, but they are only the beginning. What separates a useful market assessment from a simple data table is the ability to translate revenue movement into operational consequences. For a VP of procurement, the historical swing between 2023 and 2024 is not merely a statistical blip; it is a reminder that glass-to-metal sealing supply Chains can tighten quickly when specific end-use sectors accelerate procurement. For a CTO evaluating next-generation packaging, the projected 2032 ceiling is less important than the intermediate inflection points that will determine when capacity expansions, glass formulation investments, or custom tooling decisions become financially justified. Our report is structured precisely around that translation challenge.
Why the 2026 Decision Window Demands This Level of Intelligence
The current year presents a distinctive set of strategic conditions. On one side, demand for hermetic glass-to-metal seals continues to be anchored by sectors where failure is not an option. Military and defense programs, aerospace platforms, and high-reliability medical devices depend on sealing solutions that can withstand thermal cycling, pressure differentials, chemical exposure, and long service lives. On the other side, the supply base is undergoing subtle but important adjustments in capability, geography, and specialization. Some manufacturers are broadening their preform and glass formulation portfolios; others are refining compression and matched seal architectures for increasingly demanding custom geometries. Meanwhile, the broader electronics and energy storage landscape is pushing seal designers to think beyond conventional configurations and toward hybrid, oxide-free, and high-durability solutions.
In that environment, a decision made without granular market visibility can create three types of risk. The first is timing risk: committing to a supplier relationship, internal capacity investment, or long-term procurement contract at a point in the cycle that does not align with actual demand momentum. The second is specification risk: over-indexing on a seal type or material class because it appears dominant in a headline figure, while missing the more nuanced fit between application requirements and seal architecture. The third is concentration risk: underestimating how fragmented or consolidated the competitive field truly is, and therefore misreading the bargaining power available to buyers or the vulnerability of incumbents. Our research is designed to reduce all three.
The report's forecast framework is deliberately built to support near-term execution while preserving long-range optionality. By anchoring the analysis to a 2025 base year and running the outlook through 2032, the study enables readers to test multiple strategic scenarios. A component manufacturer can examine how early-cycle demand in 2026 and 2027 might affect tooling schedules and glass preform inventory. A systems integrator can assess whether anticipated revenue progression through the end of the decade justifies qualification investments in a new seal material or a second-source supplier. A strategic planner can use the trajectory to distinguish between temporary price relief and a genuine shift in market structure. The goal is not to provide a single predicted path, but to make the range of plausible paths explicit and operationally actionable.
Glass-to-Metal Connectors Market
What the Report Delivers: Operational Content, Not Just Aggregates
A high-quality market study should function as a working document for cross-functional teams. Our glass-to-metal seals research is organized to support that expectation. It combines macro revenue tracking with the kind of structural decomposition that engineering, sourcing, and strategy groups need when they translate market conditions into commercial choices.
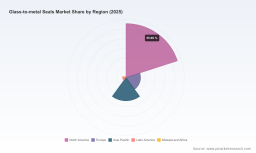
At the core of the report is a detailed segmentation architecture. The analysis breaks the market down by type, by application, and by region, allowing readers to see where demand is concentrated and where it is emerging. This decomposition is essential because revenue aggregates can conceal very different operational realities. A market that appears stable in total can still contain a segment that is contracting while another is accelerating, and those internal shifts often determine which suppliers thrive and which lose relevance. The report treats segmentation not as a decorative breakdown, but as the lens through which buyers can evaluate specification fit, supplier breadth, and regional sourcing logic.
Just as important, the study examines the boundaries of each segment. In practice, many sealing decisions are not made by broad category alone. They are driven by specific operating conditions: temperature ranges, pressure environments, electrical requirements, chemical exposure, miniaturization constraints, and qualification cycles. The report maps these application-dependent requirements to the relevant seal typologies and material considerations, giving readers a clearer sense of where matched seals, compression seals, and other configurations are typically positioned. That mapping is a practical aid for teams comparing vendor offerings or evaluating whether an existing supply base can support a next-generation design.
The research also includes forward-looking commentary on market dynamics that are likely to shape procurement and production decisions through the forecast period. Rather than relying on generic speculation, the analysis ties observed revenue behavior to underlying drivers such as program timing in defense and aerospace, the scaling of medical device platforms, and the broader adoption of harsh-environment electronics. By connecting the numbers to the conditions that generate them, the report helps organizations avoid the common mistake of interpreting a single year's revenue figure as a permanent signal.
- Detailed segmentation by type, application, and region, with enough granularity to support specification and sourcing decisions
- Historical revenue tracking from 2020 through 2025, enabling cycle-aware planning rather than point-in-time assumptions
- A forecast trajectory through 2032 that supports scenario modeling for capacity, qualification, and supplier strategy
- Competitive profiling of the leading participants shaping hermetic sealing capability across multiple end markets
- Practical interpretation of market concentration and what it implies for buyer leverage, supplier resilience, and entry dynamics
Competitive Landscape: Who Shapes the Market and How
The glass-to-metal seals market is characterized by a blend of established multinational players, specialized U.S. manufacturers, and focused European and Italian producers, each with distinct strengths in materials, process control, and application know-how. Our competitive analysis evaluates the companies that materially influence pricing, capability benchmarks, and supply availability. The study does not simply list participants; it assesses the strategic posture of each, including their positioning across seal types, their depth in critical applications, and the extent to which they control the upstream components of the value chain.
SCHOTT AG remains a central reference point in the global landscape. Headquartered in Mainz, Germany, the company is recognized as a world leader in hermetic glass-to-metal seals, with an unusually complete internal footprint that spans in-house glass formulation, preform production, and full process control. That breadth is strategically significant because it allows tighter integration across matched and compression seal architectures for electronic packaging, medical implants, aerospace, and high-temperature applications. For buyers, the relevance of a fully integrated supplier is not just quality assurance; it is the ability to respond to demanding custom requirements without depending on a fragmented chain of external material and component sources.
Electronic Products Industries, based in Newburyport, Massachusetts, represents a more specialized but equally important profile. The company focuses on custom glass-to-metal hermetic seals and TO headers for microelectronic packages, supporting both compression and matched seals across sensors, batteries, and harsh-environment electronics. Its value proposition is rooted in tailored packaging solutions rather than broad commodity supply, which makes it particularly relevant for programs where header and seal design directly affect reliability and form factor.
Concept Group LLC, operating from Florida, illustrates another distinct niche. The company manufactures oxide-free hermetic glass-to-metal compression seals using stainless steel and titanium, targeting high-temperature and high-pressure feedthroughs and connectors. In applications where material compatibility and long-term integrity under stress are decisive, this kind of specialization can become a differentiator that is not captured by headline revenue figures alone.
Elan Technology, headquartered in New York, contributes a different layer of market capability. The company supplies glass preforms and composite materials, including ceramic glass formulations such as Elan 46, for matched and compression hermetic seals. Its emphasis on high chemical durability and custom geometries underscores an important point: in many sealing challenges, the material and preform stage is not a commodity input but a strategic variable that determines whether the final assembly can meet the required specification.
Other firms extend the competitive field into targeted application areas and specialized production approaches. Hermetic Seal Technology, in Cincinnati, Ohio, produces custom hermetic glass-to-metal seals and feedthroughs for lithium batteries, aerospace, military, and oil exploration applications, aligning its capabilities with sectors where environmental severity and energy storage demands intersect. Legacy Technologies LLC, based in Mission, Kansas, specializes in precision quartz crystal and hermetic glass-to-metal seals for aerospace, medical, automotive, and sensor use, highlighting the connection between frequency-critical components and sealing precision. Dietze Group, in Switzerland, develops and manufactures glass-ceramic-to-metal feedthroughs with copper conductors and stainless-steel housings for interconnection solutions, reflecting a structural focus on reliable interfaces in complex assemblies.
The field also includes players whose relevance lies in specialty glass formulation and high-reliability execution. STC Material Solutions, operating from California, formulates and produces specialty glass for matched and compression seals, including challenging custom applications where standard material libraries are insufficient. Sintermetalglass, a long-established producer based in Opera, Italy, is known for high-quality hermetic compression glass-to-metal seals with a strong emphasis on reliability, while progressively expanding into advanced lines. SGA Technologies, located in Uttlesford, United Kingdom, is recognized for high-reliability glass-to-metal seals serving satellite communications, medical, and harsh-environment systems, reinforcing the importance of qualification-intensive markets in shaping supply capability.
Taken together, these companies illustrate a market that is diversified in capability but not uniformly concentrated. The report quantifies that structural reality, noting that the top three firms account for approximately 25.0 percent of market revenue, while the top five reach roughly 35.0 percent. Those concentration levels carry practical implications. For buyers, they indicate meaningful but not overwhelming supplier consolidation, which shapes negotiation strategy, qualification risk, and the value of maintaining alternative sources. For suppliers, they highlight the distance between being a recognized specialist and being a market-defining scale player. The analysis unpacks these dynamics without reducing them to simplistic rankings, because in a market driven by reliability and custom engineering, scale is only one dimension of competitive advantage.
Reading the Numbers Strategically: What the Report Reveals Without Giving Everything Away
One of the intentional design choices behind this study is to demonstrate analytic depth while preserving the full decision-grade detail for the complete report. Readers of this overview will see enough to evaluate the research's relevance and to understand the strategic questions it answers. They will also see why the complete dataset, regional breakdowns, application-level splits, and supplier-level detail matter when a company moves from general market awareness to an actual sourcing, investment, or expansion decision.
Glass-to-metal Seals Market
This approach reflects a realistic view of how enterprise intelligence is used. A C-suite audience may need the narrative logic and the strategic implications first. A sourcing team may need the segmentation logic and supplier profiles to assess alternative sources. An R&D group may need the material, preform, and seal-type framing to determine whether current internal capabilities align with anticipated application demands. By presenting the scaffold of the analysis here and reserving the full operational detail for the complete report, we make it possible for different functions to recognize the specific value that the study can deliver to them.
The report's treatment of the competitive and demand environment is particularly important at a moment when several long-cycle industries are revising their expectations for durability, miniaturization, and environmental resistance. Hermetic glass-to-metal seals sit at the intersection of those expectations. They are often invisible in the final product, yet they frequently determine whether the product can survive the conditions it was designed for. That dependence makes the market less sensitive to short-lived consumer trends and more sensitive to engineering requirements, qualification cycles, and program-level procurement behavior. The report reflects that reality by emphasizing structural drivers over speculative hype.
How to Use This Research in a 2026 Planning Cycle
The most effective use of this study is to embed it in a multi-step decision process rather than treating it as a one-time reference document. Early in the planning cycle, executives can use the forecast trajectory and historical behavior to stress-test assumptions about near-term demand and medium-term growth. Mid-cycle, engineering and sourcing teams can use the segmentation and competitive content to evaluate supplier fit, second-source options, and specification alignment. Later in the cycle, strategy groups can use the concentration data and capability profiles to assess whether the market structure supports current procurement policies or whether a change in sourcing posture is warranted.
The report is also designed to support conversations across functions. A market assessment that can be read by procurement, engineering, finance, and strategy without losing analytic rigor is more likely to produce aligned decisions. Accordingly, the study avoids unnecessary jargon while preserving technical accuracy. It translates revenue movements into operational context, and it frames competitive dynamics in terms of capability, reliability, and strategic positioning rather than simple market share rhetoric.
Access the Full Intelligence
This overview provides the strategic context and analytic framing that underpin the complete study. It is intended to show why the research is relevant to 2026 decision-making and how it connects market behavior to operational consequences. The full report extends this foundation with the detailed segmentation values, regional and application-level breakdowns, and the complete competitive profiles needed to convert insight into action. For teams that are preparing sourcing strategies, qualification roadmaps, capacity plans, or investment cases, that additional depth is where the practical advantage lies.
The glass-to-metal seals market is moving through a period in which disciplined analysis matters more than ever. Historical volatility, application-specific demand, and a competitive field defined by both scale and specialization all point to the same conclusion: enterprises that rely on broad generalizations will miss the nuances that determine sourcing resilience and technical fit. Our research is built to close that gap. The complete version is available through our market research portal, where decision-makers can access the full dataset, the detailed segmentation, and the supplier analyses that support the scenarios discussed here.
For detailed analysis of this topic, please visit the official page: Glass-to-metal Seals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


