



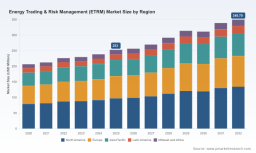
PW Consulting ETRM Market to Hit $349.79M by 2032, Growing at 4.8% CAGR from 2026-2032

Navigating the 2026 Energy Trading and Risk Management Landscape: Strategic Imperatives for Enterprise Leaders
The global energy markets are undergoing a structural transformation defined by regulatory complexity, accelerated digital adoption, and an unrelenting demand for real-time risk intelligence. As organizations transition from legacy spreadsheet-based workflows to enterprise-grade Energy Trading and Risk Management (ETRM) ecosystems, the strategic stakes for technology investment have never been higher. Our latest market intelligence study on the ETRM sector provides a rigorous, forward-looking blueprint for executives who must align technology strategy with operational resilience, compliance obligations, and commercial growth. Drawing on historical performance from 2020 through 2025 and extending our forecast horizon to 2032, this research translates macroeconomic signals into actionable decision frameworks for procurement leaders, risk officers, and enterprise architects.
The Post-2025 Market Arc: Scale, Momentum, and Structural Shifts
The commercial trajectory of the ETRM market through the mid-2020s confirms a sustained expansion cycle that is reshaping procurement priorities across commodity trading houses, utilities, financial institutions, and diversified energy portfolios. Historical revenue performance between 2020 and 2025 reflects the compounding effect of compliance-driven modernization, the migration to cloud-native architectures, and the operational necessity of consolidating fragmented trade lifecycles into unified risk platforms. The market crossed a critical inflection point as adoption rates accelerated sharply, driven by both regulatory pressure and the tangible return on investment that centralized analytics deliver for position management, margin optimization, and counterparty exposure assessment.
Looking toward the forecast period of 2026 to 2032, the expansion trajectory remains firmly positive, anchored by a compound annual growth rate that underscores durable demand even as broader macroeconomic conditions fluctuate. The forward revenue envelope indicates a clear upward path, with the total market size projected to scale meaningfully over the next several years. For enterprise buyers, this growth environment carries two strategic implications. First, it signals that ETRM investments will remain central to competitive differentiation, particularly for organizations managing complex physical and financial commodity portfolios. Second, it highlights that procurement timelines and platform selection windows are compressing, as vendors release more sophisticated analytics, automation features, and integration capabilities at a faster cadence. Decision-makers who delay platform evaluation or remain tethered to legacy, on-premise configurations risk falling behind peers who are standardizing on modern workflows capable of supporting real-time risk calculation, automated compliance reporting, and multi-commodity visibility.
Importantly, the growth dynamic is not uniform across every operational segment or geography. While the overall revenue trend is robust, procurement teams must interpret the broader figures in the context of their own portfolio complexity, trade volumes, and regional compliance obligations. The market expansion reflects a convergence of multiple underlying drivers, including sustained hedging activity, increasing volumes in renewable and transition-fuel trading, and the modernization imperative triggered by years of fragmented system landscapes. Understanding how these drivers interact requires deeper segmentation intelligence that goes beyond headline totals and examines where demand intensity is concentrated, which asset classes are generating the fastest workflow transformation, and how vendor capabilities are evolving to capture new use cases.
Sector Dynamics Redefining Platform Requirements
The modernization imperative in ETRM adoption has moved rapidly from a best-practice discussion to an operational baseline. During the recent reporting period, the proportion of organizations actively deploying or modernizing ETRM and CTRM systems climbed dramatically, signaling that automation, transparency, and integrated analytics are no longer optional enhancements. This acceleration is being reinforced by a dense regulatory environment in which firms must continuously satisfy obligations under frameworks such as EMIR for derivatives reporting, MiFID II market conduct requirements, REMIT transparency mandates, and emerging sustainability directives. In practice, these obligations affect every stage of the trade lifecycle, from initial capture and confirmation to settlement, risk aggregation, and auditable emissions or origin tracking. Platforms that cannot deliver automated compliance workflows, traceable audit trails, and configurable reporting structures quickly become liabilities rather than enablers.
Energy Trading & Risk Management (ETRM) Market
At the same time, the compliance landscape is expanding beyond traditional market supervision. Evolving ESG and carbon reporting mandates are placing new responsibilities on trading and risk operations, requiring systems to support emissions calculations, carbon intensity attribution, and verifiable documentation for sustainability disclosures. The integration of these requirements into daily trading and risk workflows is driving demand for platforms that can unify financial risk management with environmental and operational data without sacrificing speed or accuracy. As firms face stricter position reporting expectations in Europe and derivatives regulation in North America, the ability to compute risk metrics, exposure concentrations, and margin implications in near real time has become a critical differentiator. ETRM solutions that support these capabilities are increasingly viewed as foundational infrastructure rather than standalone trading tools.
A parallel shift is occurring in the deployment architecture itself. Cloud-native ETRM platforms are enabling organizations to scale compute capacity on demand, lower the capital expenditure burden associated with legacy hardware, and accelerate access to advanced analytics for position monitoring and value-at-risk calculations. The move toward cloud delivery is also reshaping vendor roadmaps, as providers release managed cloud offerings, expand integration flexibility, and improve user workflows to reduce operational friction. Recent product developments illustrate the pace of this evolution: vendors are introducing AI-assisted trade capture modules that reduce manual input errors, updating risk visualization dashboards for faster decision-making, and releasing new platform versions optimized for evolving liquid hydrocarbon and renewable fuel markets. Some providers have also secured growth capital to fund further expansion of cloud-based capabilities, while others have established partnerships to deliver their ETRM solutions as fully managed cloud services. These developments collectively indicate that the competitive frontier is moving from basic trade recording toward intelligent, continuously updated operating environments.
Competitive Landscape: Ecosystem Architecture and Strategic Positioning
The ETRM vendor landscape is characterized by a high degree of concentration at the top tiers, with a small group of major providers accounting for a substantial share of total market revenue. This concentration reflects both the scale required to sustain comprehensive trade lifecycle coverage and the specialized expertise needed to serve complex energy and commodity workflows. Nonetheless, the market remains structurally diverse, encompassing dedicated ETRM specialists, broader enterprise software players, and service-led organizations that offer managed platforms or consulting-intensive implementations. For procurement leaders, the strategic challenge is not simply comparing feature lists but evaluating how each vendor aligns with the operational, regulatory, and integration requirements of a particular portfolio.
At one end of the spectrum are platforms focused deeply on end-to-end energy trading, risk management, and settlement across physical and financial commodities. These solutions emphasize full lifecycle support, portfolio analytics, and multi-commodity operations, often serving organizations with sophisticated trading desks and substantial risk aggregation requirements. Other providers concentrate on commodity trading, risk analysis, and portfolio management with flexible configuration for different asset classes, while additional vendors specialize in enterprise risk management for energy and commodities with strong emphasis on compliance workflows and regulatory reporting. On the enterprise software side, large platform vendors extend their broader ERP and analytics ecosystems by offering ETRM modules that integrate trading, risk, and compliance activity into unified corporate systems. This provides a distinct value proposition for organizations seeking tighter alignment between trading operations and back-office or corporate finance processes.
A notable competitive trend is the rise of cloud-native entrants and the accelerated modernization of established platforms. Several providers are positioning their offerings around real-time risk and trading capabilities, cloud-first deployment models, and rapid scalability. Others continue to strengthen core strengths in electronic trading, logistics management, bid-to-bill operations, scheduling, and wholesale energy lifecycle management. Regional specialization also remains relevant, with some platforms optimized for multi-commodity trading and risk in specific international markets. Service-oriented participants complement the software ecosystem by delivering implementation, integration, and managed operations support, enabling firms to accelerate modernization without assuming all implementation risk internally.
Recent product and commercial moves underscore how this competitive field is evolving in practice. Vendors are introducing AI-assisted trade capture to reduce error rates and improve operational speed, releasing updated versions calibrated for shifting hydrocarbon and renewable fuel dynamics, and rolling out enhanced risk visualization and cloud deployment options to improve analytics performance and user workflows. Partnerships aimed at delivering fully managed cloud services, alongside funding rounds that expand cloud-based platform development, indicate a strategic race to combine regulatory-grade functionality with the speed, flexibility, and total cost of ownership advantages that modern deployment models can provide. For buyers, these developments create both opportunity and complexity: the expanding feature frontier can materially improve risk oversight and compliance readiness, but it also demands disciplined evaluation of integration complexity, vendor stability, and long-term roadmap alignment.
Evaluating this landscape effectively requires multi-dimensional assessment criteria. Procurement teams should weigh trade lifecycle coverage against the specific commodities and markets they operate in, examine the depth and speed of risk analytics and compliance automation, and assess the flexibility of deployment and integration paths. Equally important is the organizational fit: some firms benefit from highly configurable specialist platforms, while others gain more from integrated enterprise modules or managed service arrangements that reduce internal delivery burden. The concentrated nature of the top-tier market does not eliminate choice; rather, it raises the importance of understanding which provider can support the firm's regulatory footprint, portfolio complexity, and transformation timeline with the least operational friction.
Translating Intelligence into 2026 Decision Architecture
For enterprise leaders planning ETRM investments in 2026, the most valuable insights are not abstract market totals but the operational implications embedded within them. The current environment rewards a structured decision architecture that connects platform selection to measurable business outcomes: faster exposure visibility, reduced compliance leakage, improved trade workflow efficiency, and better alignment between trading strategy and risk appetite. Organizations that approach procurement as a strategic capability upgrade rather than a software replacement exercise are better positioned to capture the value of modern platforms. This means defining clear evaluation criteria around trade capture accuracy, risk calculation latency, reporting automation, integration breadth, and operational support model, then testing those criteria against realistic usage scenarios rather than scripted demonstrations.
Procurement teams should also pressure-test the total cost and risk profile of each option. Cloud-native offerings can reduce upfront capital requirements and improve scalability, but they require careful assessment of data governance, migration effort, and ongoing service economics. Enterprise-integrated modules can simplify broader system alignment, but they may require trade-offs in commodity-specific depth. Specialist platforms can deliver advanced functionality for targeted use cases, but they may demand more extensive integration work with ERP, scheduling, logistics, or settlement systems. The right answer depends on portfolio composition, regulatory exposure, internal capability, and the pace at which the organization expects its trading and risk operations to evolve. What is consistent across all scenarios is that delaying evaluation tends to increase future retrofit costs, especially as vendors continue to raise the bar on automation, analytics, and regulatory readiness.
Our full market study goes further than these directional insights by providing the segmentation depth, vendor positioning detail, and quantitative forecasts needed to support formal sourcing decisions, budget planning, and risk investment prioritization. The report examines regional revenue distributions, type-based market structures, and application-level demand patterns that reveal where procurement pressure is most intense and which workflows are driving the fastest transformation. It also maps competitive dynamics more precisely, giving buyers a framework to compare platform families, assess recent product movements, and anticipate where vendor roadmaps are likely to converge or diverge. This level of detail is essential for organizations that must justify investment, sequence modernization phases, and select technology partners with confidence.
Worldwide Electricity Trading Platform Market
Accessing the Complete Strategic Intelligence
The energy trading and risk management sector is moving quickly, and the difference between reactive technology spending and deliberate strategic investment is widening. Organizations that build their 2026 decisions on rigorous market intelligence will be better equipped to balance compliance obligations, operational efficiency, and competitive agility. The complete study provides the segmentation data, forecast trajectories, competitive profiles, and industry dynamics required to move from high-level awareness to executable strategy. To review the full quantitative findings, vendor comparisons, and segmentation breakdowns that underpin this analysis, access the complete report and secure the intelligence your team needs to make informed ETRM investment decisions in the year ahead.
For detailed analysis of this topic, please visit the official page: Energy Trading & Risk Management (ETRM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


