



PW Consulting: Furniture Hardware Market Hits $195M in 2025, 3.5% CAGR to 2032

Navigating the Next Wave: Strategic Intelligence for the Global Furniture Hardware Market 2026–2032
The global furniture hardware market stands at a critical inflection point. As manufacturing ecosystems recalibrate and consumer expectations evolve, the components that quietly enable furniture functionality are becoming strategic differentiators rather than commodity inputs. For executives, procurement leaders, and product development teams operating in 2026, understanding where this market is heading is not a matter of curiosity—it is a prerequisite for resilient supply chain design, portfolio positioning, and capital allocation. The newly released Furniture Hardware Market research study delivers precisely that clarity, translating multi-year historical performance, forward-looking projections, and granular competitive intelligence into an actionable decision framework.
This article serves as a strategic preview of the full report. It outlines the macro trajectory, highlights the structural forces reshaping supply and demand, maps the competitive architecture, and details the operational contents that make this study a practical tool for 2026 planning cycles. What follows is designed to demonstrate the analytical rigor and corporate relevance embedded in the research—while deliberately reserving the exact segment breakdowns, revenue figures, and regional allocations for the complete publication. To secure the full dataset and execute targeted planning, stakeholders are encouraged to access the source portal directly.
Market Trajectory and the Case for Forward-Looking Intelligence
Over the past half-decade, the furniture hardware sector has demonstrated steady expansion, recovering from minor cyclical adjustments and building momentum through sustained demand for upgraded cabinetry, kitchen systems, and commercial furnishings. Historical tracking from 2020 through 2025 reveals a consistent upward arc, with market valuation rising into the range of 195 million USD by the base year. This trajectory sets the foundation for a forecast period extending to 2032, during which the market is projected to continue its measured expansion at a compound annual growth rate of 3.5 percent.
For strategic planners, these numbers are more than a historical recap—they signal durability. The projected valuation progression through 2032 reflects both volume retention in mature markets and incremental growth in regions undergoing densification, renovation cycles, and modernization of commercial interiors. Importantly, the forecast horizon captures the compounding effects of product innovation, regulatory alignment, and shifting procurement preferences. Because hardware is integrated early in the furniture design and sourcing lifecycle, market-side intelligence with a multi-year view gives manufacturers, distributors, and component specifiers the foresight needed to align production capacity, pricing strategy, and SKU rationalization before demand signals become visible at the retail or project level.
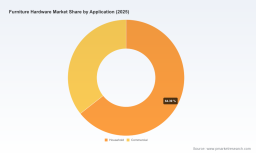
The report’s full publication preserves detailed regional and application-level allocations, enabling readers to identify where growth is most concentrated and which end-use environments are creating the strongest pull for specific hardware categories. Those precise figures are essential for scenario modeling and are therefore reserved within the complete study, ensuring that decision-makers can calibrate their strategic assumptions against verified baselines rather than approximations.
Structural Forces Redefining the Competitive Landscape
Behind the headline growth numbers lie several operational and structural dynamics that are actively reshaping how hardware is designed, manufactured, and specified. A dominant material reality continues to anchor the sector: steel remains the primary raw material for drawer slides, hinges, and runners, with supply trends holding stable amid broad-based manufacturing demand. This material continuity provides a predictable cost backbone, but it also means that sourcing strategy, supplier diversification, and quality assurance now matter more than ever in differentiating margins and protecting delivery reliability.
Simultaneously, regulatory frameworks are tightening the floor for acceptable performance. ISO 9001 certification has become a baseline requirement for manufacturers seeking to operate across international markets, reinforcing the need for documented quality management and consistent production controls. Complementing this, BIFMA and ANSI standards govern safety and performance expectations for furniture fittings, including hinges and slides intended for consumer use. Compliance is no longer a peripheral consideration; it is a market-access condition that influences supplier selection, export readiness, and risk exposure. The study details how these standards intersect with supply chain qualification processes and what they mean for long-term vendor relationships.
On the demand side, a clear innovation vector is pulling the market toward enhanced user experience and sustainability. Soft-close mechanisms and a growing preference for sustainable materials are driving product development, reinforced by energy-efficiency mandates and broader environmental expectations in both household and commercial settings. This shift is not cosmetic. It alters design requirements, testing protocols, and the value proposition that leading suppliers must articulate to design teams and end customers alike.
Cost pressures are also part of the equation. Skilled labor shortages in precision manufacturing for furniture hardware components are contributing to production cost increases in key regions. As tolerances tighten and functional complexity rises, the labor dimension of manufacturing becomes a strategic variable, influencing where capacity is expanded, how automation is prioritized, and which supplier profiles remain competitive over time. These dynamics are explored in depth within the report’s market dynamics section, where qualitative drivers are linked to the quantitative forecast to show how structural pressures translate into market outcomes.
Competitive Architecture and Strategic Positioning
The furniture hardware market is characterized by a concentrated yet diverse competitive field. Top-tier players hold a meaningful share of consolidated revenue, with the three largest firms accounting for approximately 54 percent of the market and the five largest reaching around 58 percent. This level of concentration indicates that scale, brand trust, and comprehensive product ecosystems play a decisive role in capturing specification share. At the same time, a broader set of specialized manufacturers competes on innovation, regional reach, and niche system solutions, making the landscape dynamic rather than static.
Among the leading organizations, several European and Italian manufacturers anchor the premium and mid-premium segments with broad portfolios spanning drawer runners, hinges, lift systems, sliding mechanisms, and interior accessories. Austria-based Blum stands out as a leading manufacturer of drawer runners, hinges, lift systems, and box systems for furniture, while Germany’s Hettich covers hinges, drawer systems, runner systems, sliding door systems, and folding door systems. Germany’s Häfele extends beyond fittings into architectural hardware, electronic locking systems, and kitchen appliances, reflecting a broader systems orientation. Italy’s Salice focuses on hinges, runners, and sliding systems; GRASS produces movement systems including hinges, drawer slides, flaps, and interior accessories; and FGV delivers hinges, drawer slides, drawer systems, hanging brackets, and sliding systems. Kesseböhmer contributes kitchen interior fittings, steel processing, and storage solutions, and Vauth-Sagel specializes in storage solutions, base cabinets, corner solutions, and pull-out systems. Italy’s Titus rounds out the European contingent with connectors, dowels, drawer and cabinet hardware, dampers, and levelers.
Furniture Hardware Market
Cabinet Hardware Market
On the Asia side, Taiwan’s King Slide manufactures drawer slides, undermount slides, ball bearing slides, and furniture fittings, while China hosts a strengthening cohort of producers. DTC is a leading manufacturer of hinges, drawer slides, drawer systems, and lifting systems; Taiming is recognized as a world-leading manufacturer of drawer slides and innovative opening and closing mechanisms; Jusen operates as an active manufacturer of furniture hardware components and systems; and Hi-Gold produces home hardware including kitchen and wardrobe fittings. ADAMS serves as an active provider of furniture fittings and hardware solutions. This geographic diversification underscores the market’s dual reliance on established European engineering heritage and expanding Asian manufacturing capacity.
Recent corporate and product developments make the competitive dynamics even more tangible. In January 2024, Hettich completed a merger with FGV, expanding its product portfolio in furniture fittings and strengthening its system-level offering. In May 2025, King Slide opened a new manufacturing facility in Houston, Texas to support U.S. market growth—an indicator of how critical regional capacity has become for serving near-term demand and reducing logistical friction. At the trade level, Vauth-Sagel introduced new VS ENVI waste bin systems and VS COR corner solutions at the interzum fair in November 2025, highlighting how product launches are increasingly focused on space optimization, functionality, and integrated storage.
Looking ahead, the industry calendar reinforces the pace of innovation diffusion. The 11th–12th March 2026 edition of the Furniture Component Expo in Telford, UK, showcased the latest furniture hardware innovations, while the 8th–11th September 2026 Furniture China Expo in Shanghai is set to feature new furniture hardware models and systems. These gatherings do more than display products; they reveal where specification trends are moving, which functional promises are gaining traction, and how quickly new mechanisms are reaching commercial readiness. The report integrates these corporate milestones and event signals into a competitive assessment that goes beyond headcount and revenue, examining portfolio breadth, regional footprint, and the strategic logic behind recent expansion and consolidation moves.
What the Full Report Delivers: A Practical Toolkit for 2026 Decisions
This study was constructed with execution in mind. Rather than stopping at high-level projections, it assembles a modular set of analyses that can be applied directly to sourcing strategy, product planning, market entry evaluation, and competitive benchmarking. The full report includes:
- A comprehensive market overview that frames current size, historical behavior, and forecast direction within a single, decision-ready narrative.
- Segmentation analyses that break down the market by type, application, and region, allowing readers to isolate the categories and geographies most relevant to their operations.
- Historical and forecast data tables covering the 2020–2032 window, providing a consistent basis for modeling volume assumptions, pricing scenarios, and capacity planning.
- A detailed competitive landscape section profiling the key companies, their headquarters, product focus, and strategic posture, along with an assessment of market concentration and positioning logic.
- Recent developments tracking covering product launches, mergers and acquisitions, facility expansions, and major trade events, so that planners can connect external movements to internal decision timelines.
- A market dynamics chapter that examines raw material conditions, regulatory requirements, macro trends, and labor cost pressures, linking these forces to procurement and production implications.
- Forward-looking insight on innovation directions, sustainability expectations, and specification trends, helping teams anticipate near-term shifts in demand before they become widespread.
Why This Research Matters for 2026 Corporate Strategy
The strategic value of this study lies in its ability to connect high-level market behavior with the operational realities that executives face on a daily basis. For procurement and supply chain leaders, the combination of material stability, regulatory requirements, and labor-driven cost pressure calls for a deliberate approach to supplier qualification, dual sourcing, and quality assurance. For product development teams, the momentum behind soft-close solutions, sustainable materials, and integrated storage mechanisms indicates where differentiation is most likely to pay off in both household and commercial projects. For executive planners and investors, the forecast trajectory and concentration profile provide a structured basis for evaluating growth potential, competitive vulnerability, and the timing of capacity or portfolio investments.
Equally important, the report is designed to support scenario-based thinking. Because the forecast extends through 2032 and is anchored in a detailed historical record, readers can test assumptions about regional expansion, application mix, and category substitution against a consistent analytical baseline. That capability matters in 2026, when supply chain restructuring, specification changes, and competitive realignment can materially affect margins and market share within a single planning cycle. The full report preserves the exact regional and application-level allocations, type-specific revenue context, and concentration details that make such scenario work precise rather than speculative.
Conclusion: Turn Market Intelligence into Action
The Furniture Hardware Market research study offers more than a snapshot of current conditions. It provides a structured, forward-looking view of a sector defined by stable material foundations, rising performance expectations, concentrated yet competitive supplier dynamics, and a forecast path that supports multi-year planning. For organizations operating in 2026, the difference between reactive sourcing and strategic advantage often comes down to access to the right level of detail at the right time.
The preview above highlights the scope, methodology, and strategic relevance of the study. To leverage the full set of quantitative tables, segment splits, regional allocations, and company-level insight, readers are invited to access the complete report through the source webpage. There, the data is presented in a format built for direct integration into budgeting models, sourcing reviews, and strategic planning sessions—enabling teams to move from awareness to action with confidence.
For detailed analysis of this topic, please visit the official page: Furniture Hardware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


