



PW Consulting Forecasts Power Generation Equipment Market to Hit $237.47B by 2032 with 5.1% CAGR

Navigating the Power Generation Equipment Market: Strategic Imperatives for 2026 and Beyond
The global power generation equipment sector is undergoing a structural recalibration unlike any seen in the past decade. As energy demand accelerates and policy frameworks shift, organizations operating across the power value chain must look beyond short-term pricing signals and evaluate the deeper architectural changes reshaping supply, demand, and competitive positioning. At PW Consulting, our latest Power Generation Equipment Market study has been engineered specifically to equip executive teams, procurement leaders, and strategic planners with the analytical rigor needed to navigate this complexity. This overview outlines the strategic contours of the market, previews the operational depth contained in the full report, and demonstrates why access to granular, forward-looking intelligence is no longer optional but essential for 2026 decision-making.
A Market in Transition: Macro Trajectory and Structural Realities
During the 2020-2025 evaluation window, the global market for power generation equipment experienced a pronounced contraction phase, with total revenue declining from an estimated 219.62 billion USD at the start of the period to 175.0 billion USD by 2025. This downward pressure reflected a confluence of project delays, supply chain bottlenecks, and transitional demand patterns as legacy infrastructure phased out and new capacity faced permitting and financing hurdles. However, the trajectory has decisively shifted. Forecast modeling for the 2026-2032 horizon indicates a sustained recovery, with market size projected to climb back to 185.76 billion USD in 2026 and continue expanding at a compound annual growth rate of 5.1 percent. By 2032, the sector is expected to surpass 237 billion USD in revenue, signaling a durable growth cycle rather than a temporary rebound.
For corporate strategists, this inflection carries critical implications. The early-cycle contraction masked underlying demand resilience, while the projected expansion underscores that capacity additions, modernization programs, and distributed generation deployments are aligning into a sustained build-out phase. The 5.1 percent CAGR is not merely a statistical projection; it reflects structural drivers including grid modernization mandates, industrial power demand surges, data center expansion, and the ongoing need for reliable baseload and flexible peaking capacity. Companies that treat the market as a static procurement environment risk misallocating capital, whereas those that map procurement cycles, technology roadmaps, and partnership strategies to this growth trajectory will secure favorable positioning.
The 2026 Decision Architecture: Why This Research Matters Now
Entering 2026, executives are operating at the intersection of multiple compounding forces. Demand forecasts indicate that electricity usage is expected to grow by an average of 5.7 percent annually over the next five years, with peak demand growth reaching 166 GW. Such magnitude of load expansion places unprecedented pressure on generation planning, equipment lead times, and balance-of-plant integration. Simultaneously, cost structures are being reshaped by material input pressures. Tariffs on imported steel and aluminium are elevating costs for power generation equipment and transmission projects, turning historical cost assumptions into unreliable planning benchmarks. Engineering-heavy deployments now require more sophisticated scenario modeling to protect margins and avoid schedule overruns.
On the regulatory front, the policy environment has tightened considerably. A U.S. executive action concluded market-distorting subsidies for unreliable foreign-controlled energy sources in July 2025, accompanied by strict enforcement of tax credit terminations. This development alters the economic calculus for project developers, equipment selectors, and financing structures, particularly for hybrid or transitional assets. In parallel, reliability challenges are surfacing in major load centers. Utilities in New York City have encountered reliability violations linked to peaker plant retirements under stricter emissions requirements, necessitating temporary dual-fuel retention through 2026 to preserve grid stability. These localized stress events are not isolated; they are early indicators of broader reliability-compliance tension that will influence equipment selection criteria, dispatch flexibility requirements, and O&M contract structures throughout the forecast period.
Strategic planners must therefore answer a series of interlocking questions: How should procurement timelines align with projected capacity additions? Which equipment categories will capture the largest share of near-term investment? What regional dynamics will dictate contract negotiation leverage? How are leading incumbents adjusting their portfolios to serve data center, utility-scale, and distributed power demand? The full PW Consulting report is structured to resolve these questions with methodological precision, but the strategic takeaway is already clear: 2026 is a year in which informed anticipation will separate market leaders from reactive followers.
Power Generation Equipment Market
Inside the Research: Operational Depth Designed for Action
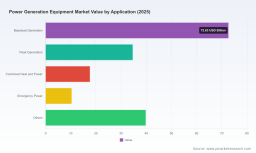
Our study is built around the principle that high-level market sizing alone does not drive execution. The report delivers a comprehensive analytical framework covering technology segmentation, application dynamics, regional deployment patterns, competitive positioning, and forward-looking scenario modeling. Readers will find a detailed breakdown of equipment categories spanning turbines, reciprocating engines, boilers, heat exchangers, and power transformers, with emphasis on how each segment is being reshaped by performance requirements, emissions constraints, and system integration needs. The analysis maps how baseload generation, peak generation, combined heat and power, emergency power, and other application classes are diverging in procurement behavior and technology preference, enabling buyers and suppliers to calibrate product strategies accordingly.
The regional dimension is examined with attention to deployment intensity, policy influence, and infrastructure readiness, helping organizations identify where demand concentration is forming and where partnership or localization strategies may be required. Equally important, the study incorporates a realistic appraisal of cost and supply-side headwinds, including the impact of tariff-driven input cost escalation on large engineering projects and the implications of labor and material conditions on delivery schedules. Rather than presenting static snapshots, the report integrates these variables into a cohesive view of market dynamics, allowing readers to stress-test assumptions and prepare for multiple plausible outcomes.
Worldwide Power Generation Engines Market
To preserve the analytical leverage of the complete publication, we intentionally avoid disclosing the specific regional share splits, application-level revenue figures, and segment-level breakdowns in this preview. Those detailed matrices, combined with scenario-adjusted projections and competitive cross-referencing, form the core intelligence layer that decision-makers rely on when sizing investments, negotiating frameworks, and prioritizing technology roadmaps. Accessing the full report ensures that your team can work from the exact percentages, magnitudes, and relational insights necessary for precise planning.
Competitive Landscape: Positioning, Portfolio Moves, and Recent Signals
The market is characterized by meaningful concentration, with the top three players accounting for approximately 58.0 percent of revenue and the top five reaching roughly 62.0 percent. This structure signals a landscape where scale, integrated service offerings, and long-term framework agreements carry disproportionate strategic weight. Yet the competitive field remains diverse, with specialist manufacturers, regional integrators, and technology-focused entrants all pursuing differentiated pathways. The following companies illustrate the range of strategic postures currently shaping the market.
-
Wärtsilä Corporation , headquartered in Helsinki, Finland, continues to expand its footprint through integrated power generation packages, including 2-stroke and 4-stroke engines and gas turbines. Its recent 123 MW power plant order in Odessa, Texas, booked in the first quarter of 2026 for ERCOT grid supply, demonstrates a clear emphasis on grid-serving flexible capacity alongside comprehensive O&M agreements. Wärtsilä’s positioning reflects a strategy centered on delivery reliability, modular plant configurations, and long-term service partnerships.
-
Caterpillar Inc. , based in Irving, Texas, United States, maintains a broad portfolio of reciprocating engines, gas turbines, and large-scale power generation packages. Its strategic relevance is amplified by framework-level commitments, including a 1.4 GW framework agreement secured with Atlas Energy Solutions Inc. for data center and distributed power projects, with initial orders anticipated between 2027 and 2029. Caterpillar’s capacity to anchor multi-year, high-volume deployments underscores its role as a backbone supplier in scaling distributed and industrial generation.
-
2G Energy AG , headquartered in Heek, Germany, specializes in containerized cogeneration and power generation equipment, with a notable focus on natural gas-fired plants for data center applications. In May 2026, its North American subsidiary received a major order for containerized power generation equipment to equip data centers, with deliveries beginning in the second half of 2026. This move highlights the growing importance of packaged, rapidly deployable solutions in high-density power environments.
-
Atlas Energy Solutions Inc. , located in Austin, Texas, United States, operates as a procurer and integrator of high-efficiency natural gas reciprocating engine generators and power generation packages for long-term distributed power solutions. Beyond its March 2026 framework agreement with Caterpillar, Atlas placed an order in November 2025 for 240 MW of power generation equipment, with 4 MW per engine units and delivery scheduled for late 2026. Its strategy illustrates the integrator model, where equipment aggregation, project coordination, and long-term service alignment create value beyond the hardware itself.
-
Liberty Advanced Equipment Technologies LLC , based in Houston, Texas, United States, supplies Bergen Engines-based power generation equipment and balance-of-plant solutions for data center and distributed power projects. In May 2026, the company entered 505 million USD in supply contracts with Bergen Engines, with deliveries planned across 2027 and 2028. This contract scale signals strong confidence in engine-based solutions for near-term capacity deployment and reflects the increasing relevance of balanced plant integration in project economics.
-
Solar Turbines Incorporated , headquartered in San Diego, California, United States, offers factory-packaged gas turbine generator sets ranging from 1 to 39 MW for industrial and utility power generation. Its product range positions the company well for modular industrial deployments and mid-scale utility applications where packaged reliability and simpler commissioning are prioritized.
-
Shanghai Electric Group Company Limited , based in Shanghai, China, provides synchronous condensers, generators, and power generation equipment for grid connection and utility-scale applications. Its focus on grid interfacing and large-scale generation hardware aligns with infrastructure-heavy expansion routes and transmission-linked generation planning.
-
IHI Corporation , headquartered in Tokyo, Japan, is developing ammonia-capable gas turbines and boilers for low-emission power generation equipment. This technological orientation points toward a longer-horizon strategy in which fuel flexibility and emissions performance become central differentiators, especially as procurement criteria increasingly weigh future-proofing against regulatory trajectories.
These profiles demonstrate that competitive advantage is no longer defined by product breadth alone. It is increasingly determined by the ability to secure framework agreements, integrate balance-of-plant components, deliver containerized or modular packages for fast-deployment environments, and align offerings with emerging fuel and emissions pathways. Our full report maps these strategic postures against market share dynamics, order flow indicators, and technology migration patterns, enabling readers to identify where partnerships, procurement shifts, or capacity investments are likely to yield the highest return.
From Intelligence to Execution: What 2026 Demands
The convergence of rapid load growth, material cost volatility, regulatory recalibration, and concentrated supplier power means that 2026 will reward organizations that can move from awareness to action with precision. Procurement teams must anticipate lead-time compression and competition for high-demand equipment categories. Engineering and project developers must build cost models that account for tariff-sensitive input structures and dual-fuel or emissions-compliant configurations where local reliability requirements dictate. Commercial teams must evaluate framework opportunities with a clear understanding of which incumbents are scaling data center and distributed power commitments, and which technology pathways are gaining traction for low-emission or fuel-flexible deployments.
Equally important, executives should treat the market as a system rather than a series of isolated purchases. The interaction between baseload requirements, peaking flexibility, combined heat and power efficiency, and emergency backup needs creates cross-segment dependencies that influence total cost of ownership, dispatch strategy, and service contract design. Understanding how these application classes relate to one another, and how equipment categories such as turbines, engines, boilers, heat exchangers, and transformers are positioned within each, is essential for building resilient investment plans.
Accessing the Full Intelligence: The Strategic Case for the Complete Report
This preview has outlined the market’s direction, the decision environment now taking shape, and the competitive dynamics that will influence outcomes through the end of the decade. Yet the most valuable insights, including the precise regional deployment figures, application-level revenue compositions, segment-level magnitudes, and scenario-adjusted forecasts, are reserved for the complete PW Consulting Power Generation Equipment Market study. By withholding those specifics here, we underscore a simple principle: durable strategic advantage comes from working with the full data architecture, not from partial signals.
Organizations that secure the complete report will be equipped to quantify demand concentration, benchmark competitor positioning, model cost and regulatory scenarios, and align procurement and investment plans with the most probable market pathways. In a sector where growth is returning, concentration is high, and external pressures are intensifying, the difference between reactive purchasing and proactive strategy will be defined by the quality of intelligence underpinning each decision. The full study provides that foundation, enabling your team to move into 2026 with clarity, discipline, and competitive confidence.
For detailed analysis of this topic, please visit the official page: Power Generation Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


