



PW Consulting: AI Learning Machine Market to Reach $33.95B by 2032, Expanding at 21.08% CAGR (2026-2032)

Navigating the Next Wave: Strategic Intelligence in the Worldwide AI Learning Machine Market Through 2032
The global education technology landscape is undergoing a structural transformation. Artificial intelligence is no longer an auxiliary feature grafted onto traditional hardware; it has become the core architecture of the next generation of learning tools. For enterprises, investors, and policy-aligned strategists, the Worldwide AI Learning Machine Market represents one of the most consequential convergence points of hardware engineering, large-model deployment, and pedagogical design. Our newly published market research study maps this evolution with granular precision, offering decision-makers a disciplined framework to navigate a sector expanding at a remarkable pace. The base year for this analysis is 2025, with historical tracking spanning 2020 through 2025 and a comprehensive forecast horizon extending from 2026 to 2032. This temporal architecture is deliberately designed to capture inflection points rather than incremental drift, enabling leadership teams to align capital allocation, product roadmaps, and partnership strategies with the trajectory of real demand.
Why Strategic Timing Matters in 2026
The year 2026 functions as a critical proving ground. Market momentum has already conditioned stakeholders to expect compound annual growth rates in the low-to-mid twenty percentiles across the forecast window, reflecting the compounding effect of hardware refresh cycles, model capability upgrades, and institutional adoption. The revenue scale, measured consistently in millions of U.S. dollars, has progressed from a modest foundational base into a multi-billion-dollar enterprise ecosystem. Historical progression shows a clear acceleration curve: the market expanded steadily through the early 2020s, crossed decisive thresholds in the post-pandemic normalization period, and surged into a higher operational tier by 2025. From that plateau, the forward projection outlines a steeper growth arc that stretches well into the early 2030s, signaling that the current cycle is not a transient spike but a structural expansion driven by durable adoption vectors.
For corporate strategists, the operative question is not whether the category will grow, but how to position within it before competitive moats solidify. Early-mover advantages in ecosystem integration, content syndication, and model-to-hardware optimization are already reshaping margin structures and user retention dynamics. Enterprises that treat AI learning machines as pure hardware plays risk capturing only a fraction of the value chain. Those that orchestrate content partnerships, localized curriculum alignment, and differentiated interaction models are building defensible positions. The report dissects these positioning mechanics without resorting to surface-level aggregation, ensuring that executives can distinguish between noise and actionable signals.
Report Architecture and Actionable Contents
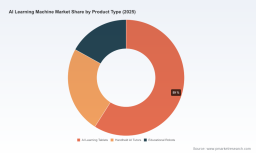
This study is engineered for operational deployment rather than passive reading. It begins with macroeconomic and demographic tailwinds that anchor demand, then proceeds into a multi-dimensional segmentation lens covering product architecture, regional deployment patterns, and end-user institutional behavior. Rather than presenting static snapshots, the analysis emphasizes transition dynamics: how tablet-centric form factors are being reconfigured by intelligent base modules, how handheld tutoring devices are absorbing conversation-driven interfaces, and how educational robotics are moving from novelty to structured classroom adjuncts. The end-user dimension captures the distinct purchasing rhythms, procurement constraints, and pedagogical expectations across primary and secondary education environments, higher education contexts, and vocational or corporate training programs. Each segment is examined through the lens of adoption friction, content dependency, and total-cost-of-ownership considerations that actually dictate procurement decisions.
The operational core of the report addresses the components that typically determine execution success. Readers will find structured evaluations of hardware design trade-offs, thermal and battery constraints in sustained AI inference environments, localization requirements for multilingual and curriculum-specific content, and the integration pathways between on-device processing and cloud-scale model updates. The study also maps the content ecosystem layer, where exclusive licensing arrangements, pedagogical validation, and age-appropriate design standards increasingly function as competitive differentiators. Procurement and distribution channels receive dedicated treatment, including direct-to-consumerigital funnel dynamics, institutional bulk purchasing cycles, and after-sales service expectations that influence brand loyalty and replacement cadence. The analytical framework is deliberately built to support scenario planning, allowing strategy teams to stress-test assumptions around pricing elasticity, model capability thresholds, and regulatory shifts before committing to long-cycle investments.
Worldwide AI Learning Machine Market
Competitive Dynamics and Innovation Velocity
The competitive landscape is defined by a concentrated set of enterprises that are actively converting AI capability into differentiated learning experiences. The report profiles the organizations that are shaping category standards, from firms that anchor their devices around cognitive large models and interactive voice tutoring to players that pair traditional tablet hardware with intelligent base architectures for study companionship and diagnostic feedback. Several leading developers have integrated adaptive learning pathways, homework scanning, and real-time error analysis into unified device experiences, while others emphasize curriculum synchronization, screen protection features, and structured tutoring workflows designed for sustained daily use. Smart hardware ecosystems are also expanding beyond dedicated learning terminals, with voice-enabled platforms and general consumer AI devices increasingly absorbing educational content features.
Autonomous Mobile Robotic Machine Market
Recent development activity underscores the speed at which competitive differentiation is being constructed. Strategic content partnerships have emerged as a high-leverage maneuver, with flagship devices securing exclusive access to award-winning animation libraries and immersive language-learning assets to deepen engagement and justify premium positioning. Product innovation cycles have accelerated in parallel, with next-generation designs introducing intelligent base modules that transform conventional tablets into interactive study companions capable of personalized diagnostics and emotionally responsive interaction. Financial disclosures from the sector further validate the demand surge, with certain category leaders reporting year-over-year revenue expansion in the smart education segment that reflects both volume growth and successful premiumization of AI-enhanced features. These developments are mapped in chronological and functional context within the report, enabling readers to separate one-off announcements from durable capability upgrades that will influence multi-year competitive positioning.
Regulatory Architecture, Supply Constraints, and Demand Catalysts
The operational environment for AI learning machines is being shaped by an intersecting set of policy directives, security standards, and supply-side realities. National assessment frameworks for machine learning algorithm security and baseline requirements for generative AI services are establishing compliance boundaries that affect model deployment, corpus curation, and content filtering obligations. Concurrently, education authorities are formalizing AI literacy mandates that create institutional demand for classroom-adjacent tools and structured digital learning environments. These policy signals do not merely constrain the market; they actively redirect procurement toward compliant, curriculum-aligned devices and incentivize manufacturers to implement content safety boundaries, including the exclusion of gaming-oriented material from dedicated learning platforms.
At the same time, hardware supply dynamics introduce strategic complexity. Export controls on advanced semiconductors and related manufacturing equipment have reshaped the calculus of high-performance compute access for model training and on-device inference, pushing developers toward architectural tradeoffs, optimization strategies, and regional sourcing diversification. These constraints are analyzed not as abstract geopolitical commentary but as practical inputs into product roadmap planning, cost structure modeling, and time-to-market assessments. On the demand side, policy measures that limit traditional offline tutoring have accelerated the shift toward compliant at-home educational tools, reinforcing the role of AI learning machines as structured, monitorable alternatives for families and schools seeking continuity in academic support. The report synthesizes these dynamics into a coherent operating environment assessment, enabling strategists to anticipate compliance overhead, supply risk exposure, and demand-side reinforcement cycles.
Structural Concentration and the Road Ahead
Market structure analysis reveals a landscape where scale, ecosystem depth, and brand trust are consolidating advantage. Concentration metrics indicate that a relatively small cohort of leading enterprises commands a substantial share of category revenue, while a broader tier of regional and specialized players competes on localized curriculum alignment, price accessibility, and niche hardware features. The report examines how this concentration evolves under the pressure of continuous model iteration, content partnership competition, and incremental hardware commoditization. It evaluates where differentiation is most defensible, where margin compression is likely to intensify, and where partnership networks can create switching costs that protect share without relying solely on specification escalation.
For executives planning beyond the immediate fiscal cycle, the forecast horizon offers a structured view of the pathways that will define the next phase of category maturation. Revenue progression across the forecast window reflects a market that is not simply expanding in absolute terms but recalibrating its value drivers around model intelligence, content authority, and user retention. Strategic readers will find the analysis particularly useful for evaluating entry timing, partnership structures, and product architecture choices that align with long-run adoption curves rather than short-term promotional spikes. The study intentionally preserves the granularity required for operational planning while directing attention to the analytical frameworks that convert raw market size into executable strategy.
How to Use This Intelligence
This report is designed to function as a decision-support instrument rather than a static reference document. Leadership teams can deploy it to calibrate product portfolio priorities, assess partnership opportunities in content syndication and ecosystem integration, and stress-test regional expansion assumptions against procurement behavior and regulatory direction. It also serves as a benchmarking foundation for competitor monitoring, enabling strategy groups to track capability upgrades, content licensing moves, and financial momentum without relying on fragmented news cycles. Because the analysis distinguishes between headline growth and the structural variables that sustain it, readers can separate durable adoption from cyclical hype and allocate attention accordingly.
To access the complete segmentation detail, full company profiles, development timelines, regulatory mapping, and forward projection tables that support these conclusions, please visit the source page for the Worldwide AI Learning Machine Market research. The published study provides the operational depth required for investment committee reviews, product strategy sessions, and market entry evaluations, ensuring that strategic decisions are anchored in verified market architecture rather than surface-level impressions.
For detailed analysis of this topic, please visit the official page: Worldwide AI Learning Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


