



PW Consulting: Polyetherimide Films Market to Hit $843.66 Million by 2032, with 7.12% CAGR

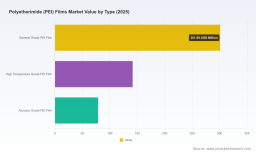
Strategic Intelligence for the Polyesterimide Era: Navigating the 2026 Polyetherimide Films Market
The global Polyetherimide (PEI) films market stands at a critical inflection point. As industries demand higher performance materials capable of withstanding extreme thermal and mechanical stress, PEI films have transitioned from niche specialty inputs to essential components in high-value manufacturing. This report serves as a definitive strategic compass for executives seeking to capitalize on the projected revenue trajectory reaching 843.66 million USD by 2032, evolving from a 521.5 million USD baseline in 2025. Understanding these shifts is not merely an academic exercise but a prerequisite for securing supply chain resilience and identifying high-margin growth vectors in 2026 and beyond.
Macro Trajectory and Growth Dynamics
The market has demonstrated remarkable recovery and expansion following the volatility of the early twenty-first decade. Historical analysis from 2020 through 2025 reveals a compound annual growth rate of 7.12 percent extending into the forecast period of 2026 to 2032. This sustained expansion is underpinned by the material unique ability to maintain structural integrity at temperatures up to 217°C, a property that continues to displace traditional polymers in critical applications. The revenue progression from 460.09 million USD in 2024 to the anticipated 549.14 million USD in 2026 underscores a robust demand environment that rewards early movers with superior material formulations and strategic partnerships. Stakeholders must recognize that this growth is not uniform across all segments. The divergence between standard performance grades and specialized high-temperature or acoustic variants presents distinct risk-return profiles that require nuanced portfolio management.
Segmentation Architecture and Demand Vectors
A granular understanding of product types and application end-uses is vital for optimizing production capacity and R&D expenditure. The market is fundamentally divided into three primary film grades, each serving a specialized industrial function.
- General Grade PEI Film represents the volume backbone of the industry.
- High Temperature Grade PEI Film caters to extreme environment applications where thermal stability is non-negotiable.
- Acoustic Grade PEI Film addresses noise reduction requirements in mobility and consumer electronics.
Parallel to product segmentation, demand is aggregated across four key application clusters. Electronics and Semiconductors constitute a major consumption pillar, driven by miniaturization trends and the need for durable insulation in flexible circuitry. Aerospace and Defense remain a high-value segment, where material certification and flame resistance are paramount. The Automotive sector is increasingly integrating PEI films into lightweighting initiatives and electric vehicle battery management systems. Industrial and Medical applications round out the demand landscape, leveraging the material biocompatibility and chemical resistance for precision equipment and diagnostic devices.
Regional Market Distribution
Geographical dynamics play a decisive role in sourcing strategies and market entry timing. The Asia Pacific region commands the largest share of market activity, reflecting the concentration of electronics manufacturing and rapid industrialization. North America and Europe maintain significant presence, supported by stringent aerospace regulations and advanced medical device ecosystems. The Rest of World region represents an emerging frontier with growing potential for infrastructure development and localized production. Companies must navigate varying regulatory landscapes and logistics costs across these territories to maximize margin realization.
Competitive Landscape and Corporate Profiles
Market concentration is substantial, with the top three competitors accounting for approximately 62.45 percent of total revenue and the top five controlling nearly 78.3 percent. This oligopolistic structure suggests high barriers to entry and emphasizes the importance of supply partnerships for downstream manufacturers.
SABIC, headquartered in Riyadh, Saudi Arabia, maintains its position as a global leader in ULTEM™ polyetherimide films. The company offers thin-gauge films ranging from 0.025 to 2 mm, specifically engineered for aerospace, electronics, and medical applications that require heat resistance up to 217°C. Their technical datasheets confirm that specific grades achieve UL 94 V-0 flame ratings at thicknesses as low as 0.075 mm, fully complying with aerospace FAR 25.853 standards. This certification capability is a critical differentiator for defense and aviation contractors.
Ensinger GmbH, based in Nufringen, Germany, produces TECAPEI™ PEI films and sheets tailored for technical applications. Their product line serves the automotive, electronics, and medical sectors, offering both standard and custom thicknesses to accommodate diverse processing requirements. The European manufacturer emphasis on precise thickness tolerances supports high-volume automotive production lines where consistency is essential.
RTP Company, located in Winona, Minnesota, USA, provides custom-compounded PEI films designed for specialty applications. Their expertise in electrical insulation and flexible circuitry allows them to address niche technical demands that standard off-the-shelf products cannot meet. This customization capability enables rapid prototyping and collaboration with engineering teams during product development phases.
Supply Chain and Raw Material Considerations
Strategic planning must account for feedstock dynamics and regulatory compliance. The market has experienced pressure from raw material cost fluctuations, notably regarding m-Phenylene diamine (MPDA), a key monomer for PEI synthesis. In Asia, MPDA prices rose 12 percent year-over-year to approximately 2,500 USD per metric ton during the third quarter of 2024 due to feedstock tightness. This volatility impacts production costs and requires hedging strategies or long-term supplier agreements to protect profitability.
Worldwide Polyetherimide (PEI) Films Market
Regulatory frameworks continue to shape market access and product specifications. Certain PEI film grades have met EU REACH Annex XVII restrictions on BPA migration for food contact applications, expanding the material utility in packaging and food processing equipment. Additionally, compliance with flame retardancy standards and aerospace certification requirements remains a gatekeeper for entry into high-value sectors. Manufacturers must ensure their product portfolios align with evolving global safety and environmental regulations to avoid market exclusion.
Operational Scope and Executive Utility
This comprehensive study delivers actionable intelligence designed to support cross-functional decision-making. The analysis covers historical performance benchmarks and forward-looking forecasts that enable capacity planning and investment prioritization. Readers will gain access to detailed segmentation evaluations that clarify demand drivers across product types and application sectors. The report also examines competitive positioning, benchmarking key players against performance metrics and geographic reach.
Procurement and supply chain teams will find value in the raw material trend analysis and regulatory updates that inform risk mitigation strategies. R&D and product development stakeholders can leverage the technical specifications and grade comparisons to align material selection with end-user requirements. Sales and marketing organizations benefit from the regional distribution insights that guide market expansion and channel partner selection.
Polyetherimide (PEI) Market
Strategic Imperatives for 2026
As the market advances toward the 2032 horizon, successful organizations will be those that integrate material science expertise with commercial agility. The convergence of electric vehicle adoption, semiconductor packaging complexity, and aerospace fleet modernization creates a favorable demand environment. However, capturing this opportunity requires disciplined execution in procurement, compliance management, and customer collaboration.
Decision-makers who engage with this intelligence early will be better positioned to negotiate favorable terms, anticipate supply constraints, and align product roadmaps with emerging application needs. The data presented herein provides the foundation for building resilient strategies that navigate the complexities of a concentrated global market while capitalizing on the 7.12 percent growth trajectory projected over the forecast period.
About This Research
This analysis is derived from PW Consulting Worldwide Polyetherimide (PEI) Films Market study, offering a complete view of market size, segmentation splits, competitive dynamics, and regional distributions. The full report includes detailed data tables, methodology disclosures, and strategic recommendations tailored for C-suite executives, investors, and industry analysts. For complete access to all segmentation data, company profiles, and forecast models, please refer to the source publication available through our research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Polyetherimide (PEI) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


