



PW Consulting: Worldwide Headphones Without Mic Market Hits $4.8B in 2025, Projects 4.25% CAGR to 2032

Strategic Clarity in an Audio Market Defined by Purity: Inside the 2026 Worldwide Headphones Without Mic Report
The global audio hardware landscape is undergoing a quiet but decisive realignment. As voice assistants, hybrid meeting ecosystems, and always-on connectivity become default expectations, a distinct counter-trend has solidified around devices engineered purely for sound reproduction. Our latest Worldwide Headphones Without Mic Market research isolates this specialized segment, delivering a ten-year analytical window that spans historical baselines from 2020 through 2025 and a forward-looking forecast extending to 2032. For executives, product planners, and supply chain leaders navigating 2026 procurement cycles and portfolio resets, this publication functions as a decision-grade intelligence layer rather than a static market snapshot.
Headphones without microphones occupy a unique position in the broader audio ecosystem. Their value proposition is measured in acoustic fidelity, driver engineering, closed or open-back architecture, and purpose-built ergonomics for monitoring, critical listening, and focused entertainment. They are not optimized for two-way communication; they are optimized for signal purity. That distinction has become commercially significant. Professional studios, home audio enthusiasts, and audiophile communities continue to prioritize passive acoustic designs, while manufacturers face mounting pressure to separate product lines that serve communication-heavy use cases from those that serve performance-first applications. Understanding where revenue concentrates, how product typologies evolve, and which regional dynamics dictate sourcing strategies has never been more essential to capital allocation.
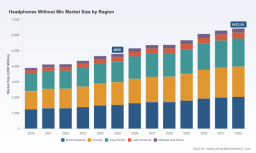
The headline trajectory captured in our analysis reflects sustained, disciplined expansion. The worldwide market for headphones without microphones crossed the 4.8 billion USD threshold in 2025 and is projected to advance toward a range above 6.4 billion USD by the end of the 2032 forecast period, supported by a compound annual growth rate of 4.25 percent. These figures are not abstract totals; they are a structural signal. The growth pace suggests a mature but resilient category, one that expands less through explosive category creation and more through steady replacement demand, premiumization in professional and enthusiast segments, and incremental penetration of high-performance personal audio in home entertainment environments. For 2026 strategy sessions, the implication is clear: this is not a market to treat as a commodity derivative of general headset sales. It behaves according to its own acoustic priorities, procurement cycles, and competitive benchmarks.
What the Report Delivers for 2026 Decision-Making
A market study earns its place on an executive dashboard only when it translates data into operational choices. Our Worldwide Headphones Without Mic Market report is built for that purpose. Rather than offering a single aggregated number, the analysis deconstructs the market into actionable dimensions that align with how companies actually plan, source, and launch.
Structural Breakdown Across Product Typologies and Use Cases
The research disaggregates demand across the core physical architectures that define the segment: over-ear, in-ear, and on-ear form factors. Each architecture carries distinct manufacturing pathways, acoustic tuning priorities, and consumer or professional expectations. Over-ear designs continue to anchor professional and audiophile usage, where enclosure volume, damping materials, and driver spacing directly shape monitoring accuracy and long-session comfort. In-ear monitors sustain a highly specification-driven demand profile tied to stage monitoring, portable critical listening, and compact high-fidelity setups. On-ear configurations occupy a narrower but persistent niche, often balancing portability with acceptable acoustic isolation for focused listening scenarios.
Equally important is the application lens. Revenue flows through professional studio workflows, home entertainment setups, and audiophile listening environments, each with different purchasing cadence, performance tolerance, and willingness to invest in premium components. Studio-oriented procurement revolves around durability, consistency across units, and reference-grade tonal balance. Home entertainment purchases increasingly blend convenience with a desire for richer spatial presentation and reduced distortion at higher listening levels. Audiophile buying behavior is driven by component hierarchy, enclosure craftsmanship, and the perceived transparency of the signal chain. The report explains how these application pathways diverge in volume, margin profile, and product lifecycle expectations, enabling teams to align roadmap priorities with realistic demand pools rather than broad assumptions.
Competitive Positioning Beyond Brand Names
Market share is a starting point, not a conclusion. The report maps the competitive architecture of the segment through the lens of product philosophy, engineering specialization, and go-to-market focus. Entrants such as Sony Corporation, Sennheiser Electronic GmbH & Co. KG, Audio-Technica Corporation, Beyerdynamic GmbH & Co. KG, Grado Labs, AKG Acoustics, Focal-JMlab, and Audeze LLC are examined not as a simple ranking, but as players occupying distinct acoustic and commercial territories. Some compete primarily on studio durability and consistent reference tuning. Others emphasize handcrafted construction, planar magnetic driver technology, or high-end tweeter materials aimed at discerning listening audiences.
The analysis also tracks how these companies are actively shaping the segment through product updates and targeted launches. Recent activity includes the introduction of open-back studio models designed for mixing accuracy, the continued availability of stationary studio headphones alongside USB-enabled variants, the release of closed-back professional models with upgraded driver technology, and catalog refinements for established studio lines in key domestic markets. These moves matter because they signal where incumbents believe performance differentiation remains achievable. For 2026 planners, the competitive section is designed to illuminate which innovation vectors are receiving investment, which product families are being maintained for continuity, and where the segment is seeing a deliberate reinforcement of passive, no-microphone architectures.
Macro Tailwinds and Supply-Side Realities Shaping 2026
Any credible forecast for audio hardware must account for the environment in which products are designed, sourced, and shipped. The report integrates current industry context so that strategy teams can test their assumptions against real operational friction rather than idealized market logic.
- Raw material pressures are reshaping cost structures at the component level. Neodymium magnet pricing has experienced measurable year-over-year escalation, reflecting supply chain constraints linked to rare earth processing. Since high-performance drivers rely heavily on magnetic flux efficiency, cost volatility in this input stream directly affects tuning targets, bill-of-materials planning, and margin defense in premium tiers.
- Manufacturing labor economics continue to adjust across major assembly geographies. Rising average hourly wages in key Vietnamese production hubs alter the traditional cost calculus for large-volume builds. The effect is not uniform across all product types, but it is meaningful for companies balancing cost leadership with consistent quality control in complex acoustic assemblies.
- Regulatory frameworks are becoming more prescriptive. Updated European restrictions on restricted substances in cable and component materials change compliance requirements for products destined for EU markets. For manufacturers operating multi-region supply chains, this is not a marginal administrative detail; it influences material selection, supplier qualification, and time-to-market for revised SKU configurations.
- Trade policy remains a live variable for imported audio hardware. Tariff exposure on certain Chinese-origin headphones continues to influence landed cost calculations for market entry and replenishment strategies. Companies with concentrated sourcing footprints must evaluate whether regional diversification, inventory buffering, or supplier renegotiation will be necessary to protect margin and availability in 2026.
- Lead times for advanced driver technologies have extended in certain high-specification categories, especially where rare earth processing bottlenecks affect specialized magnetic components. This constraint has practical consequences for launch timing, forecasting accuracy, and the ability to respond quickly to competitor announcements.
These dynamics are presented within the report as part of a broader operating environment, not as isolated headlines. The objective is to help decision-makers connect market expansion with the physical realities of production, compliance, and logistics. Growth is only valuable when it can be executed without eroding quality, delaying launches, or undermining cost discipline.
Worldwide Headphones Without Mic Market
Headphone Market
Concentration, Structure, and the Shape of the Competitive Field
The headphones without microphone segment is not equally dispersed across all participants. A meaningful share of revenue is captured by a relatively concentrated group of established manufacturers with strong engineering reputations, long-standing professional-channel relationships, and recognized brand equity in both studio and enthusiast circles. The report quantifies this concentration at the top of the market, providing a realistic picture of how much of the category’s economics are tied to a handful of players versus a broader tail of specialized or regional brands.
This structural insight is particularly useful for 2026 competitive planning. In a moderately concentrated market, pricing behavior, channel access, and innovation signaling can be influenced disproportionately by a few anchor companies. Simultaneously, the presence of differentiated specialists means that total market leadership does not necessarily translate into universal relevance across all applications. A company dominant in professional studio monitoring may compete under different rules than a high-end audiophile brand centered on planar magnetic transducers and handcrafted enclosures. Understanding where each competitor derives defensibility allows strategy teams to avoid generic competitive benchmarking and instead target the rival moves that actually affect their segment, margin structure, and product roadmap.
How the Report Becomes an Operational Tool
The Worldwide Headphones Without Mic Market study is designed to be referenced repeatedly throughout the planning cycle. Its structure supports scenario work, not just static reporting. Product teams can use the segmentation framework to compare form-factor momentum and identify where design investment will have the highest payoff. Procurement and operations leaders can incorporate the supply-side context into sourcing strategies, inventory planning, and cost negotiation timelines. Commercial and marketing leaders can map application-driven demand patterns to position products with the right performance messaging and channel focus.
The report also serves as a shared reference point for cross-functional alignment. In categories where audio performance, component availability, and regulatory compliance interact so closely, strategic misalignment often arises when engineering, sales, and supply chain teams work from different assumptions. By consolidating historical performance, forecast logic, competitive activity, and operating constraints into one coherent view, the research reduces the risk of decisions made on fragmented intelligence. That is especially valuable in 2026, when many organizations are recalibrating portfolios after several years of rapid change in consumer audio habits and manufacturing economics.
Why the Full Intelligence Layer Matters Now
Summarizing the market’s direction is useful; understanding its underlying mechanics is what changes decisions. The core figures, segmentation detail, competitive activity log, and operating-environment analysis are assembled to reveal the interplay between demand behavior and execution risk. When revenue expands steadily, the strategic question is not simply whether growth exists, but where it is coming from, which product lines are absorbing it, and what cost or compliance pressures could alter the return on investment behind each growth path.
This is why the complete report goes beyond a top-line narrative. It provides the structured breakdown, company-level context, and environmental variables that allow teams to pressure-test their own plans. Executives who rely only on aggregate totals may miss the product-type shifts, regional sourcing pressures, and competitive launches that actually reshape the field. Executives who work from the full analytical package can time launches more deliberately, prioritize engineering resources where acoustic differentiation still matters most, and anticipate supply-side constraints before they become schedule risks.
For organizations preparing 2026 budgets, product roadmaps, and channel strategies, the Worldwide Headphones Without Mic Market research offers a focused lens on a segment where sound quality is the product. The publication is built to translate that reality into measurable strategic advantage. The complete dataset, segmentation detail, and competitive activity timeline are available through the full report, where they can be examined in the depth required for confident decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Headphones Without Mic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


