



PW Consulting: Worldwide System on Module Boards Market Hits $2,450.5M in 2025, Expands at 11.45% CAGR

Strategic Intelligence for the Embedded Edge: Inside the Worldwide System on Module Boards Market Report 2026
In an era where embedded computing dictates the pace of industrial transformation, the System on Module (SoM) sector has evolved from a niche component category into a strategic infrastructure asset. As enterprises navigate the convergence of edge artificial intelligence, stringent regulatory frameworks, and shifting semiconductor supply chains, the requirement for precise, forward-looking market intelligence has never been more acute. PW Consulting’s latest Worldwide System on Module Boards Market research delivers exactly that: a comprehensive, data-grounded blueprint designed to inform capital allocation, product roadmapping, and supply chain strategy through 2032.
This report is crafted not merely as a statistical snapshot, but as an executive decision-support instrument. By synthesizing historical trajectory, architecture-level demand shifts, and the competitive maneuvers of established players, the study equips technology leaders, procurement directors, and venture strategists with the contextual clarity needed to operate in a market characterized by both rapid acceleration and structural volatility. The following overview outlines the analytical architecture of the research, demonstrates its immediate relevance to 2026 planning cycles, and illustrates how organizations can leverage its findings to secure competitive positioning in the embedded systems landscape.
Market Trajectory and Structural Momentum
The global System on Module Boards market has demonstrated sustained, compounding growth over the past half-decade, reflecting the accelerating migration from discrete component designs to integrated, carrier-board-compatible computing platforms. Historical valuations from 2020 through 2025 reveal a consistent upward arc, with the market expanding from approximately 1.42 billion USD to 2.45 billion USD. This trajectory is projected to maintain its momentum across the 2026 to 2032 forecast horizon, propelled by an anticipated compound annual growth rate of 11.45 percent. By the close of the forecast window, the market is positioned to surpass the 5.2 billion USD threshold, underscoring the embedded sector’s transition from complementary technology to core operational infrastructure.
Several macro forces are converging to sustain this expansion. The proliferation of edge computing requirements across manufacturing floors, medical environments, transportation networks, and commercial display ecosystems is driving demand for compact, thermally efficient, and power-optimized compute modules. Simultaneously, the industry is witnessing a structural recalibration of component availability. Average lead times for widely adopted system-on-chip platforms have compressed from prolonged multi-quarter bottlenecks to more manageable procurement cycles, while regulatory interventions such as the EU Chips Act are injecting capital into domestic semiconductor fabrication capacity. These conditions are gradually stabilizing the module supply environment, though they remain contingent upon geopolitical trade parameters and raw material pricing volatility, particularly in specialized compound semiconductors.
The Architecture and Standard Landscape
A defining characteristic of the SoM market is its bifurcated architecture ecosystem. ARM-based designs continue to capture the largest share of deployment volume, reflecting their dominance in low-power, highly integrated embedded applications. x86 architecture maintains a dedicated footprint, particularly in environments requiring higher computational throughput or legacy software compatibility, while PowerPC and FPGA-based modules serve specialized niches where deterministic processing, harsh-environment resilience, or custom logic acceleration is paramount. The strategic choice of architecture is no longer a purely technical decision; it is increasingly a function of supply chain resilience, vendor roadmap continuity, and long-term total cost of ownership.
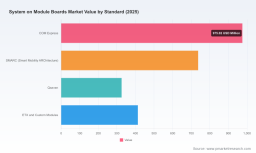
Standardization further shapes procurement and integration strategy. The COM Express specification remains a cornerstone for traditional embedded deployments, offering mature interoperability and broad carrier-board compatibility. SMARC has emerged as a highly flexible alternative, particularly in mobility-oriented and space-constrained applications where lightweight form factors and dynamic peripheral configurations are critical. Qseven continues to serve a stable segment of industrial and legacy-system refresh projects, while ETX and custom module approaches persist in highly specialized or security-sensitive deployments. Understanding how these standards intersect with specific architecture choices, thermal envelopes, and I/O requirements is essential for organizations designing next-generation embedded platforms.
Application Verticals and Demand Drivers
Demand for System on Module Boards is distributed across a diverse set of application verticals, each imposing distinct performance, certification, and lifecycle requirements. Industrial automation represents the most substantial demand pool, driven by the ongoing modernization of factory floors, the integration of vision-based quality inspection, and the deployment of distributed control nodes. Medical devices constitute another high-conviction segment, where modules must satisfy rigorous reliability standards, maintain long-term availability commitments, and support compact, low-noise form factors for diagnostic and patient-monitoring equipment.
Transportation and automotive applications continue to expand as advanced driver-assistance systems, in-vehicle infotainment, and fleet telemetry push compute workloads closer to the edge. Aerospace and defense deployments, while smaller in aggregate volume, command elevated margins and extended product lifecycles, with strict requirements for environmental hardening, traceability, and supply chain security. Retail and digital signage environments contribute steady demand for media-ready modules capable of driving high-resolution displays, handling connectivity stacks, and operating reliably in thermally variable public-facing settings. The report examines how each vertical’s unique procurement cycles, certification pathways, and technology refresh cadences influence module selection and vendor partnerships.
System on Module (SOM) Market
Competitive Landscape and Market Concentration
The competitive fabric of the SoM market is characterized by a mix of specialized embedded computing firms, regional manufacturing champions, and highly focused engineering-driven vendors. Market concentration metrics indicate a moderately fragmented environment, with the top three participants collectively accounting for roughly one-third of total revenue and the leading five firms representing just under half. This structure suggests that while scale players command meaningful share, there remains substantial room for differentiation through architecture specialization, regional supply chain positioning, and application-specific engineering support.
Several companies illustrate the breadth of strategic positioning within the sector. Swiss-based Toradex has built a recognized portfolio around its Verdin, Colibri, and Apalis module families, anchored by NXP i.MX, TI Sitara, and Renesas processor integration for industrial embedded use cases. Israel’s Variscite has concentrated on DART and VAR-SOM series platforms tailored for IoT and edge computing workloads, spanning NXP i.MX, TI AM, and Qualcomm silicon. German provider Kontron offers a broad standards portfolio, including SMARC 2.1, Qseven, and COM Express Type 6 modules, with Intel, AMD, and ARM processors targeted at rugged embedded systems. Taiwan’s Advantech supplies ROM-series and SOM-5720 platforms emphasizing industrial automation and medical applications, while Phytec develops phyCORE modules leveraging NXP, TI Jacinto, and Renesas processors for automotive and avionics contexts.
Additional players extend the competitive spectrum across geographic and application dimensions. Compulab delivers networking- and defense-oriented modules based on NXP i.MX platforms. Gateworks focuses on the Newport family for outdoor wireless and video applications, with recent production ramp activity tied to enhanced AI-capable silicon. TechNexion provides PICO and EDEN series modules for AI and vision systems, drawing on NXP, TI, and Rockchip processors. Within the China-based ecosystem, MYIR Tech and Forlinx Embedded Technology contribute ARM-centric and multimedia/HMI-focused modules across consumer and industrial segments, while AAEON and IEI Integration Corp supply SMARC and SOM platforms for IoT gateways and edge AI workloads. Italy’s Seco rounds out the landscape with SMARC and Qseven modules targeting transportation and smart city deployments.
Recent Product and Supply Chain Developments
The pace of module introductions and qualification milestones during the most recent reporting cycles underscores the sector’s emphasis on next-generation silicon and application-tuned performance. In late 2023, Toradex introduced its Verdin iMX93 System on Module, leveraging the NXP i.MX 93 dual Cortex-A55 processor to address edge AI workloads. Shortly thereafter, in early 2024, Phytec launched the phyCORE-AM69A module based on the Texas Instruments Jacinto AM69A, designed for advanced driver-assistance systems and machine vision applications. Kontron’s qualification of the KMM-T1 SMARC 2.1.1 module with the NXP i.MX 95 processor marked a notable step toward industrial IoT deployment readiness, while Gateworks announced the production start of its Newport iMX93 module with enhanced AI capabilities. These developments illustrate how vendors are aligning product roadmaps with the convergence of edge inference, improved power efficiency, and stricter system-level reliability expectations.
At the same time, supply chain dynamics continue to shape procurement strategy. While average lead times for key NXP i.MX system-on-chip components have shortened considerably from earlier peak periods, the market remains sensitive to export control frameworks, tariff structures on printed circuit board and component assemblies, and fluctuations in specialty raw material pricing. Elevated gallium costs, for example, have affected cost assumptions for gallium nitride components used in power-efficient module designs, while export restrictions on advanced semiconductor categories have introduced additional complexity for high-performance module sourcing. These factors reinforce the importance of scenario planning, multi-source qualification, and regional procurement balancing.
What the Report Delivers: Analytical Scope and Decision Utility
PW Consulting’s Worldwide System on Module Boards Market study is structured to provide actionable clarity across multiple layers of strategic inquiry. The analysis begins with a detailed quantification of market size and growth pathways across the historical baseline and the full 2026 through 2032 forecast window, expressed in consistent monetary terms to facilitate cross-period comparison and investment modeling. The report then disaggregates demand by architecture, standard, application, and regional footprint, enabling decision-makers to identify where growth is accelerating, where maturity is setting in, and where niche opportunities may justify targeted resource deployment.
Beyond aggregate sizing, the research provides granular competitive profiling that examines each major participant’s product portfolio, processor partnerships, geographic footprint, and recent tactical moves. This includes assessment of product launch cadence, qualification milestones, and supply agreement activity, contextualized within the broader market structure and concentration metrics. The report also integrates market dynamics analysis that maps regulatory interventions, trade policy shifts, lead-time normalization trends, and raw material cost movements to their implications for module availability, pricing curves, and procurement timing.
For engineering and product leadership, the study offers a practical lens on standard selection, form-factor trade-offs, and architecture alignment with target workloads. For procurement and sourcing teams, it provides context on supplier differentiation, regional supply chain exposure, and the evolving balance between commodity-adjacent modules and application-specialized platforms. For corporate strategy and investment functions, the report frames the market’s growth mechanics, competitive fragmentation, and mid-term expansion pathways in a manner conducive to capacity planning, M&A screening, and partnership evaluation.
Implications for 2026 Strategic Planning
As organizations finalize 2026 operating plans, the System on Module Boards market presents a mix of opportunity and execution complexity. The projected double-digit growth trajectory signals continued demand expansion, yet the underlying composition of that growth varies substantially across architectures, standards, and application verticals. Enterprises that rely on a single module family, a narrow processor vendor relationship, or a single regional sourcing channel face elevated exposure to supply interruptions, design obsolescence, or margin compression. Conversely, organizations that treat module selection as a strategic design variable—balancing performance, availability, standards interoperability, and vendor roadmap continuity—are better positioned to capture value from the market’s structural expansion.
Strategic priorities for 2026 should include a disciplined review of architecture roadmaps, with particular attention to the balance between established low-power platforms and emerging higher-performance silicon for edge inference. Procurement teams should evaluate multi-sourcing feasibility, qualification timelines, and long-term availability commitments, especially for modules tied to mission-critical or certification-bound deployments. Product planners should assess how evolving standards such as SMARC and COM Express align with carrier-board reuse strategies, thermal constraints, and end-customer integration expectations. Finally, leadership should incorporate regulatory and trade risk considerations into sourcing architecture, recognizing that export controls, tariff exposure, and specialty material pricing can materially affect cost structures and delivery reliability.
Conclusion
The Worldwide System on Module Boards market is entering a phase in which technology differentiation, supply chain resilience, and application-specific engineering support will increasingly determine competitive outcomes. PW Consulting’s 2026 research is designed to give executives, engineers, and sourcing leaders the analytical foundation required to navigate that environment with confidence. By combining rigorous market sizing, architecture- and standard-level segmentation, competitive profiling, and integrated market dynamics assessment, the report transforms complex market signals into a coherent decision-making framework. For organizations seeking to validate product roadmaps, optimize procurement strategies, or identify high-conviction growth segments, the full study provides the depth and structural clarity necessary to act decisively.
readers interested in the complete dataset, detailed regional and application breakdowns, and comprehensive vendor analyses are encouraged to access the full report through the official PW Consulting market research portal, where the complete intelligence suite is available for download and executive review.
Worldwide System on Module Boards Market
For detailed analysis of this topic, please visit the official page: Worldwide System on Module Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


