



PW Consulting: Global Military Protective Gear Market to Hit $22.93B by 2032, 4.5% CAGR

Navigating the Future of Defense Protection: Strategic Insights from the Worldwide Military Protective Gear Market 2026–2032
The global defense landscape is undergoing a profound transformation. As military forces worldwide recalibrate their operational doctrines, the demand for advanced protective gear has evolved from a commodity consideration to a critical strategic imperative. At PW Consulting, we recognize that informed decision-making in this sector requires more than surface-level observations. It demands a granular understanding of market trajectories, competitive dynamics, material science advancements, and the regulatory currents shaping procurement behaviors.
Our newly published Worldwide Military Protective Gear Market research report is designed precisely for this purpose. Serving as a comprehensive strategic compass, this study equips defense contractors, material suppliers, investment firms, and government procurement analysts with the intelligence needed to navigate the complex terrain of military personal protection through 2032. This article serves as a strategic preview, highlighting the analytical depth, actionable frameworks, and forward-looking perspectives embedded within the full report, while demonstrating why this intelligence is indispensable for enterprise strategy in 2026 and beyond.
The Macro Landscape: Resilient Growth Anchored in Strategic Shifts
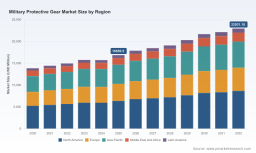
The worldwide military protective gear market has demonstrated remarkable resilience and steady expansion over the past half-decade. Drawing on historical performance data from 2020 through 2025, the sector has consistently grown, culminating in a base-year valuation of approximately 16,850.5 million USD in 2025. This progression reflects not only post-pandemic procurement normalization but also the accelerating modernization of armed forces, heightened geopolitical tensions, and the ongoing integration of advanced materials into personal protection systems.
Looking ahead, our forecast models project a clear upward trajectory. The market is anticipated to expand from roughly 17,877.5 million USD in 2026 to over 22,931.2 million USD by 2032, translating to a compound annual growth rate of 4.5 percent. This growth rate is neither speculative nor overstated; it is derived from rigorous bottom-up analysis that accounts for defense budgeting cycles, procurement lead times, inventory replenishment patterns, and the steady adoption of next-generation protective technologies. For strategic planners, this CAGR represents a sustainable expansion environment—one where long-term capacity planning, R&D investment, and supply chain optimization can yield compounding returns.
It is worth noting that this growth is not uniformly distributed across all market dimensions. The interplay between regional defense spending priorities, product-category evolution, and application-specific procurement drives creates distinct value pools. Understanding where capital is flowing, which procurement channels are gaining prominence, and how material preferences are shifting requires a detailed segmentation analysis that the full report provides in depth.
What the Report Delivers: A Blueprint for Actionable Intelligence
Market research at its best does not merely describe what has happened; it equips leaders to anticipate what will happen and act accordingly. Our Worldwide Military Protective Gear Market report is structured around this principle. It combines macroeconomic forecasting with granular operational insights, delivering a multi-layered analytical framework that supports everything from M&A targeting to product roadmap development.
At its core, the study offers a comprehensive segmentation architecture that dissects the market by region, product type, and application. Each segment is evaluated through the lens of demand drivers, procurement maturity, technological adoption curves, and competitive intensity. This allows readers to identify high-growth niches, assess market saturation risks, and benchmark their positioning against industry norms. Rather than presenting isolated statistics, the report weaves these dimensions into a cohesive narrative that explains how structural factors interact to shape market outcomes.
Worldwide Military Protective Eyewear Market
Beyond segmentation, the report provides an extensive competitive landscape analysis. Thirteen leading companies are profiled, with detailed assessments of their headquarters, core competencies, technological focus areas, and strategic positioning. These profiles go beyond corporate bios; they examine how each player leverages material science, manufacturing scale, government relationships, and innovation pipelines to capture share. Special attention is given to firms that have recently demonstrated momentum through contract extensions, major procurement awards, or strategic acquisitions, offering readers a real-time pulse on industry consolidation and capability expansion.
The study also incorporates a forward-looking analysis of market dynamics. Here, we explore the forces that will dictate competitive advantage in the coming years: raw material pricing pressures, regulatory compliance requirements, geopolitical procurement shifts, and the growing emphasis on multi-threat, lightweight protective systems. By contextualizing these dynamics within the broader market trajectory, the report enables readers to stress-test their strategies against plausible future scenarios.
Additionally, the report addresses practical operational considerations that often fall outside traditional market sizing exercises. Topics such as export control frameworks, international ballistic testing standards, and regional procurement preferences are examined for their implications on market access, supply chain design, and partnership strategies. For global players, these insights are critical to avoiding compliance pitfalls and aligning product portfolios with the expectations of key defense customers.
Competitive Architecture: Leaders, Innovators, and the Battle for Capability
The military protective gear sector is characterized by a concentrated yet dynamic competitive landscape. Our analysis indicates a market structure where a handful of dominant players command significant share, yet specialized innovators and regional manufacturers continue to carve out defensible positions through technological differentiation and niche procurement relationships.
Worldwide Military Protective Gear Market
Prominent incumbents such as 3M Company, BAE Systems, and Gentex Corporation anchor the upper tier of the market. 3M leverages its broad materials portfolio to deliver lightweight composites and multi-threat personal protection systems. BAE Systems focuses on integrated soldier systems, emphasizing modular armor architectures and advanced material integration for global military deployments. Gentex has carved a distinct niche in combat helmet innovation, particularly through its Advanced Combat Helmet programs and communication-integrated head protection platforms, recently extending its production support under a multi-year contract framework with the Defense Logistics Agency.
In the body armor and tactical vest segment, Point Blank Enterprises maintains a strong footprint through its focus on ballistic plates, shields, and protective vests tailored to U.S. military and Department of Defense requirements. DuPont and Honeywell International operate as critical upstream enablers, with DuPont's aramid fiber technologies and Honeywell's Spectra Shield composites serving as foundational materials for high-performance ballistic solutions across multiple end-users. Avon Protection rounds out the leadership cohort with its expertise in respiratory and CBRN defense systems, reflecting the market's growing emphasis on integrated, multi-hazard protection.
Beyond these established players, a vibrant ecosystem of specialized manufacturers drives innovation at the tactical level. ArmorSource LLC and Revision Military focus on lightweight helmet and eye-protection systems designed for dismounted operations, while Safariland and MKU Limited maintain strong positions in tactical carrier systems and export-oriented ballistic protection, respectively. In the Asia-Pacific manufacturing corridor, Ningbo Chowey Police Equipment Co., Ltd. has expanded its footprint in bulletproof vests, helmets, and tactical accessories, aligning with the broader shift toward diversified, internationally compliant supply chains.
Recent industry developments underscore the intensity of this competitive environment. In late 2025, the U.S. Army awarded substantial delivery orders for lightweight small arms protective insert plates, signaling sustained demand for enhanced ballistic performance without compromising weight thresholds. Simultaneously, strategic acquisitions such as Double Tap Industries LLC's absorption of Caliber Armor illustrate how market participants are consolidating capabilities to broaden product lines and strengthen their positioning across military and law enforcement segments. These moves are not isolated; they reflect a broader trend in which companies are actively reshaping their portfolios to capture emerging requirements in modularity, weight reduction, and multi-spectrum protection.
Market Dynamics: The Forces Reshaping Procurement and Innovation
Understanding the competitive map is only half the equation. The real strategic value lies in grasping the underlying dynamics that will determine which companies thrive and which struggle to maintain relevance. Several interconnected forces are currently redefining the military protective gear market.
Raw material economics remain a persistent pressure point. Advanced ballistic materials, particularly aramid fibers and UHMWPE-based composites, command premium pricing due to high manufacturing complexity and ongoing R&D investment aimed at achieving lightweight, multi-hit performance. For OEMs and system integrators, this translates into a constant balancing act between performance specifications, cost structures, and procurement budgets. Companies that can secure reliable material supply, optimize composite architectures, or introduce alternative high-performance fibers will hold a distinct advantage in margin management and contract competitiveness.
Regulatory and compliance environments further complicate market access. Stringent international ballistic testing standards require continuous third-party validation, and certifications must be maintained across multiple export markets to ensure interoperability and buyer confidence. In parallel, export control frameworks such as the U.S. International Traffic in Arms Regulations impose restrictions on certain ballistic technologies and materials, requiring careful licensing strategies for companies seeking to expand their international footprint. Navigating these requirements is not merely a legal exercise; it is a strategic capability that determines which markets are accessible and how quickly a company can scale into new regions.
Geopolitical recalibration is perhaps the most transformative dynamic of the current cycle. Rising NATO defense spending commitments, including the push toward 2 percent of GDP and a growing preference for European-sourced procurement by 2030, are driving demand for localized manufacturing and regional supply chain resilience. This shift is prompting both incumbent suppliers and new entrants to evaluate production footprints, partnership structures, and technology transfer arrangements. For companies with global ambitions, the ability to align with regional procurement preferences while maintaining technical and quality standards will be a defining factor in capturing government and allied contracts.
Together, these dynamics create a market environment that rewards agility, technical depth, and strategic foresight. The companies that succeed will be those that treat compliance, material innovation, and regional alignment not as operational afterthoughts but as core components of their growth strategy.
Why This Research Is Critical for 2026 Decision-Making
As organizations enter 2026, the decisions made today will shape competitive positioning for the remainder of the decade. Whether you are evaluating capacity expansion, assessing M&A targets, refining a product roadmap, or advising government clients on procurement optimization, the margin for guesswork is narrowing. Market intelligence must be precise, forward-looking, and directly applicable to operational strategy.
Our Worldwide Military Protective Gear Market report is built for exactly this moment. It provides the analytical scaffolding needed to move from high-level awareness to concrete action. Readers will gain clarity on which product categories are experiencing the strongest demand momentum, how regional procurement patterns are evolving, and where the competitive center of gravity is shifting. The report's company profiles, market dynamics analysis, and segmentation frameworks are designed to inform investment thesis development, partnership targeting, and risk assessment in a sector where technological advantage and procurement access are tightly intertwined.
Importantly, the full report contains detailed regional and application-level data, granular segmentation values, and comprehensive competitive metrics that are essential for precise strategic planning. While this overview highlights the structure and strategic relevance of the study, the complete dataset and in-depth analyses are available through the full report. We encourage defense industry executives, investment professionals, and policy-adjacent analysts to review the complete publication to ensure their 2026 strategies are grounded in the most current and comprehensive market intelligence available.
Conclusion: Strategic Clarity in a Rapidly Evolving Sector
The worldwide military protective gear market is entering a phase of sustained, structurally supported growth. Driven by modernization programs, evolving threat environments, and the relentless pursuit of lighter, more capable protection systems, the sector presents both opportunity and complexity. Success in this environment requires more than broad market awareness; it demands a detailed understanding of segmentation dynamics, competitive positioning, material and regulatory constraints, and regional procurement shifts.
PW Consulting's Worldwide Military Protective Gear Market research report delivers that understanding. By combining rigorous forecasting with practical, operationally relevant analysis, the study equips leaders to make confident, evidence-based decisions as they navigate the years ahead. For those committed to staying ahead of the curve in defense protection, the insights within this report are not just valuable—they are essential.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


