



PW Consulting: Global Micro Irrigation Market Hits $13.85B in 2025, Projected 9.5% CAGR to 2032

Unlocking Growth in the Worldwide Agriculture Micro Irrigation System Market: Strategic Intelligence for 2026 Decision-Makers
The global agriculture sector stands at a critical inflection point where water scarcity, climate volatility, and the demand for yield optimization converge to redefine operational priorities. For executives navigating the Worldwide Agriculture Micro Irrigation System Market, understanding the trajectory of this industry is no longer optional—it is a prerequisite for resilient growth. Our latest comprehensive market research report, covering the historical period from 2020 to 2025 and extending forecast insights through 2032, delivers the granular intelligence necessary to transform uncertainty into competitive advantage.
This study is designed specifically for strategic planners, investment committees, and commercial leaders who require more than surface-level statistics. By synthesizing historical performance data with forward-looking modeling, the report provides a robust framework for evaluating market entry, capacity expansion, partnership opportunities, and technology adoption. The analysis anchors on a baseline year of 2025, ensuring that all projections reflect the most current market realities while accounting for the accelerating shift toward precision water management across diverse agricultural landscapes.
Market Scale and Growth Trajectory: A Decade of Transformation
The macro picture emerging from our analysis underscores a sustained upward trajectory for micro irrigation adoption worldwide. The overall market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately 8,995 million USD in 2020 to 13,850 million USD in 2025. This historical momentum translates into a forecasted compound annual growth rate of 9.5 percent throughout the 2026-2032 forecast period, positioning the industry for substantial value creation well into the next decade.
By 2032, the market is projected to reach a revenue scale that reflects both incremental adoption and structural shifts in farming practices. This growth is not merely a function of population-driven food demand. Rather, it is propelled by a confluence of regulatory mandates, subsidy-driven affordability programs, technological maturation in sensor-enabled delivery systems, and an increasingly urgent corporate sustainability mandate across the agri-food value chain. Organizations that align their roadmaps with these underlying drivers will be best positioned to capture disproportionate share during the forecast window.
It is important to recognize that the 9.5 percent CAGR represents an aggregate velocity that masks significant variation across system architectures, crop categories, and regional maturity levels. The report deconstructs these variations without oversimplifying them, enabling readers to identify where growth is likely to concentrate and which structural factors will act as tailwinds or constraints in specific contexts.
Structural Segmentation and Strategic Focus Areas
Micro irrigation is not a monolithic category. The report segments the market along three primary dimensions that matter most to commercial strategy: system type, crop application, and regional deployment patterns. Each dimension reveals distinct demand drivers, pricing dynamics, and competitive intensity.
Worldwide Agriculture Micro Irrigation System Market
- System architectures divide the market between drip irrigation configurations and micro-sprinkler technologies, each addressing different agronomic requirements, water pressure constraints, and capital expenditure profiles. The report evaluates how end-users weigh initial system cost against long-term operational savings, and how evolving emitter designs and filtration standards are reshaping purchasing decisions.
- Crop-type segmentation captures the divergence in irrigation needs across orchard crops and vineyards, field crops, greenhouse operations, and other specialized applications. The analysis highlights how crop value density, root-zone sensitivity, and harvesting logistics influence the willingness to invest in precision delivery infrastructure, and where bundled solutions are gaining traction over standalone component sales.
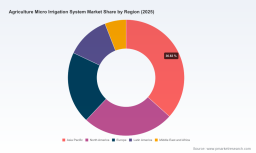
- Regional analysis maps demand intensity across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa, illuminating how local policy environments, water stress levels, farm structure, and distribution network maturity interact to shape market potential.
Throughout the report, we intentionally avoid presenting simplistic percentage shares or isolated dollar figures for individual segments in isolation. Instead, we contextualize each segment within the broader ecosystem, showing how cross-segment dynamics—such as the interplay between drip system adoption in high-value orchards and micro-sprinkler deployment in broader field contexts—inform total addressable market calculations and scenario-based forecasting. This approach empowers readers to build their own internal models based on a transparent analytical foundation.
Competitive Landscape: A Consolidated Arena with Differentiated Playbooks
Market concentration data indicates a moderately consolidated competitive environment, with the top three players commanding a combined share of approximately 42.5 percent and the top five firms extending their collective footprint to roughly 56.8 percent. Such concentration signals both the maturity of the industry and the strategic importance of scale, distribution reach, and technology differentiation. However, the presence of highly specialized regional players and vertically integrated manufacturers ensures that competition remains dynamic, particularly as newcomers and established firms alike pursue digital integration and localized service models.
The report profiles a curated set of leading organizations whose strategies illustrate the spectrum of approaches shaping the market:
- Netafim Ltd. (Orbia Advance Corporation) continues to leverage its pioneering heritage in drip irrigation, pairing hardware excellence with digital farming tools that enable real-time optimization of water and nutrient delivery across high-value crops such as avocados, wine grapes, corn, and sugarcane. Recent corporate moves underscore a dual focus on precision technology and large-scale partnership-driven deployment.
- Jain Irrigation Systems Ltd. operates a vertically integrated model anchored in the "More Crop Per Drop" philosophy, emphasizing water and fertilizer efficiency through ultra-low energy systems tailored to field crops, orchards, and innovative applications that expand micro irrigation into traditionally water-intensive practices.
- The Toro Company and Rain Bird Corporation both maintain strong positions in the North American market, offering comprehensive component and system portfolios that prioritize clogging reduction, emission uniformity, and water-use optimization across diverse crop production environments.
- Lindsay Corporation and Valmont Industries Inc. (Valley Irrigation) bridge large-scale center pivot and linear irrigation expertise with micro irrigation integration, enabling precision water management across expansive operations and leveraging digital platforms to optimize scheduling and resource allocation across multiple geographies.
- Rivulis Irrigation Ltd. delivers a broad micro irrigation portfolio spanning drip tapes, molded emitter lines, layflat pipes, filters, valves, and fertigation solutions, supporting field crops, orchards, greenhouses, and protected agriculture with an emphasis on manufacturing scale and regional responsiveness.
- Hunter Industries and Nelson Irrigation Corporation round out the competitive field with specialized product lines that address subsurface delivery, pressure-compensating emitters, high-uniformity micro sprinklers, and automation-enabled water management, catering to both crop production and specialized nursery or tree-vine applications.
Beyond corporate profiles, the report integrates a timeline of recent developments that illustrate how competition is shifting from hardware-only contestation toward ecosystem-level value creation. Notable examples include the introduction of AI-powered dosing product ranges for enhanced precision fertigation, collaborations aimed at deploying advanced drip irrigation at scale in high-growth agricultural markets, the launch of rotator sprinklers designed for reduced maintenance in orchard settings, facility expansions intended to shorten lead times in key regions, and patented hybrid dripline technologies that combine integral and on-line dripper configurations for labor-saving efficiency in vineyards, orchards, and greenhouses. Together, these moves signal an industry that is accelerating toward smarter, faster, and more integrated solutions.
Market Dynamics: Policy, Standards, and Input Economics as Strategic Levers
The growth narrative for micro irrigation cannot be disentangled from the policy and standards environment that frames adoption economics. Regulatory frameworks, subsidy architectures, and international standards collectively influence the cost-benefit calculus for farmers, distributors, and system integrators. The report examines several dynamics that are actively reshaping demand behavior and supply-side strategy.
Worldwide Micro Spray System Market
- Standardization efforts, such as international guidelines for the implementation of pressurized drip irrigation systems, provide a reference architecture that supports consistent performance expectations and reinforces the water-saving potential of properly designed micro irrigation configurations for both small-scale and large-scale operations.
- National datasets from major agricultural economies reveal a pronounced structural shift toward pressurized irrigation systems, including micro and drip technologies, across substantial portions of irrigated cropland in Western agricultural regions, reflecting a long-term preference for efficiency gains that compound over time.
- Subsidy programs continue to play a decisive role in accelerating adoption among small and marginal producers. In key markets, government schemes have extended substantial coverage across millions of hectares through 2024, with differentiated subsidy rates that make micro irrigation systems more accessible while maintaining quality benchmarks through component certification requirements.
- Large-scale public investment announcements in select regions have signaled intent to modernize irrigation infrastructure and reduce agricultural water consumption through advanced technologies, creating both near-term procurement opportunities and longer-term demand stability for system suppliers.
- Input economics remain a critical factor, as micro irrigation systems rely heavily on polymer-based tubing and emitters whose costs are sensitive to raw material markets. Subsidy eligibility frameworks in certain programs tie financial support to the use of certified components, meaning that supply chain compliance and material sourcing strategies carry direct commercial implications.
By treating these dynamics as interconnected rather than isolated, the report helps decision-makers anticipate how changes in subsidy policy, standards adoption, and raw material pricing may alter competitive conditions, margin structures, and time-to-market expectations across different geographies and customer segments.
What the Report Delivers: Operational Intelligence for Concrete Decisions
This market research is built to support action, not just observation. Readers will find a structured body of content designed to feed directly into strategic planning processes, investment appraisals, and commercial execution plans. Key contents include:
- A rigorous historical reconstruction of market performance that establishes baseline credibility and identifies inflection points across the 2020-2025 period.
- A forecast model extending through 2032 that integrates growth drivers, constraints, and scenario considerations, enabling internal sensitivity testing rather than reliance on a single point estimate.
- Segmentation analysis that clarifies where system types, crop categories, and regional opportunities intersect with corporate capabilities and distribution strengths.
- Competitive profiling that maps strategic positioning, product portfolio depth, technology direction, and recent corporate activities for leading market participants.
- Market dynamics coverage that connects policy, standards, subsidy design, and input economics to adoption behavior and supply-side implications.
- Practical guidance for interpreting concentration metrics, evaluating partnership and M&A opportunities, and assessing where differentiation is most defensible in a maturing market.
Throughout, the report maintains a disciplined standard: it provides enough analytical depth to establish trust and credibility, while reserving the most granular segment-level data for the full publication. This design reflects a deliberate philosophy. High-level market direction and structural logic are essential for initial strategic alignment, but precise figures, sub-segment splits, and detailed regional breakdowns are most valuable when integrated into proprietary planning models. By accessing the complete report, decision-makers gain the full quantitative foundation required to benchmark internal assumptions, calibrate revenue targets, and prioritize resource allocation with confidence.
Why This Research Matters for 2026 Strategy
As organizations formulate their 2026 agendas, the Worldwide Agriculture Micro Irrigation System Market presents both opportunity and complexity. The convergence of sustained demand growth, increasing market concentration, accelerating technology integration, and evolving policy frameworks means that strategy cannot be built on anecdotal evidence or lagging indicators alone. Companies need a current, methodologically consistent view of where value is being created, how competitive pressure is shifting, and which structural trends will endure beyond short-term cycles.
This report is intended to serve as that reference point. It equips leadership teams with the context to evaluate market entry timing, assess the strategic fit of potential partnerships or acquisitions, interpret competitor moves within a broader trajectory, and align commercial execution with the demand realities of farmers, absentee landowners, cooperative bodies, and institutional agri-operators. Whether the objective is to expand geographic reach, deepen product differentiation, or improve go-to-market efficiency, the analysis provides a calibrated foundation for informed decision-making.
For executives who require the complete dataset, sub-segment breakdowns, regional modeling detail, and full competitive intelligence to finalize their 2026 plans, the full report offers the comprehensive intelligence necessary to act decisively. The macro trajectory is clear. The strategic value lies in translating that trajectory into precise, company-specific action. Our research is designed to make that translation possible.
For detailed analysis of this topic, please visit the official page: Worldwide Agriculture Micro Irrigation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


