



PW Consulting: PCM Metal Sheet Market to Hit $4.85B in 2025, Grow at 5.15% CAGR Through 2032

Navigating the 2026 Landscape: A Strategic Introduction to the Pre-Coated Metal (PCM) Sheet Market
The global Pre-Coated Metal (PCM) sheet market stands at a critical inflection point as we move through 2026. For executives, procurement leaders, and strategic planners, the ability to anticipate shifts in substrate pricing, coating technologies, and regional demand trajectories is no longer a luxury—it is a fundamental requirement for maintaining competitive advantage. This article serves as a strategic preview of our newly released comprehensive market research, offering a high-level view of the market forces defining the period from 2026 to 2032. The full report provides the granular intelligence necessary to transform these macro trends into actionable business decisions.
Our analysis is anchored in a robust historical framework spanning 2020 to 2025, which allows us to validate growth patterns and identify structural breaks before projecting forward. The market has demonstrated persistent expansion over this period, evolving from a base valuation of approximately 3,750.25 million USD in 2020 to an estimated 4,850.5 million USD in 2025. This trajectory underscores a resilient demand environment driven by sustained utilization in both household appliance manufacturing and construction sectors, even as the industry navigates fluctuating raw material costs and shifting regulatory expectations.
The 2026-2032 Growth Trajectory and Market Expansion
Looking ahead, the market is projected to follow a steady compound annual growth rate of 5.15 percent throughout the forecast horizon. This growth rate, while moderate, reflects the maturation of core application segments and the increasing sophistication of end-user requirements. The market size is expected to advance from approximately 5,157.81 million USD in 2026 to reach 6,893.69 million USD by 2032. This expansion is not merely a function of volume but is increasingly tied to value addition through advanced coatings, corrosion resistance warranties, and aesthetic customization.
It is important to contextualize this growth within the broader pricing environment. As of March 2026, benchmark pricing for hot-rolled coil steel in the Midwest reached 975 USD per short ton, reflecting a month-over-month increase of 2.1 percent. Furthermore, cold-rolled coil substrates, which are essential inputs for high-quality PCM production, maintain a significant premium of roughly 165 USD per short ton over hot-rolled counterparts. These input cost dynamics directly influence margin structures and pricing strategies for PCM manufacturers. Our research dissects how these cost pressures are being absorbed, passed through to downstream customers, or mitigated through process innovations and substrate substitution, such as the strategic use of aluminum or electro-galvanized steel where appropriate.
Segmentation Dynamics: Substrates, Applications, and Regional Flows
The PCM market is structurally defined by a diverse array of substrates and applications, each with distinct growth drivers and competitive intensities. The substrate landscape is dominated by galvanized steel, which continues to serve as the workhorse material for a wide range of applications due to its balance of cost, formability, and corrosion resistance. Aluminum occupies a significant secondary position, particularly in segments where weight reduction, non-magnetic properties, or specific aesthetic finishes are prioritized. Cold rolled steel also represents a critical substrate category, often selected for premium applications requiring superior surface quality and dimensional precision. The interplay between these material choices is becoming more complex as manufacturers respond to both cost volatility and performance demands.
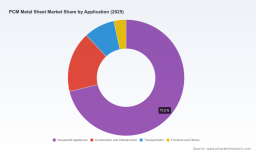
On the application front, household appliances remain the dominant consumption pillar, absorbing the largest share of PCM sheet utilization. This segment benefits from continuous product refreshes, urbanization trends, and the replacement cycle of major white goods. Construction and infrastructure form the second major pillar, where PCM sheets are used extensively in roofing, cladding, and architectural facades. The long-term corrosion warranties often associated with these products, sometimes extending decades, highlight the critical role of coating integrity and quality assurance. Transportation and furniture represent additional application vectors, each with specific technical requirements regarding formability, surface durability, and environmental exposure.
Regionally, the market exhibits pronounced concentration patterns that reflect underlying industrial capacity and consumption centers. Asia Pacific represents the most substantial market region, reflecting the dense concentration of appliance manufacturing, construction activity, and metal processing infrastructure. Europe and North America constitute significant demand centers with mature markets that emphasize premium finishes, sustainability certifications, and regulatory compliance. Latin America and the Middle East and Africa represent emerging and developing demand pockets where industrialization, infrastructure investment, and appliance penetration rates are gradually expanding the addressable market. Our report provides a detailed, granular breakdown of these regional flows, capacity allocations, and trade dynamics, enabling readers to pinpoint where growth is most likely to materialize and where competitive saturation may be intensifying.
Concentration Dynamics and Competitive Intensity
Market concentration data reveals a landscape that is consolidated yet contested. The top three players collectively account for approximately 42.15 percent of market revenue, while the top five players extend their share to 58.6 percent. This concentration profile indicates a market where scale advantages in coating lines, raw material procurement, and distribution networks are meaningful, but where significant opportunities remain for specialized players, regional champions, and niche technology providers. The presence of a broad competitive field means that differentiation through product performance, service reliability, and supply chain resilience is essential for sustaining market position.
Competitive Landscape: Key Players and Strategic Positioning
The competitive arena for PCM metal sheets spans a global roster of integrated steel producers, specialized coil coaters, and regional manufacturers. Each participant brings a distinct strategic profile, geographic footprint, and technical capability set. Understanding how these companies position themselves is critical for benchmarking, partnership evaluation, and competitive risk assessment.
Global Integrators and Brand Leaders
BlueScope, headquartered in Australia, has established a strong reputation through its COLORBOND prepainted steel portfolio, which targets both construction and industrial applications. The company's emphasis on durability and weather-resistant performance aligns with the long lifecycle expectations of building envelope and structural applications. Similarly, NSSMC (Nippon Steel & Sumitomo Metal Corporation) from Japan operates as a major producer of coated and pre-coated steel sheets, supplying high-performance PCM-grade materials to home appliance and construction markets. Its focus on advanced corrosion resistance and aesthetic finishes positions it as a supplier of choice for applications where surface quality and longevity are paramount.
ArcelorMittal, based in Luxembourg, leverages its global scale to supply pre-painted steel through coil coating processes for building and appliance uses. Its Galvalume and related pre-paint product lines are often backed by long-term corrosion warranties, reinforcing trust in roofing, siding, and fabrication markets where performance guarantees carry substantial commercial weight. POSCO, from South Korea, produces color-coated steel sheets and PCM for both appliances and construction. Notably, the company has advanced into differentiated product development, including PosART and antiviral PCM variants, which illustrate how coating technology innovation can open new value propositions beyond conventional corrosion protection.
Regional Specialists and China-Centric Capacity
A substantial portion of global PCM capacity and production activity is centered in China, where multiple manufacturers have scaled to serve both domestic demand and export channels. Baosteel (China Baowu Steel Group) stands as a large-scale producer of PCM metal sheets for home appliances and construction, offering extensive color-coated portfolios that support high-volume downstream manufacturing. Shanghai Metal Corporation supplies PCM steel with specified thickness ranges and zinc coating parameters, tailored to electric appliance applications such as refrigerators and washing machines, and utilizes imported cold rolling equipment to maintain process quality. Everesteel, also based in China with global export reach including Australia, specializes in PCM pre-coated metal sheets and pre-painted coils for appliances and construction. The company highlights custom color matching with tight tolerances, salt spray resistance performance, and substantial annual capacity, alongside ISO 9001:2015 certification, reflecting a service-oriented approach to quality assurance.
PCM Metal Sheet Market
Other notable participants in the China-centric ecosystem include Yieh Phui (China) Technomaterial, Shandong Guanzhou, HBIS New Material, Zhuhai Speedbird PVC Film Laminated Metal Sheet Co. Ltd., and Zibo Jingtai New Material Co., Ltd. Collectively, these manufacturers contribute to a highly competitive supply environment where production scale, coating line flexibility, and cost efficiency are key differentiators. Their presence reinforces Asia's role as both a production hub and a demand center, while also shaping global pricing dynamics through export availability.
European and Asian Process Specialists
ThyssenKrupp from Germany provides coated and pre-coated steel solutions across various sectors, including appliances, leveraging European engineering standards and process expertise. In Southeast Asia, PCM Processing (Thailand) Ltd., located in Chonburi, operates as a leading Thai manufacturer of pre-painted steel sheets, including PPGI and PPGL grades, meeting international standards. The company supplies high-performance prepainted coils and sheets for household electrical appliances and offers coil center processing and embossing capabilities, which add value through post-coating customization. Dongkuk Steel and JSW Steel further broaden the competitive field, with Dongkuk focusing on pre-coated metal sheets for home appliance and industrial applications, and JSW Steel supplying pre-coated and color-coated steel sheets for appliance and building uses. JFE Steel from Japan rounds out the competitive set with high-performance pre-coated metal sheets that emphasize corrosion resistance for appliance applications.
Recent Developments and Operational Signals
Recent operational activity among key players provides useful signals about capacity utilization, quality emphasis, and market engagement. PCM Processing (Thailand) Ltd. has shared updates during 2025 reflecting ongoing facility activity and community engagement, including events and certification-related attendance, indicating sustained operational momentum and compliance focus. Everesteel has reported a zero rust claims record across more than 3,000 containers shipped in 2024, supported by ongoing lab-verified color matching services, and has released a 2025 pre-coated metal catalog covering a full range of PCM coils and film-coated metals. These developments highlight the growing importance of verifiable quality performance, consistent color matching, and catalog-driven product standardization in securing and retaining downstream contracts.
Industry Context: Compliance, Certification, and Substrates
The commercial viability of PCM products is closely tied to compliance and certification frameworks. Pre-coated metal products typically comply with ISO 9001 quality management standards and environmental directives such as RoHS. Third-party certifications from organizations including SGS, Bureau Veritas, and Intertek are commonly provided to demonstrate quality and compliance for appliance and construction applications. These certifications are not merely procedural; they function as trust mechanisms that reduce procurement risk for downstream manufacturers and construction fabricators. Additionally, environmental product declarations and lifecycle documentation are increasingly relevant, aligning PCM offerings with broader sustainability expectations in building and appliance sectors.
From a technical standpoint, PCM manufacturing generally relies on base substrates that include cold-rolled steel, electro-galvanized steel, and hot-dip galvanized steel with zinc coatings in the range of 40 to 150 grams per square meter, along with aluminum options. These substrate choices influence coating adhesion, formability, corrosion behavior, and final product cost. The availability and pricing of these substrates, combined with coating line capabilities, shape the product mix that manufacturers can offer and the value they can capture. Our research examines how substrate selection strategies are evolving in response to cost pressures, performance requirements, and customer specifications.
Why This Research Matters for 2026 Decision-Making
The strategic value of this market research lies in its ability to connect macro trends with operational implications. For sourcing and procurement teams, understanding the interplay between substrate pricing, coating technology, and regional capacity is essential for mitigating cost volatility and securing reliable supply. For product development and engineering leaders, the report provides context on coating innovations, corrosion performance benchmarks, and aesthetic customization trends that can inform material selection and design-for-manufacturing decisions. For competitive intelligence and corporate strategy functions, the analysis of market concentration, player positioning, and recent operational developments offers a framework for evaluating threats, identifying partnership opportunities, and assessing market entry or expansion feasibility.
Phase Change Material (PCM) Market
Importantly, this research is designed to support decisions that require precision. While this article outlines the broad contours of the market and the strategic themes defining 2026, the full report delivers the detailed segmentation data, regional breakdowns, application splits, and company-level assessments that executives need to quantify opportunity and risk. The complete dataset enables readers to move beyond directional insight and into scenario planning, margin modeling, and prioritization of growth initiatives.
What the Full Report Unlocks
The complete PCM Metal Sheet Market research provides an integrated view across multiple dimensions. It details the segmentation structure across regions, substrates, and applications, allowing readers to identify which segments are driving growth and which are experiencing maturation or intensification. It includes comprehensive profiles of key companies, with headquarters, product focus, and strategic context, enabling benchmarking and targeted competitive analysis. It incorporates recent developments and operational signals that reflect real-time market behavior, supporting a timely and nuanced interpretation of industry dynamics.
In addition, the report embeds industry context around raw material pricing, substrate specifications, and regulatory compliance, ensuring that strategic conclusions are grounded in the operational realities of PCM manufacturing and procurement. By combining historical data validation with a forward-looking forecast through 2032, the research offers a durable reference point for planning cycles that extend beyond the current fiscal year.
Conclusion: Positioning for Informed Action
The Pre-Coated Metal sheet market in 2026 presents a landscape shaped by steady growth, material cost dynamics, evolving substrate strategies, and a competitive field that spans global integrators and specialized regional manufacturers. Success in this environment depends on access to accurate, detailed, and actionable intelligence. This article has outlined the strategic themes and market structure that define the current period, but the depth required for confident decision-making resides in the full research publication. We invite stakeholders to access the complete report to obtain the granular market size data, segmentation breakdowns, competitive profiles, and contextual analysis needed to navigate the PCM market with clarity and precision.
For detailed analysis of this topic, please visit the official page: PCM Metal Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


