



PW Consulting: Global Digital Movie Projector Market to Hit $7.18B by 2032, 7.21% CAGR

Strategic Intelligence for the Next Era: Inside the Worldwide Digital Movie Projector Market Research
The global cinema exhibition landscape is undergoing a structural transformation. As exhibition chains navigate post-recovery attendance patterns, technology refresh cycles, and escalating content quality expectations, the digital movie projector market has emerged as a critical battleground for competitive positioning, capital allocation, and long-term commercial strategy. PW Consulting recent comprehensive study on the Worldwide Digital Movie Projector Market delivers a rigorously validated, forward-looking intelligence framework designed specifically for enterprise decision-makers operating in 2026 and beyond. This market research introduction outlines the strategic architecture of the report, highlights the market mechanics that will define competitive outcomes, and demonstrates how leadership teams can translate macro momentum into executable growth strategies.
The analysis spans a five-year historical baseline from 2020 through 2025, extended by a seven-year forecast horizon reaching 2032. This temporal architecture enables stakeholders to calibrate investment cycles, anticipate supply chain inflection points, and evaluate how exhibition infrastructure rollouts align with broader content distribution roadmaps. By anchoring strategic planning in validated historical trajectories and systematically modeled forward scenarios, the report equips executives with the analytical discipline required to navigate an industry characterized by rapid technological substitution and evolving geographic demand patterns.
Macro Market Trajectory and the Strategic Imperative for 2026
The worldwide digital movie projector market has demonstrated sustained expansion across the analyzed historical window. Revenue scaled from approximately 1,850.4 million USD in 2020 to 4,412.5 million USD by the 2025 base year, reflecting a decisive shift in global exhibition infrastructure as traditional lamp-based systems gave way to higher-efficiency illumination architectures and exhibitors modernized screens to meet premium format requirements. The market is projected to continue its upward trajectory through the forecast period, reaching 7,183.43 million USD by 2032, supported by a compound annual growth rate of 7.21 percent.
For executive teams, this growth profile carries several strategic implications. First, the expanding addressable market signals that capital deployment into projection technology is no longer a maintenance exercise but a growth-oriented investment. Second, the pace of expansion creates a competitive window for manufacturers and system integrators to capture share before market saturation intensifies in mature exhibition corridors. Third, the forecast horizon underscores the importance of modular product roadmaps, as exhibitors increasingly demand flexible deployment architectures that accommodate varying screen sizes, ambient light conditions, and operational budgets.
Amid this trajectory, industry participants must also contend with structural dependencies that influence supply resilience and cost structuring. High-performance laser diodes and solid-state laser components rely on rare earth materials, with concentrated sourcing networks introducing potential vulnerabilities into manufacturing pipelines. Simultaneously, standardized technology licensing frameworks shape which manufacturers can commercially deploy certain digital cinema architectures, reinforcing industry concentration and influencing partnership strategies. Decision-makers who model these dependencies explicitly will be better positioned to secure component availability, negotiate supplier terms, and design product portfolios that remain viable under shifting raw material dynamics.
Report Architecture: Actionable Intelligence for Executive Decision-Making
The research is structured to convert complex market signals into operational clarity. Rather than presenting abstract market summaries, the publication delivers a multi-layered intelligence framework that supports pricing strategy, R&D prioritization, regional rollout planning, and partnership evaluation. The report content is designed for cross-functional use, enabling product leadership, commercial teams, and strategy offices to align around a unified evidence base.
Core analytical components include:
- A detailed historical reconstruction of market performance across key valuation years, enabling trend validation and scenario anchoring
- A forward-looking forecast model extending through the end of the decade, with explicit assumptions around adoption pacing, technology transitions, and exhibition upgrade cycles
- A structural segmentation analysis that disentangles the primary commercial axes shaping demand, allowing stakeholders to isolate growth drivers and assess portfolio fit across distinct product architectures
- A competitive positioning review that examines strategic moves by leading manufacturers, highlighting product launches, technology introductions, and market expansion patterns that indicate where industry momentum is accumulating
- A qualitative and quantitative assessment of market concentration, providing context for pricing power, barrier-to-entry dynamics, and partnership considerations
- An integrated review of technology dependencies, regulatory and licensing frameworks, and supply chain sensitivities that can materially affect cost structures and deployment timelines
Each analytical module is engineered to support concrete decision-making. Exhibitors can use the findings to sequence capital upgrades across venue portfolios. Manufacturers can identify where next-generation illumination systems and resolution formats are gaining traction relative to legacy configurations. Component suppliers and service providers can map demand patterns to anticipate aftermarket service needs, maintenance cycles, and retrofit opportunities. By maintaining consistency between historical analysis and forward projection, the report reduces ambiguity in budgeting and strategic planning, allowing organizations to commit resources with greater confidence.
Competitive Architecture and the Battle for Next-Generation Projection
The digital cinema projector market is characterized by a concentrated supplier base, with leading manufacturers controlling a substantial share of global revenue. Recent competitive activity demonstrates how incumbents are reinforcing their positions through illumination innovation, format differentiation, and targeted geographic expansion. Understanding these moves is essential for any organization evaluating partnership opportunities, competitive response strategies, or product development priorities.
Digital Light Processing (DLP) Projector Market
Barco NV continues to position itself as a leading provider of laser-based digital cinema projectors, emphasizing unified next-generation product families that balance performance with operational simplicity for commercial theaters. Its focus on high-brightness RGB laser systems reflects a broader industry shift toward illumination architectures that enhance color volume, consistency, and brightness stability across varied screening environments. Christie Digital Systems maintains a strong presence through its high-performance cinema portfolio, including the CineLife+ series and RGB laser platforms designed for diverse screen sizes. The company has also built recognition around advanced HDR and Dolby Vision-aligned solutions, reinforcing its association with premium image performance and award-recognized engineering.
NEC Display Solutions, operating through Sharp NEC, delivers digital cinema projectors built on DLP technology, prioritizing high brightness and extended operational lifespan for theatrical deployments. Sony Corporation remains active in professional projection ecosystems, bringing SXRD and DLP lineage to high-end cinema contexts while adjusting its portfolio footprint in response to broader segment evolution. The strategic behavior of these firms illustrates a market where differentiation increasingly depends on illumination technology, optical performance, service infrastructure, and the ability to align hardware with emerging content delivery standards.
Recent corporate activity reinforces the pace of innovation. In January 2025, Christie Digital introduced new CineLife+ RBe series projectors featuring Phazer illumination technology designed to improve image performance on small, high-gain screens, alongside Jazz Series 1DLP laser projectors built around Texas Instruments 0.8-inch HEP DMD components for improved color, contrast, and a more compact chassis. Later that year, Christie expanded its cinema lineup with RGBH projectors using CineLife+ electronics and Phazer illumination for small to mid-size screens. In January 2026, Texas Instruments showcased new DMD chipsets and controllers enabling higher brightness, improved native contrast, 4K/120 fps support, and compact high-lumen projector designs at CES 2026. These developments signal an industry moving rapidly toward higher resolution, higher brightness, and more efficient optical architectures, while also compressing form factors to support flexible installation scenarios.
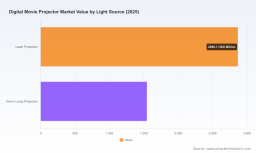
Alongside product momentum, regulatory and technical licensing structures continue to shape competitive boundaries. DLP Cinema technology for digital cinema projectors is licensed by Texas Instruments primarily to Barco, Christie, and NEC, reinforcing a linked ecosystem of hardware developers operating under shared optical and digital standards. At the same time, laser illumination systems accounted for an estimated 55 to 68 percent of cinema projector shipments from major manufacturers in 2025, highlighting how quickly illumination technology is reshaping shipment composition and buyer preferences.
Technology Transitions, Critical Materials, and Regional Demand Signals
Technology migration is one of the most consequential forces shaping product strategy. The shift from xenon lamp projection toward laser projection is not simply a performance upgrade; it reflects a broader reconfiguration of total cost of ownership, maintenance intervals, brightness stability, and content compatibility. As exhibitors evaluate whether to replace legacy units or expand screen capacity, the choice of light source becomes a strategic decision with implications for energy consumption, service logistics, and long-term operational expenditure.
Resolution format adoption further complicates the decision environment. High-resolution projection is increasingly associated with premium large-format experiences, upgraded contractual expectations from studios, and audiences accustomed to higher detail levels. As 4K-class formats gain share relative to 2K configurations, manufacturers and exhibitors must consider how product roadmaps align with content pipelines, screen dimensions, and budgetary constraints. This transition is not uniform across all venue classes, which makes segmentation-based planning essential for identifying where premium upgrades will generate the strongest return and where cost-efficient reliability remains the primary buying criterion.
Supply-side resilience is equally important. The dependency on rare earth materials within high-performance laser diode and solid-state laser supply chains introduces concentration risk that can affect lead times, pricing, and continuity of supply. Organizations that incorporate supplier diversification, inventory buffering, and long-term sourcing agreements into their strategy are better insulated against volatility. This is particularly relevant for manufacturers scaling laser-based portfolios and for exhibitors planning multi-year upgrade programs that depend on predictable equipment availability.
Regional demand patterns add another layer of strategic complexity. While mature exhibition markets continue to refresh installed bases and pursue premium format upgrades, select growth regions are accelerating infrastructure build-out through large-scale procurement initiatives. Geopolitical and national development programs can generate concentrated demand spikes, creating both opportunity and execution risk. For example, Vision 2030 initiatives in Saudi Arabia have driven significant demand for laser DLP cinema projectors, with Christie securing a contract for more than 420 units in early 2026. Such developments illustrate how government-backed entertainment and tourism objectives can abruptly reshape regional procurement priorities, rewarding manufacturers and partners capable of delivering at scale with technical compliance and localized support.
Strategic Applications of the Research for 2026 Decision-Making
The strategic value of this research lies in its ability to convert market complexity into decision-ready intelligence. For manufacturing leadership, the report supports product portfolio calibration, helping teams determine where to emphasize laser illumination development, resolution upgrades, and compact high-brightness architectures. For exhibition operators, it informs venue-level upgrade sequencing, enabling smarter prioritization of screens that will generate the strongest audience response and revenue uplift from new projection systems. For investors and corporate strategy teams, it provides a structured view of concentration dynamics, competitive moats, and technology dependency risks that influence valuation assumptions and partnership selection.
In practice, the research can be applied across several critical planning dimensions:
- Assessing whether near-term capital should prioritize new product introductions, service expansion, or market-specific geographic development
- Identifying which technology transitions are moving from early deployment to mainstream adoption and how quickly incumbent portfolios must adapt
- Evaluating competitive vulnerability in segments where illumination, resolution, or brightness leadership is becoming a decisive purchase factor
- Modeling supply chain exposure related to laser components and rare earth dependencies, then aligning procurement and production strategies accordingly
- Interpreting regional demand signals to determine where large-scale opportunities may emerge and what local support, certification, or partnership capabilities are required to win
By connecting historical performance, forward forecast logic, and competitive activity in one integrated analysis, the study helps organizations avoid fragmented decision-making. Instead of reacting to individual product launches or isolated regional orders, executives can evaluate how multiple forces interact and shape the next cycle of market leadership.
Why the Full Report Matters Now
Market intelligence is most valuable when it does more than describe what has already occurred. It must clarify what is likely to happen, where competitive advantage will be created, and which decisions should be made before the market reallocates share. The Worldwide Digital Movie Projector Market research is designed to meet that standard. It integrates validated historical data, a disciplined forecast framework, and a detailed review of technology, competitive, and regional dynamics into a single strategic reference point.
Because the full report contains the segmented breakdowns, detailed scenario assumptions, competitive benchmarking, and operational recommendations that executive teams need to build precise plans, it is structured as a comprehensive decision-support asset rather than a high-level summary. Readers who require exact regional valuations, application-level market allocations, and granular resolution- and light-source-level insights will find the complete dataset essential for pricing, forecasting, and investment decisions.
Worldwide Digital Movie Projector Market
For leadership teams preparing for 2026 and the forecast years ahead, the complete research delivers the level of clarity required to act with confidence. The market is expanding, the technology base is shifting, and competitive intensity is rising. Organizations that ground their strategy in rigorous, forward-looking intelligence will be best positioned to capture growth, manage supply and technology risk, and build durable advantage in a rapidly evolving exhibition technology landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Movie Projector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


