



PW Consulting: Global Dispute & Arbitration Market to Hit USD 38,238.2 Million by 2032

The Global Dispute Advisory and International Arbitration Market 2026–2032: Strategic Intelligence for Enterprise Decision-Making
The mechanics of global commerce are shifting beneath the feet of corporate boards. Disputes that once settled in regional courts now traverse continents, implicate sovereign interests, and unfold under increasingly complex digital and regulatory architectures. For enterprises operating across borders, the question is no longer whether disputes will arise, but how quickly, how expensively, and under what procedural conditions they will be resolved. PW Consulting's Worldwide Dispute Advisory and International Arbitration Market research, newly released and anchored in a comprehensive dataset spanning 2020 through a forecast period extending to 2032, offers a structured, evidence-based vantage point for executives navigating this terrain. This article previews the strategic architecture of the report, outlines the operational intelligence it contains, and explains why the 2026 decision window demands more than intuition.
A Market in Structured Expansion: Reading the Trajectory
The global dispute advisory and international arbitration market has completed a sustained growth cycle and is entering a phase of accelerated maturity. Drawing on historical records from 2020 through the base year of 2025 and extending forecast projections to 2032, the study maps a revenue trajectory that reflects both organic demand expansion and the structural professionalization of dispute resolution services. Over the historical window, the market advanced from approximately 18.25 billion to 24.85 billion, demonstrating a compound trajectory that outpaces general professional services benchmarks. The forward view projects further expansion through 2032, with the overall market scale anticipated to climb meaningfully as cross-border transaction volumes, infrastructure commitments, and energy-sector investments continue to generate complex, multi-party disputes.
At the core of the forecast lies a compound annual growth rate of 6.35 percent across the projection horizon. This rate is not a generic curve fitted to sector averages; it is derived from institutional filing patterns, jurisdictional diversity indicators, service-type demand shifts, and regional deployment dynamics documented throughout the historical period. For strategy and finance leaders, the implication is clear: annualized planning for dispute-related contingencies, external counsel budgeting, and risk advisory partnerships must account for a market that is consistently appreciating rather than fluctuating at the mercy of discrete case spikes. The report embeds this trajectory within sensitivity overlays that account for jurisdictional case-load variability, macroeconomic stress scenarios, and shifts in institutional rule-making, providing decision-makers with a disciplined range rather than a single-point estimate.
What the Report Delivers Beyond the Top-Line Numbers
Market size and growth rates are necessary scaffolding, but they are not the substance of strategic action. The research is built around actionable intelligence designed to translate market movement into internal planning, vendor selection, and risk posture adjustments. The report structure spans multiple analytical dimensions that practitioners can operationalize immediately.
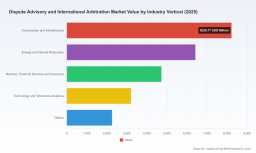
The service-type analysis dissects demand across forensic accounting and damage valuation, technical and delay analysis, legal advisory and counsel, and strategic advisory and risk management. Each category is examined not as an isolated line item but as a function of dispute complexity, evidentiary burden, and the procedural stage at which organizations most frequently seek external support. The sectoral breakdown maps activity across construction and infrastructure, energy and natural resources, banking and financial services, technology and telecommunications, and a residual category capturing emerging and cross-cutting engagements. This vertical lens is paired with regional deployment patterns that reveal where institutional seats, party domiciles, and expert networks are concentrated, allowing enterprises to calibrate geographic resource allocation against their own transaction footprints.
Beyond segmentation, the report integrates procedural and structural intelligence that frequently escapes generic market summaries. The analysis incorporates developments in data privacy and cybersecurity governance within arbitration contexts, including the application of frameworks such as GDPR Article 32 and guidance from joint task forces addressing electronic evidence and confidentiality obligations. It also examines how specialized human capital, seasoned arbitration counsel and subject-matter experts, continues to function as a primary operational cost driver, and how leading practices are responding through integrated global teams designed to manage high-value, multi-jurisdictional matters more efficiently. These threads are not decorative; they form the connective tissue between market scale and the practical mechanics of dispute readiness.
Competitive Architecture and the Cost of Positioning
The international arbitration ecosystem is defined by a distinctive concentration pattern. The market is not dominated by a handful of overwhelming incumbents; rather, it reflects a moderately fragmented structure in which concentrated leadership coexists with deep specialization across boutiques, global full-service practices, and advisory firms that bring forensic, valuation, and expert-witness capabilities into arbitration contexts. The research documents this arrangement through concentration indicators that illustrate the share of activity captured by leading firms, revealing a landscape where scale advantages in cross-border case management exist alongside highly differentiated practice strengths in energy, infrastructure, investor-state, and commercial treaty matters.
Several firms anchor this competitive field, each with identifiable strategic positioning. Freshfields Bruckhaus Deringer operates with a pronounced emphasis on pre-contentious strategic advice and representation across major institutions, with distinctive depth in energy, infrastructure, and public international law. White & Case maintains a global arbitration platform covering commercial, investor-state, and enforcement proceedings, complemented by recurring user-preference research that informs how parties experience institutional processes. Herbert Smith Freehills Kramer delivers integrated global arbitration services with particular momentum in Asia-Pacific high-value mandates spanning energy, construction, and corporate sectors. King & Spalding continues to specialize in arbitration and litigation for energy, infrastructure, and commercial disputes, frequently positioned among top-tier global practices in both commercial and treaty work.
Debevoise & Plimpton's profile reflects high-value commercial and investor-state representation with recognized strength in energy sector disputes and public international law. Three Crowns LLP operates as a boutique exclusively focused on international arbitration and public international law, providing counsel and advocacy in high-stakes matters where procedural precision is paramount. Quinn Emanuel Urquhart & Sullivan has been recognized for its international arbitration representation across commercial, construction, energy, and sovereign disputes, reflecting a practice built around intensive advocacy under major institutional rules. Baker McKenzie offers a full-range arbitration advisory and representation platform covering investor-state, commercial, energy, mining, and post-M&A disputes across a broad geographic network. Squire Patton Boggs brings strength in energy, commodities, and investment treaty arbitrations, while Cleary Gottlieb Steen & Hamilton contributes both complex cross-border dispute handling and recurring analytical publications on arbitration trends, including emerging issues such as artificial intelligence and tariff-related disputes. PwC's dispute advisory footprint, encompassing forensic analysis, valuation, expert witness support, and strategic advice, completes the competitive picture by illustrating how accounting and advisory capabilities intersect with legal advocacy in arbitration contexts.
The report does not stop at firm profiles. It maps how these players interact with institutional activity, jurisdictional preferences, and service-type demand shifts, allowing enterprises to assess not only who is active but where capability aligns with the nature of their likely exposure.
The 2026 Context: Forces Reshaping Dispute Resolution Decision-Making
The most valuable intelligence in a market study is not merely where the market has been, but what is changing in real time. A series of recent institutional and practice-level developments illustrates the tempo of transformation that the 2026 decision window must accommodate.
At the institutional level, preliminary statistics released in early 2026 show that international dispute resolution continues to operate at exceptional scale and geographic breadth. One major arbitral institution reported 881 new cases filed under its arbitration rules in the prior year, with more than 2,500 parties originating from 147 jurisdictions and procedural seats located across 123 cities in 70 countries, alongside an aggregate pending case value approaching 299 billion. These figures are more than institutional metrics; they signal a dispute environment in which party diversity, multi-seat logistics, and high aggregate exposure are structural features rather than temporary anomalies. Complementary reporting from another leading arbitral institution showed similarly international patterns in its casework, with the substantial majority of cases involving parties from more than 100 jurisdictions, reinforcing the globalized character of contemporary arbitration practice.
eDiscovery Market
Rankings and recognition developments further clarify competitive standing while highlighting the criteria by which market participants are evaluated. Chambers and Partners' 2026 global rankings recognized multiple firms and individuals as market leaders or top-tier practitioners in international arbitration, with named recognition for firms including White & Case and King & Spalding. Industry awards have likewise highlighted specific practices for sustained excellence; one firm received International Arbitration Team of the Year recognition at a major UK awards program for its global practice in complex disputes. These recognitions, while not substitutes for fit assessment, provide a structured reference point for understanding where institutional credibility and peer evaluation converge.
Equally significant are the thematic forces now reshaping arbitration workflows. Macroeconomic and geopolitical turbulence continues to elevate cross-border friction, while technological breakthroughs, particularly the integration of artificial intelligence for case analysis and evidence review, are altering how disputes are prepared, managed, and adjudicated. Cleary Gottlieb's 2026 trends analysis documents a surge in commercial arbitrations, renewed attention to enforcement against sovereigns, and the growing salience of tariff-related disputes alongside cryptocurrency and regulatory questions. At the same time, emerging guidance on data protection, including the work of joint task forces addressing electronic evidence and confidentiality within arbitration, underscores that procedural compliance is becoming as strategically consequential as substantive advocacy. ESG considerations are also exerting greater influence on dispute posture, stakeholder expectations, and the reputational calculus surrounding resolution choices.
Translating Intelligence into 2026 Enterprise Decisions
For boards, general counsel, risk leaders, and corporate development teams, the strategic value of this research lies in its capacity to convert market behavior into decision architecture. The report is designed to support several concrete planning functions that 2026 demands.
Worldwide Dispute Advisory and International Arbitration Market
First, it enables more disciplined external engagement strategy. By linking service-type demand to sectoral exposure and regional deployment, enterprises can align counsel selection, forensic and valuation partnerships, and strategic advisory retainers with the dispute profiles most likely to arise from their transaction portfolios. Second, the concentration and competitive analysis supports vendor diversification and escalation planning, helping organizations avoid over-reliance on any single practice cluster while identifying where integrated global teams and boutique specialization each offer distinct advantages. Third, the institutional and procedural intelligence provides a basis for calibrating internal dispute readiness: evidentiary protocols, data-handling standards, cross-border seat considerations, and the operational implications of AI-assisted review and tariff-related compliance questions can be anticipated rather than improvised after a filing has begun.
The study also frames cost and timeline expectations more realistically. Because specialized human capital remains a primary cost driver, and because institutional activity continues to reflect high internationality and high aggregate exposure, enterprises benefit from modeling dispute-related expenditure as a recurring strategic line item rather than an episodic surprise. The report's forward trajectory, embedded in sensitivity analysis and anchored by historical-to-forecast continuity, gives finance and legal leadership a defensible basis for budgeting, reserving, and insurance calibration across the 2026–2032 window.
Where the Full Intelligence Resides
This overview establishes the why and the how of the report, but the decisive detail lives in the complete analysis. The full PW Consulting Worldwide Dispute Advisory and International Arbitration Market research contains the segmented operational breakdowns, the jurisdictional and institutional mappings, the competitive positioning matrices, and the forward scenario overlays that executives need to operationalize the themes summarized here. The report's segmentation detail, service-type dynamics, vertical demand distribution, and regional deployment patterns are presented with the granularity required for hands-on planning, while the concentration structure and firm-level profiles are analyzed in relation to service fit, geographic reach, and procedural capability rather than as static rankings.
For decision-makers preparing for the 2026 operating year and the forecast horizon beyond it, the complete study functions as a reference system for external engagement design, risk budgeting, and dispute-readiness investment. The macro trajectory and the 2026 institutional and practice developments provide the context; the full segmentation, concentration analysis, and firm-specific intelligence provide the decision-grade depth. PW Consulting has structured the research to support precisely that transition from awareness to action, and the complete report is available for teams that need to move from strategic overview to implementation-ready insight.
For detailed analysis of this topic, please visit the official page: Worldwide Dispute Advisory and International Arbitration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


