



PW Consulting: Indirect Auto Finance Market to Hit $474 Billion by 2032 at 6.85% CAGR

Navigating the Indirect Auto Finance Landscape: Strategic Intelligence for 2026 and Beyond
The automotive retail ecosystem is undergoing a structural transformation, and at the center of this shift lies the indirect auto finance market. For executives, investors, and policy strategists, understanding the mechanics of dealer-originated lending is no longer optional. It is a prerequisite for capital allocation, product development, and competitive positioning. Our latest market research delivers a comprehensive, data-rich map of this sector, designed to translate macroeconomic signals and regulatory friction points into actionable decision frameworks for the 2026 to 2032 horizon.
This article serves as a strategic preview of the full study. It outlines the analytical architecture, highlights the most critical market dynamics that will define the next planning cycle, and explains how leadership teams can leverage the full publication to build resilient, forward-looking strategies. While we provide verified high-level metrics and structural insights here, the granular segmentations, competitive benchmarking matrices, and scenario-weighted forecast models remain exclusive to the complete report. Readers seeking the complete intelligence suite are directed to the source page, where the full dataset, interactive visualizations, and executive briefs are available for immediate deployment.
Indirect Auto Finance Market
The Structural Pulse of the Market: Size, Trajectory, and Concentration
Indirect auto finance—where dealerships originate retail installment contracts and dealer floorplan facilities on behalf of third-party lenders—has cemented its role as the dominant distribution channel for vehicle credit. Our historical reconstruction from 2020 through 2025 documents a sector that expanded from approximately 168.45 billion USD in 2020 to 298.5 billion USD in 2025, reflecting both the post-pandemic vehicle procurement surge and the sustained preference for dealer-mediated credit origination. The momentum carries into the forecast window, with the market projected to reach roughly 322.02 billion USD in 2026 and to continue its ascent toward 474.0 billion USD by 2032.
The compound annual growth rate across the forecast period is estimated at 6.85 percent, a pace that signals durable expansion rather than a cyclical rebound. This trajectory is shaped by enduring consumer behavior, dealer economics, and lender appetite for originated credit, even as macro headwinds introduce episodic demand volatility. Industry analysis indicates a modest contraction in overall auto loan originations expected for 2026, driven by affordability constraints and elevated vehicle pricing. Yet indirect channels remain structurally embedded, and the addressable market continues to scale as financing penetration deepens across both new and pre-owned vehicle transactions.
Concentration patterns underscore the strategic importance of channel relationships. The market is moderately consolidated, with the top three participants holding an estimated 38.5 percent share and the top five capturing approximately 52.3 percent. This structure creates a layered competitive field: large captives and scaled banks anchor the prime and near-prime corridors, independent finance companies extend reach into non-prime segments, and dealer networks operate as the critical gatekeepers of origination volume. Understanding how these layers interact—and where margin pools and risk asymmetries emerge—is central to any credible market entry, partnership, or portfolio strategy.
How the Report Is Structured: Turning Complexity into Decision-Ready Intelligence
The full study is built around practitioner needs. Rather than presenting a static snapshot, the report constructs a multi-layered analytical model that links segment dynamics to strategic choices. The architecture is organized to support scenario planning, competitive response design, and risk-weighted growth planning across the 2026 to 2032 period.
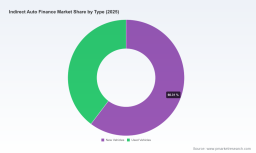
At the foundation, the report provides a disciplined segmentation framework that disaggregates the market along operationally meaningful axes. It examines regional dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, and it separates new vehicle financing from used vehicle financing to reflect different credit profiles, margin structures, and dealer behavior. The application lens distinguishes passenger vehicles from commercial vehicles, capturing divergent underwriting logic, utilization patterns, and lender tolerance for risk. Each dimension is mapped to volume trends, channel economics, and lender positioning, allowing readers to isolate where growth is most durable and where competitive intensity is rising fastest.
Beyond segmentation, the study delivers operational and strategic content designed for immediate use. These include dealer network influence mapping, lender origination economics, underwriting evolution in digital and hybrid processes, floorplan financing dynamics, and lease-versus-loan mix considerations for captives and independents. The report also evaluates channel conflict and cooperation between banks, credit unions, captive arms, and independent finance companies, with specific attention to how dealer partnerships shape approval speed, pricing competitiveness, and customer experience. Where relevant, the analysis connects these themes to portfolio performance indicators, delinquency sensitivities, and the implications of shifting credit standards.
The competitive profiling section does not simply list companies; it situates them within the market’s operational logic. Profiles address corporate footprint, financing philosophy, channel strategy, and competitive differentiation, enabling readers to assess where incumbents are defending share, where they are vulnerable, and where whitespace may exist for new entrants or partnership models. The report balances the perspective of major non-captive providers, captives anchored in manufacturer brands, and large bank-based auto lenders, and it includes specialized independents that target specific credit tiers.
Competitive Architecture: Captives, Banks, and the Independent Layer
The competitive field is best understood as a system of interdependent roles rather than a simple brand ranking. Captive finance arms—organizations tied closely to original equipment manufacturers—operate as strategic instruments of retail impact, brand loyalty, and inventory velocity. Major captives provide indirect financing through their respective dealership networks, combining retail installment contracts with lease options and, in several cases, dealer floorplan support. Their strategic advantage lies in the ability to align financing incentives with brand mix, model lifecycle, and promotional cadence, making them deeply embedded in the commercial logic of vehicle sales.
Finance Lease Market
Non-captive lenders occupy a complementary but distinct position. Large banks and diversified consumer finance institutions leverage dealer relationships to originate indirect auto loans at scale, emphasizing competitive rates, digital approval workflows, and integration with broader retail and commercial banking relationships. These institutions benefit from balance sheet capacity, data infrastructure, and cross-sell potential, and they continue to gain relevance in dealer-originated volume as dealer finance debt expands. Their operational focus increasingly centers on speed of decisioning, omnichannel experience, and risk-based pricing precision.
Independent finance companies add a third dimension to the landscape, often concentrating on non-prime and specialty segments where underwriting nuance and dealer trust are decisive. These players depend on deep relationships with franchise and independent dealerships, flexible contract structures, and targeted credit strategies. Their growth is closely tied to dealer willingness to forward contracts, local market conditions, and the relative cost of funding. In this ecosystem, competitive advantage is less about scale alone and more about channel intimacy, underwriting alignment, and the ability to absorb risk in segments that larger lenders may underweight.
The strategic implication for market participants is clear. Pricing, product design, and origination strategy must be calibrated to the segment, the dealer type, and the credit tier. Market share gains are often won through the quality of dealer partnerships, the reliability of funding, and the credibility of underwriting—not through marketing alone. Leaders need a precise reading of where each competitor is positioned, what channel leverage it holds, and how its economics shift when rate environments, inventory conditions, or regulatory definitions change.
Market Dynamics and the 2026 Decision Environment
Current dynamics are reshaping both opportunity and constraint. A recurring theme across recent industry analysis is the continued dominance of the indirect channel, with a substantial majority of auto loans originated through dealerships that forward contracts to banks, credit unions, and finance companies. This concentration of origination in dealer networks elevates the strategic value of channel relationships and underscores the importance of lender readiness in terms of speed, flexibility, and consistent funding.
At the same time, the distribution of share is evolving. Recent analysis indicates that banks and non-captive lenders are gaining ground in dealer-originated indirect auto loans, with dealer finance debt rising more than 20 percent year-over-year in one widely cited measurement. This trend reflects the interplay of funding availability, underwriting technology, and dealer preferences for lender reliability. It also signals that indirect finance is not a static monopoly of any one category; the market is contested, and competitive positioning can shift as dealers recalibrate their panel of lenders.
Regulatory development is another force that demands strategic attention. Policy activity around nonbank auto finance participants has accelerated, including discussions of larger participant definitions and adjustments to origination thresholds that determine regulatory footprint. Related legal interpretations are also in motion, including guidance that affects how disparate impact claims are understood under fair lending frameworks. These developments do not merely create compliance obligations; they alter the calculus of market entry, product design, portfolio scaling, and the cost of operating across prime and non-prime segments. Organizations that build regulatory foresight into their planning will be better positioned to adapt product structures, risk appetite, and geographic footprint without losing momentum.
Consumer affordability and price levels introduce a further layer of complexity. Forecasts for 2026 point to a modest decline in overall auto loan originations, reflecting affordability pressure and elevated car prices. This environment rewards precision: lenders and dealers that rely on broad-volume assumptions may find that marginal growth requires sharper segmentation, more granular pricing, and more disciplined risk selection. For captives, the challenge includes managing mix, incentives, and lease penetration in a way that protects both retail demand and portfolio health. For independents, the challenge is to maintain dealer loyalty and credit performance in segments where rate sensitivity and repayment risk move together.
Why This Research Matters for 2026 Strategy
The strategic value of the full report lies in its ability to convert a complex, multi-actor environment into a usable operating map. For leadership teams, the study answers several questions that directly influence 2026 decisions.
- Where is durable growth most likely to come from across regions, vehicle types, and application segments, and how should capital and product effort be prioritized accordingly?
- How should organizations interpret the evolving balance between captives, banks, credit unions, and independent lenders when designing partnership strategies, dealer panels, and origination targets?
- What operational capabilities are most decisive in a market where digital approval, dealer trust, funding stability, and risk-based pricing determine competitive outcomes?
- How do regulatory shifts around larger participant definitions, origination thresholds, and fair lending interpretation change the risk-reward calculus for scaling portfolios or entering new segments?
- In an environment of affordability constraints and elevated vehicle prices, how can organizations protect volume while preserving credit quality and dealer relationships?
These are not abstract questions. They shape pricing strategy, underwriting policy, channel investment, technology roadmaps, and portfolio construction. The report provides the analytical depth needed to answer them with less uncertainty, while deliberately keeping the most granular segmentations and quantitative models in the full publication so that readers can benchmark against their own internal assumptions and test multiple strategic scenarios.
Conclusion: From Market Awareness to Market Advantage
Indirect auto finance remains a market defined by channel power, lender differentiation, and continuous regulatory evolution. The sector’s size and growth trajectory confirm its strategic importance, while the competitive composition and current dynamics reveal where advantage is being created and where risk is accumulating. Organizations that approach 2026 with a clear view of these forces will be better equipped to allocate resources, structure partnerships, and manage exposure across credit tiers and geographies.
This preview has outlined the landscape, the report architecture, and the decision themes that matter most. To access the complete market sizing, the full segmentation analysis, detailed competitive profiles, scenario-based forecasting, and operational recommendations, we invite you to visit the source page for the Indirect Auto Finance Market research. The full study is designed to be used directly in strategy sessions, portfolio reviews, and investment planning, giving decision-makers the granularity they need to move from interpretation to execution.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


