



PW Consulting: Global Sauna Steam Generator Market Hits $707 Million in 2025, Projected 6.61% CAGR Through 2032

Strategic Outlook 2026: Navigating the Global Sauna Steam Generator Market
The global wellness infrastructure sector is undergoing a structural transformation, and nowhere is this more evident than in the specialized segment of sauna steam generators. As leisure preferences shift toward holistic health solutions and commercial wellness facilities expand their footprint, the steam generator market has emerged as a critical intersection of thermal technology, consumer lifestyle trends, and industrial manufacturing capability. For executives, procurement leaders, and investment strategists operating in 2026, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, product roadmap planning, and regional expansion.
Our latest Worldwide Sauna Steam Generator Market report delivers a comprehensive, data-driven foundation for navigating this evolving landscape. Grounded in historical performance and calibrated for forward-looking projections, this analysis moves beyond surface-level demand signals to examine the underlying mechanics of value creation, competitive positioning, and regulatory adaptation. The following overview outlines the strategic architecture of the study and highlights why it serves as an essential decision-support tool for enterprise teams entering 2026 and beyond.
Market Trajectory and Macro Growth Signals
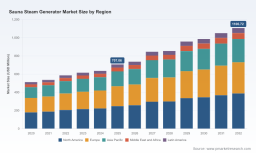
Over the past half-decade, the sauna steam generator sector has demonstrated resilient demand expansion, underpinned by a sustained shift in both residential and commercial wellness consumption. Historical revenue patterns from 2020 through 2025 reflect a clear upward curve, with the market consistently advancing past key inflection points despite broader macroeconomic volatility. By the close of the base period, total industry revenue had climbed into the $700 million range, marking a substantial recovery and subsequent acceleration from the pandemic-era baseline.
Looking ahead, the forecast window extending to 2032 projects a sustained compound annual growth trajectory of approximately 6.61 percent. This rate signals more than cyclical recovery. It reflects deepening ecosystem integration, where steam generation is increasingly recognized as a core component of wellness infrastructure rather than a peripheral amenity. The expansion is expected to be broad-based, supported by continuous product innovation, rising disposable income in emerging consumer markets, and the strategic prioritization of wellness amenities by hospitality and real estate developers. By the end of the projection horizon, the market is set to approach the $1.1 billion threshold, representing a meaningful step-change in scale and commercial maturity.
For strategic planners, this growth trajectory carries several implications. First, it validates long-term capacity and supply chain investments for manufacturers aligned with verified demand corridors. Second, it underscores the importance of timing. Market entry, capacity expansion, or partnership formation in 2026 places firms at the beginning of a multi-year growth cycle, where early positioning can translate into disproportionate margin advantage. Third, it highlights the need to differentiate between headline growth and segment-specific velocity, as not all power ratings, applications, or geographies are expanding at identical paces.
Structural Dimensions of Demand
A critical strength of this research lies in its granular segmentation framework. Rather than treating the market as a single monolith, the analysis dissects demand across power rating categories, end-use applications, and regional demand environments. This structured approach enables decision-makers to identify where volume concentration exists, where growth is accelerating, and where competitive intensity is reshaping pricing and product architecture.
Power rating segmentation reveals distinct usage profiles and engineering requirements. Lower-capacity units cater to compact residential installations and targeted wellness applications, while mid-range and higher-capacity systems serve larger commercial steam rooms, hospitality interiors, and multi-user public facilities. The distribution of revenue across these power tiers highlights how product capability mapping directly influences market share and margin profiles. Manufacturers that align their engineering roadmaps with the right capacity brackets can capture disproportionate demand while avoiding oversizing or performance mismatch.
Application segmentation further clarifies where commercial momentum is building. Residential deployments continue to anchor baseline demand, reflecting sustained consumer interest in home wellness environments and premium bathroom upgrades. Simultaneously, commercial spas, wellness centers, and hospitality properties are increasingly specifying steam generation as a core amenity differentiator. This dual-engine demand structure means the market is insulated from single-sector downturns. A slowdown in residential construction, for instance, can be partially offset by institutional procurement in wellness and hospitality, and vice versa.
Geographic segmentation provides additional nuance. While mature markets in North America and Europe maintain substantial revenue contributions, reflecting entrenched wellness culture and high installation standards, the Asia Pacific region represents a structurally expanding demand pool driven by urbanization, rising health consciousness, and growing hospitality investment. Middle Eastern, African, and Latin American territories contribute more incrementally but are increasingly relevant for specialized commercial projects and export-oriented manufacturing strategies. Mapping these regional dynamics helps firms calibrate distribution partnerships, localization efforts, and service network investments with greater precision.
Competitive Landscape and Strategic Positioning
The sauna steam generator sector is characterized by a moderately concentrated competitive environment, where established manufacturers, regional specialists, and technology-forward entrants compete on engineering quality, brand reputation, and application-specific solutions. The market structure reflects both consolidation pressure and persistent fragmentation in niche segments. Leading firms command meaningful shares through product breadth, compliance expertise, and deep integration with residential and commercial installation ecosystems. At the same time, smaller and regionally focused players compete by delivering specialized configurations, custom engineering, and localized service responsiveness.
Several core companies illustrate the breadth of strategic approaches shaping the market. Steamist, headquartered in New York, maintains a broad product range spanning residential and commercial steam generators with substantial capacity options, positioning the brand around versatility and engineering coverage. Mr. Steam, also based in the United States, emphasizes premium positioning and digital integration, with product lines that highlight app-controlled experiences and luxury home and spa applications. Amerec, operating from Washington state, focuses on reliable steam production for sauna environments, balancing residential accessibility with commercial-grade durability.
European manufacturers bring distinct strengths tied to regional standards and design philosophies. TyloHelo, based in Sweden, provides steam generator solutions integrated with sauna systems across residential and public facilities, emphasizing compatibility and European market familiarity. Harvia, a Finnish supplier, combines steam generator offerings with traditional and steam sauna heating equipment, targeting commercial installations where multi-product coordination matters. KLAFS GmbH, Germany-based, develops steam solutions oriented toward hotel and spa wellness areas, with a strong emphasis on compliance with European safety and performance expectations. In Canada, Saunacore differentiates through custom commercial steam generator manufacturing, utilizing stainless steel boiler construction to address durability and project-specific requirements.
Recent corporate activity reinforces the pace of innovation and market signaling. In early 2025, Mr. Steam introduced a new steam generator with enhanced Bluetooth controls, underscoring the industry-wide push toward connected, user-friendly wellness experiences. Later that year, TyloHelo showcased a new series of steam generators at a major European exhibition, signaling continued product refresh cycles and regional market engagement. Meanwhile, Harvia released an updated catalog emphasizing energy-efficient models for export markets, reflecting growing attention to efficiency, export competitiveness, and regulatory alignment.
Worldwide Sauna Steam Generator Market
For enterprise strategists, these competitive signals matter because they reveal where value is being created. Product differentiation through digital control interfaces, efficiency enhancements, and application-specific configurations is becoming a defining battleground. At the same time, compliance readiness, installation ecosystem strength, and after-sales service reliability increasingly determine win rates in commercial procurement. Understanding which competitors are scaling which capabilities allows firms to anticipate pricing pressure, identify partnership opportunities, and refine their own go-to-market positioning.
Industry Dynamics and Operational Realities
Beyond market sizing and competitive mapping, the research integrates the operational and environmental forces that shape execution risk and margin potential. Steam generator market performance does not unfold in isolation. It is influenced by raw material volatility, labor economics, regulatory mandates, certification requirements, and macroeconomic wellness trends. Ignoring these layers can lead to overly optimistic forecasting and misaligned procurement or production planning.
Material cost dynamics remain a persistent concern, particularly for manufacturers reliant on stainless steel for boiler construction and pressure-critical components. Recent price increases in key materials have placed upward pressure on unit production costs, prompting companies to reevaluate sourcing strategies, product design efficiency, and inventory hedging approaches. In a market where engineering quality and durability are central purchase criteria, cost pressures cannot be solved simply by substituting lower-grade materials. Instead, they demand design optimization, supply chain diversification, and value-based pricing strategies.
Labor and installation economics introduce another layer of complexity. The deployment of steam generators, especially in commercial environments, requires certified technicians and precise integration with plumbing, electrical, and ventilation systems. In some regions, labor cost escalation and technician shortages have raised installation expenses, affecting total project economics and the attractiveness of certain retrofit opportunities. For manufacturers and distributors, this highlights the strategic importance of installer training programs, simplified installation design, and regional service partnerships. Products that reduce installation friction can gain competitive advantage even when hardware pricing remains disciplined.
Regulatory and efficiency requirements are becoming increasingly binding. In Europe, energy efficiency mandates for commercial steam systems are raising the compliance bar, pushing manufacturers and specifiers toward higher-performance units. These requirements are not merely technical footnotes. They influence procurement specifications, eligibility for certain commercial contracts, and the long-term operating cost narrative that facilities use to justify capital expenditure. Companies that proactively engineer for compliance and communicate efficiency benefits effectively are better positioned to convert regulatory pressure into commercial differentiation.
Certification standards further shape market access, particularly in the United States, where safety certification for steam generators is closely tied to commercial sales eligibility. Meeting recognized standards reduces liability exposure, supports specifiers' risk management requirements, and strengthens the credibility of product claims. In a market where installation environments vary widely and safety expectations are high, certification readiness is a strategic asset rather than an administrative formality.
At the demand level, broader wellness tourism growth continues to provide a powerful tailwind for commercial-grade steam systems. As wellness-oriented travel expands, hotels, destination spas, and wellness resorts are investing in enhanced sauna and steam experiences to differentiate their offerings and support premium pricing. This trend strengthens the commercial application segment and reinforces the relevance of high-performance, reliability-focused generator offerings for institutional buyers.
What the Full Research Delivers
The complete market study is structured to support concrete business decisions rather than abstract observation. It combines historical market sizing with a forward-looking forecast framework, allowing users to benchmark current assumptions against a rigorously constructed trajectory. The analysis integrates segmentation across power rating, application, and region, enabling teams to isolate the demand pools most relevant to their product portfolio, distribution footprint, and investment horizon.
In addition to sizing and segmentation, the report examines competitive dynamics with detailed company profiles, strategic positioning notes, and recent development tracking. This allows readers to understand not only who the major players are, but how they are evolving their product lines, where they are concentrating innovation efforts, and what recent launches or catalog updates indicate about future market direction. For competitive intelligence teams, this section serves as a baseline for scenario planning and response strategy development.
The study also embeds industry context across material supply, labor economics, regulation, certification, and macro demand drivers. These insights are mapped to practical decision areas such as pricing strategy, capacity planning, installer engagement, compliance investment, and commercial targeting. By connecting environmental forces to operational implications, the report helps executives translate external signals into internal action.
Finally, the research is designed with practical usability in mind. It supports applications ranging from product portfolio prioritization and regional market entry evaluation to supplier negotiation, sales forecasting, and long-range capital planning. Whether the reader represents a manufacturer seeking to refine its capacity roadmap, a distributor assessing category growth, a hospitality group planning amenity investments, or an investor evaluating market maturity, the study provides a structured evidentiary foundation.
Why This Intelligence Matters for 2026 Decisions
The 2026 decision environment demands more than intuition. Market participants are operating in a space where growth is real but uneven, where competitive tactics are shifting toward digital integration and efficiency, and where regulatory and cost pressures are reshaping both product design and total cost of ownership. In that context, access to a validated market view is a strategic advantage.
This research helps leaders answer the questions that most directly affect execution. Which demand segments offer the strongest growth-to-effort ratio? Where are competitors likely to intensify product or pricing activity? How should material cost and labor constraints influence sourcing and installation strategy? Which compliance and certification investments are most likely to protect or expand commercial access? By addressing these questions within a single analytical framework, the report reduces ambiguity and supports more confident planning.
Equally important, the study provides the right level of granularity for strategic choice without overwhelming decision-makers with disconnected statistics. The emphasis is on interpretive clarity. Readers gain a working understanding of how historical performance translates into forward expectations, how segmentation shapes opportunity, and how competitive and operational dynamics interact to determine market outcomes.
Conclusion
The global sauna steam generator market is entering a phase in which scale, sophistication, and strategic timing will increasingly separate winners from followers. Growth is anchored by durable wellness demand, reinforced by commercial hospitality investment, and shaped by evolving engineering, efficiency, and compliance expectations. For organizations making decisions in 2026, the opportunity lies in aligning product strategy, distribution focus, and operational preparedness with the segments and dynamics most likely to drive value.
This Worldwide Sauna Steam Generator Market report is designed to support that alignment. It offers a comprehensive, forward-looking, and operationally relevant view of where the market has been, where it is heading, and what that means for competitive and investment decisions. For teams seeking a deeper, data-backed foundation for planning, the full study provides the detailed segmentation, company-level intelligence, and market context necessary to move from broad outlook to precise action.
Sauna Equipment Market
For detailed analysis of this topic, please visit the official page: Worldwide Sauna Steam Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


