



PW Consulting: Global Hearables Market Hits $68.6B in 2025, Poised for 12.35% CAGR Through 2032

Beyond Audio: Strategic Intelligence for the Global Hearables Market Through 2032
The hearables sector has evolved far beyond simple audio playback. Today’s ear-worn devices sit at the intersection of consumer lifestyle, enterprise productivity, clinical hearing health, and emerging AI-driven wellness monitoring. As organizations map their product roadmaps, supply chain strategies, and go-to-market plans for 2026 and beyond, decision-makers require more than headline growth figures. They need a structured, evidence-based view of how technology shifts, regulatory pressures, competitive dynamics, and regional manufacturing realities will reshape value capture across the entire hearables ecosystem.
Worldwide Consumer and Enterprise Hearables Market
Our latest Worldwide Consumer and Enterprise Hearables Market research delivers precisely that intelligence. Spanning a rigorous historical baseline from 2020 through 2025 and a forward-looking forecast window of 2026 to 2032, the study translates macro trajectory into actionable strategic guidance. The global market reached approximately 68.6 billion USD in 2025 and is projected to expand to roughly 76.3 billion USD in 2026, maintaining a compound annual growth rate of 12.35 percent through 2032, when total revenue is expected to approach 155 billion USD. These figures establish the scale of the opportunity, but the real strategic value lies in understanding how growth fractures across product categories, end-user segments, geographic demand centers, and competitive positioning. This introduction outlines the report’s analytical architecture and demonstrates why it should sit at the center of executive planning for the remainder of the decade.
What This Research Covers
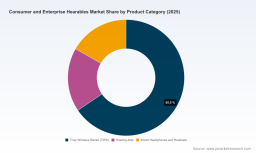
The study is engineered for practitioners who must connect market signals to operational decisions. Rather than offering a single aggregated number, the research disaggregates the market across three primary dimensions: product category, end-user application, and regional demand. On the product side, the analysis examines truly wireless stereo devices, hearing aids, and smart headphones and headsets as distinct commercial engines, each with different innovation cadences, pricing architectures, and adoption drivers. The end-user lens separates consumer and enterprise applications, enabling leaders to compare how volume, loyalty, procurement cycles, and feature priorities diverge between mass-market audio consumption and business-focused communication, collaboration, and health-oriented deployments.
Regional analysis maps where demand is concentrating and where supply-side vulnerabilities are emerging. The research evaluates market concentration dynamics, showing that the three largest players command a meaningful share of total revenue and that the top five firms collectively represent a substantial portion of industry output. This concentration is not static; it reflects ongoing differentiation in ecosystem lock-in, hearing health capabilities, premium audio quality, and enterprise-grade reliability. The report translates these structural patterns into guidance for market entry, partnership strategy, M&A screening, and competitive response planning.
Beyond segmentation, the report delivers a functional toolkit for strategy teams. It includes product positioning frameworks, demand sensitivity analysis tied to form-factor evolution and audio performance expectations, and a detailed competitive benchmarking structure that links corporate capabilities to market outcomes. The forecast model incorporates scenario sensitivity so that leaders can test how shifts in pricing, regulatory tariffs, component availability, and health-feature adoption might alter growth paths. Every section is designed to move from observation to implication, allowing executives, product managers, and investors to prioritize initiatives with greater confidence.
Competitive Landscape: Technology, Ecosystem, and Enterprise Positioning
The competitive field in hearables is defined by two overlapping battles: one for consumer attention and one for enterprise and clinical relevance. At the consumer end, a handful of ecosystem-driven leaders continue to set the pace. Apple remains a dominant force in the consumer space, leveraging the AirPods lineup to capture both everyday audio demand and emerging health-oriented use cases, including hearing assistance and wellness monitoring features. Its firmware and product cadence demonstrate how software-defined functionality can extend hardware lifecycles and deepen user retention. Samsung competes as a major provider of Galaxy Buds, building cross-device functionality that aligns well with Android-based mobility and workplace environments. Sony pursues the premium segment with high-fidelity true wireless earbuds that emphasize advanced noise cancellation and immersive sound, targeting both consumer and professional listening scenarios where audio quality is a core purchasing criterion.
In the enterprise and professional communication segment, the differentiation logic shifts from lifestyle branding to call quality, collaboration reliability, and environmental resilience. Jabra bridges consumer earbuds and professional headsets, focusing on communication clarity and business collaboration solutions. Poly serves unified communications, call centers, and business collaboration with headsets and hearables optimized for workplace deployment. Shure contributes professional-grade audio earphones for enterprise, stage, and high-performance applications where acoustic precision and durability are non-negotiable. Sennheiser rounds out the premium professional audio set with devices built around sound quality and commercial use cases. These players illustrate how enterprise hearables market themselves on operational outcomes rather than consumer novelty.
A third, rapidly intensifying front is hearing health and connected clinical applications. Demant, Starkey, and WS Audiology operate at the convergence of consumer-style wearables and advanced hearing assistance, developing products that integrate health monitoring, AI-supported personalization, and premium audio processing. These companies are actively bridging consumer and clinical/enterprise health applications, expanding the addressable market beyond traditional hearing aid purchasing cycles. At the same time, companies such as Bose continue to push premium noise-cancelling performance that translates directly into office and focus-oriented enterprise environments, while Xiaomi, Nothing Technology, and LG demonstrate how value-oriented and design-forward offerings keep pressure on price points and broaden global accessibility.
Recent developments reinforce how quickly capabilities are shifting. CES 2026 highlight reels pointed to rising interest in high-fidelity sound, immersive audio, and new form factors, with concepts like the Aura Nebula underscoring experimentation beyond conventional earbud designs. Apple’s shipment volume in early 2025 reaffirmed the scale of its consumer footprint, while firmware updates introduced AI-based health monitoring features that signal a longer-term pivot toward wellness and auditory health. Nothing Technology’s AI-integrated earbuds with scene-aware audio tuning show how software adaptation is becoming a differentiator even outside the top-tier premium tier. Together, these moves suggest that the next competitive cycle will be defined by health integration, adaptive sound personalization, and form-factor innovation, not merely incremental battery or antenna improvements.
Market Dynamics: Supply Chains, Regulation, and Component Risk
Strategic planning for hearables in 2026 must account for a tightening set of external pressures. Global trade dynamics and tariff frameworks continue to influence device costs, prompting companies to explore regional manufacturing and local sourcing as a way to strengthen supply chain resilience. The strategic implication is clear: cost modeling can no longer assume stable cross-border logistics, and regional exposure should be evaluated alongside product pricing and margin targets.
Component availability adds another layer of complexity. Volatility in MEMS microphone supply and cobalt sourcing has been noted as a risk factor, especially given the concentration of manufacturing activity in Asia Pacific. On the materials side, disruptions such as those affecting quartz supply chains have the potential to lengthen silicon lead times for hearables components, with downstream effects on product timing and inventory planning. At the same time, U.S. tariff policies have introduced renewed uncertainty into MEMS microphone and related component supply chains, which makes scenario planning around sourcing geography and bill-of-materials flexibility increasingly important. These pressures are not abstract; they affect time-to-market, pricing stability, and the ability to scale premium features without eroding margins.
Component innovation is also reshaping product potential. The introduction of specialized accelerometers designed for hearables, including devices with voice activity detection capabilities, points toward richer in-ear sensing and more nuanced interaction models. Such advances expand the design space for both consumer and enterprise applications, enabling smarter audio tuning, context-aware features, and more capable health or communication functions. The strategic lesson is that competitive advantage in hearables is increasingly tied to the ability to integrate advanced sensing and processing into compact form factors while managing supply risk.
Why This Report Matters for 2026 Decision-Making
The forecast window from 2026 through 2032 is not merely a statistical exercise; it is a planning horizon for product portfolios, regional expansion, channel strategy, and capital allocation. As the market progresses from roughly 76.3 billion USD in 2026 toward an estimated 155 billion USD by 2032, the underlying composition of that growth will matter more than the headline trajectory. Organizations need to know where wallet share is migrating, which product categories are likely to outpace the broader market, how enterprise demand will compare with consumer consumption patterns, and which competitive capabilities will separate market leaders from followers.
Hearables Market
This report gives decision-makers a structured basis for answering those questions. It links macro growth to segmentation behavior, maps concentration and competitive intensity, and frames supply-side and regulatory risk within market strategy rather than treating them as separate concerns. For product teams, it clarifies where premium quality, hearing health, and enterprise-grade communication intersect with volume-driven consumer segments. For supply chain and procurement leaders, it highlights the relevance of regional sourcing, component volatility, and tariff exposure. For corporate strategy and investor teams, it offers a benchmark for evaluating M&A targets, partnership opportunities, and market-entry timing in a market where ecosystem integration and health functionality are becoming central value drivers.
How to Use the Full Intelligence Package
The complete study extends well beyond the summary perspective outlined here. It provides detailed segmentation analysis across regions, product categories, and end-user groups; competitive profiles that connect product strategy, ecosystem positioning, and enterprise applicability; and forward-looking scenario analysis that helps teams test strategic assumptions against plausible changes in regulation, component supply, and consumer preferences. The research also incorporates recent industry developments and supplier-level signals so that forecasts remain anchored to real-world momentum rather than abstract projection.
For executives preparing 2026 plans and multi-year roadmaps, the full report functions as both a market map and a decision support tool. It is designed to support portfolio planning, go-to-market prioritization, competitive positioning reviews, and risk-aware forecasting across consumer and enterprise hearables. To access the complete segmentation detail, competitive benchmarks, and scenario frameworks, download the full Worldwide Consumer and Enterprise Hearables Market research and use it as the foundation for your 2026 strategy discussions.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer and Enterprise Hearables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


