



PW Consulting: Global Estate Agent Fees Hit $331.58B in 2025, Projected 4.5% CAGR to 2032

Navigating the Global Estate Agent Fees Landscape: Strategic Intelligence for 2026 and Beyond
The global real estate sector stands at a pivotal inflection point. As transaction volumes fluctuate and regulatory frameworks evolve, the economics of property intermediation are undergoing a structural recalibration. For executives, investors, and market strategists, understanding the trajectory of estate agent fees is no longer a peripheral concern—it is a core determinant of pricing strategy, channel partner alignment, and long-term profitability. Our latest Worldwide Estate Agent Fees Market research delivers a rigorously structured, data-rich analysis designed to equip leadership teams with the intelligence required to navigate 2026 and the decade ahead.
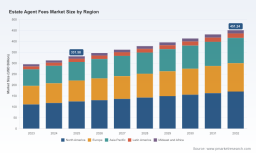
Built on a comprehensive historical foundation spanning 2020 through 2025, this study projects market behavior across a seven-year forecast horizon ending in 2032. The analysis is anchored in a macroeconomic baseline that places the global market valuation at 295.1 billion USD in 2023, rising to 312.81 billion in 2024, and reaching 331.58 billion in 2025. Looking forward, the model projects a steady expansion to 346.5 billion in 2026, continuing through 362.1 billion in 2027, 378.39 billion in 2028, 395.42 billion in 2029, 413.21 billion in 2030, 431.81 billion in 2031, and culminating at 451.24 billion in 2032. Driving this trajectory is a compound annual growth rate of 4.5 percent, a figure that reflects both organic transaction volume recovery and the strategic premium attached to specialized intermediation services in maturing and emerging markets alike.
These headline figures are essential, but they are only the starting point. The true strategic value of this research lies in how it contextualizes growth, decomposes revenue streams, and maps competitive positioning across a rapidly fragmenting global landscape.
Macro Trajectory and the Strategic Imperative for 2026
The transition from 2025 into 2026 marks more than a numerical milestone; it represents a window where historical normalization intersects with forward-looking structural shifts. Market participants who rely on legacy commission assumptions or static regional benchmarks are increasingly exposed to margin compression, pricing misalignment, and channel inefficiency. By anchoring decision-making to a forecast that extends to 2032, organizations can stress-test pricing architectures, anticipate service-mix rebalancing, and align resource allocation with the segments that will command the highest yield per transaction.
The 4.5 percent CAGR should not be read in isolation. It encapsulates the interplay between transaction frequency, average property valuations, service differentiation, and regional regulatory cadence. In high-maturity markets, growth is increasingly driven by fee optimization, value-added advisory layers, and technology-enabled service delivery. In developing corridors, expansion is propelled by formalization of transaction processes, rising urbanization, and the gradual professionalization of intermediation. Understanding where each force dominates allows firms to calibrateGo-to-market strategies rather than applying uniform pricing templates across disparate operating environments.
How This Report Converts Raw Data into Actionable Intelligence
Market size and growth rates are necessary, but they are not sufficient for executive decision-making. This study is engineered to translate macro indicators into operational clarity. The methodology integrates historical transaction economics, regulatory timeline mapping, and forward-looking scenario modeling to produce a multi-dimensional view of fee structures across property types, service categories, and geographic corridors.
Readers will encounter a structured breakdown of the market by region, property type, and service type, each analyzed through the lens of revenue contribution, pricing elasticity, and competitive intensity. The report dissects how residential brokerage dynamics diverge from commercial intermediation, and how leasing and rental services interact with traditional sales-based fee models. Property management services are examined as a distinct, increasingly strategic revenue layer, particularly in markets where asset tenure shifts toward institutional and long-term rental frameworks.
Beyond segmentation, the analysis incorporates service-level architecture, commission negotiation patterns, and the economic implications of buyer representation realignments. The research also evaluates how labor cost structures, agent productivity metrics, and technology adoption curves influence the cost base of intermediation firms, which in turn shape the fees passed to clients. For organizations assessing partnership models, channel expansion, or service bundling strategies, this granularity provides the scaffolding needed to evaluate margin resilience under multiple pricing scenarios.
To preserve analytical integrity and protect proprietary modeling frameworks, the report deliberately avoids exposing granular sub-segment percentages or itemized regional valuations within this overview. Those precise allocations, sensitivity ranges, and scenario-dependent breakdowns are reserved for the full publication, ensuring that stakeholders who access the complete dataset receive a defensible, decision-grade intelligence package rather than a superficial snapshot.
Competitive Landscape: Positioning, Models, and Strategic Divergence
The global estate agent fees market is shaped by a diverse cohort of intermediaries whose business models, geographic footprints, and pricing philosophies diverge significantly. Understanding these differences is critical for any firm evaluating market entry, partnership selection, or competitive positioning.
Among the most prominent network-based franchises, RE/MAX International and Century 21 Real Estate continue to exert broad influence across residential brokerage channels. RE/MAX operates a globally scaled franchise architecture with an extensive agent base across more than one hundred countries, positioning its fee structure around the traditional commission model commonly associated with transaction-based splits. Century 21 maintains a similarly expansive brand footprint, with thousands of independently owned offices and a residential brokerage orientation that relies on negotiable commission frameworks shaped by local market norms.
Keller Williams Realty approaches the market through an agent-centric franchise philosophy, emphasizing flexible compensation models that can range toward high agent-retention splits in select configurations. Coldwell Banker Realty leans into a premium residential and luxury brokerage identity, with commission ranges that typically align with high-value transaction economics and brand positioning around discretion and market access. Berkshire Hathaway HomeServices reinforces a premium residential network across a wide domestic footprint and select international corridors, averaging commission levels that reflect its positioning in higher-tier transaction segments.
A parallel competitive current is defined by technology-forward and virtual brokerage platforms. eXp Realty illustrates this model with a large global agent community, low per-transaction overhead, and commission structures that leverage reduced fixed costs to remain competitive at the client level. This virtual operating architecture demonstrates how digital distribution, centralized service delivery, and lower physical overhead can translate into alternative fee economics.
Worldwide Estate Agent Fees Market
Across the broader services landscape, premium consultancy-oriented firms such as Savills and Knight Frank operate with fee philosophies calibrated to regional conventions and property tiers. Savills delivers residential agency services with fee frameworks that are typically lower in percentage terms than the commission-heavy models seen in some North American channels, reflecting regional pricing norms and client expectations. Knight Frank applies a consultancy-led approach to residential sales, with sole agency fees that vary by property value and market context, emphasizing advisory quality and market reach over volume-driven transaction scaling.
Collectively, these firms illustrate a market in which competitive advantage is no longer derived solely from brand recognition. It is increasingly shaped by service architecture, agent economics, technology leverage, and the ability to adapt fee structures to regulatory and consumer-behavior shifts.
Market Dynamics and Structural Shifts Redefining Fee Economics
No analysis of estate agent fees can be credible without confronting the regulatory and behavioral forces actively reshaping transaction economics. In the United States, a landmark antitrust settlement finalized in mid-2024 mandated structural changes to buyer representation agreements and altered how commission-related terms appear in listing ecosystems. Effective from August 2024, the settlement requires written buyer-broker agreements before property tours and removes seller-paid buyer agent commissions from MLS display conventions. This development has cascading implications for fee negotiation, channel incentives, and how agents structure service offerings to both buyers and sellers.
Regulatory transparency requirements are also intensifying elsewhere. In the United Kingdom, estate agents are subject to enforced fee-disclosure obligations under consumer protection regulations, with updated enforcement posture reinforcing the expectation that fee terms be presented prominently and clearly. These measures reduce information asymmetry but also raise the bar for competitive differentiation, forcing firms to justify fee levels through service quality, market reach, and advisory depth rather than opacity.
On the consumer and labor side, structural data points highlight the operational realities behind fee models. United States real estate sales agent compensation reflects a median wage environment paired with employment levels that underscore the sector’s continued reliance on a broad agent base. In parallel, Australian market data indicates an average remuneration structure combining base salary with commission-driven upside, reinforcing how agent economics shape fee architecture in markets where productivity and incentive alignment are central to performance.
In the United Kingdom, recent survey data shows that average sale fees have experienced modest compression amid competitive intensity, with a substantial share of homeowners selecting sole agency arrangements to manage cost exposure. This behavior signals a market that is becoming more price-aware and more willing to trade multi-agent exposure for cost efficiency, a pattern with direct implications for how firms design service bundles and communicate value.
These dynamics do not operate in silos. They interact with macroeconomic cycles, financing conditions, cross-border investment flows, and technology adoption. Firms that treat regulation, consumer behavior, and labor economics as isolated variables risk building strategies that are fragile under concurrent pressure. The research integrates these forces into a unified market dynamics framework, allowing readers to assess how pricing, positioning, and service design should evolve under multiple plausible scenarios.
Guitar Effects Market
Why Executive Access to the Full Intelligence Is Critical
For boards, strategy directors, and commercial leaders, the question is not whether estate agent fees matter, but how precisely they will behave across segments and geographies in the coming years. A high-level market size figure and a headline growth rate may inform a brief discussion, but they do not provide the segmentation clarity, competitive mapping, or scenario sensitivity required for robust planning. Full access to this research unlocks region-specific revenue trajectories, service-type growth differentials, property-type pricing behavior, and a detailed competitive benchmarking framework that ties company positioning to actionable strategic implications.
In an environment where fee structures are being renegotiated, regulatory mandates are reshaping agent-client relationships, and technology-enabled models are altering cost baselines, decision-makers need intelligence that is both broad and precise. This report delivers that combination, giving organizations a defensible foundation for pricing strategy, partnership selection, market prioritization, and service innovation.
Conclusion: Positioning for Decisive Advantage
The worldwide estate agent fees market is expanding, but its growth is uneven, context-dependent, and increasingly shaped by structural rather than cyclical forces. The trajectory toward 2032 signals sustained expansion, yet the strategic opportunity lies in understanding where value concentrates, how competitive models differ, and which regulatory and behavioral shifts will redefine fee justification in the near term. This research equips leaders with the analytical architecture needed to make those judgments with confidence. For organizations ready to move beyond surface-level market narratives and access the full segmentation, competitive mapping, and scenario detail required for high-stakes planning, the complete report provides the decisive intelligence layer for 2026 and the decade ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Estate Agent Fees Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


