



PW Consulting: Global Optoelectronic Safety Laser Scanner Market to Reach $949.45M by 2032

Navigating the Next Wave: Why the Global Optoelectronic Safety Laser Scanner Market Demands Stakeholder Attention in 2026
The intersection of advanced automation, stringent safety regulations, and evolving supply chain dynamics has placed optoelectronic safety laser scanners at a critical juncture for industrial enterprises worldwide. As manufacturing floors become more collaborative, logistics networks grow increasingly autonomous, and regulatory frameworks continuously refine safety distance calculations, the demand for reliable, certified protective sensing solutions continues to accelerate. Our newly released Worldwide Optoelectronic Safety Laser Scanner Market research report provides a comprehensive, data-backed blueprint for executives, product leaders, and supply chain strategists who need to navigate this complex landscape through 2026 and beyond.
This insight piece serves as a strategic preview of the full study. It highlights the structural forces reshaping the sector, outlines the analytical depth contained within the complete dataset, and explains why a clear understanding of market trajectories, competitive positioning, and regulatory impacts is indispensable for capital allocation, product roadmapping, and risk mitigation in the coming year.
Market Trajectory and Structural Growth Signals
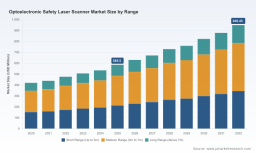
The optoelectronic safety laser scanner segment has demonstrated consistent, compounding expansion over the past half-decade, reflecting the broader industrial transition toward safeguarded automation. Historical revenue figures from 2020 through 2025 trace a clear upward arc, with the global market crossing significant valuation thresholds as industries adopted more sophisticated area guarding, machine protection, and mobile platform safety solutions. Building on that momentum, the baseline year valuation has already set the stage for the forecast period spanning 2026 to 2032, during which the sector is projected to sustain a robust compound annual growth rate of 7.15 percent.
This trajectory is not merely a function of incremental capacity additions. It reflects a structural realignment in how end users approach safety integration. Legacy fixed guarding is being supplemented, and in many cases replaced, by programmable protective fields that adapt to dynamic workcells, collaborative robotics environments, and autonomously navigating material handling systems. As enterprises modernize brownfield facilities and design greenfield automation architectures, the requirement for certified, field-configurable laser scanning technology has moved from a compliance checkbox to a core engineering consideration. The forecast window captures this transition in detail, mapping revenue progression across multiple years and highlighting the inflection points where adoption curves steepen as standardization efforts mature and downstream integration becomes more seamless.
For leadership teams evaluating capital deployment, product portfolio expansion, or regional market entry, the macro trajectory provides an essential baseline. However, the real strategic value lies beneath the aggregate figures. The complete report dissects how different range configurations, end-user verticals, and geographic corridors contribute to the overall growth narrative, enabling precise scenario planning without relying on broad industry generalizations.
Product Segmentation and Application Realities
Safety laser scanners are not a monolithic category. Range capability, scanning geometry, environmental resilience, and networking architecture fundamentally dictate where a given device can be deployed and how it delivers return on investment. The market naturally partitions across short, medium, and long-range protective fields, each serving distinct operational requirements. Short-range configurations excel in compact workcells, tight-space machine guarding, and applications where footprint constraints dominate design decisions. Medium-range solutions strike a balance between coverage and integration flexibility, frequently appearing in automated guided vehicle pathways, access protection zones, and medium-scale material handling environments. Long-range variants cater to expansive outdoor or semi-outdoor scenarios, including crane operations, large-scale logistics yards, and mobile platforms that require earlier hazard detection to ensure safe stopping distances.
On the demand side, end-user segmentation reveals how different industries are redefining their safety technology stacks. Automotive production lines continue to prioritize high-speed area monitoring and access control around robotic cells, where rapid response times and reliable field configuration are non-negotiable. Logistics and warehousing operations have driven substantial volume as autonomous mobile robots and conveyor ecosystems expand, pushing integrators to specify scanners that can handle continuous duty cycles and dynamic obstacle detection. Consumer electronics manufacturing, food and beverage processing, and a broad spectrum of other industrial applications contribute meaningfully to the overall demand profile, each bringing unique environmental, hygiene, and throughput considerations that shape product specification preferences.
The full report provides granular breakdowns of these segmentation dimensions, mapping revenue distribution and growth intensity across each category. Rather than presenting static snapshots, the analysis connects range preferences to application requirements, end-user purchasing behavior, and the evolving certification landscape. This layered approach allows technology buyers and suppliers alike to identify where specification upgrades are driving premium positioning, where cost-optimized configurations are enabling broader electrification of safety systems, and where emerging use cases are creating white-space opportunities.
Regional Dynamics and Competitive Intensity
Geographically, the market reflects the dispersed nature of global industrial production, with mature automation hubs and rapidly modernizing manufacturing corridors both contributing to overall demand. Europe maintains a strong presence, anchored by longstanding industrial automation ecosystems and rigorous safety engineering practices. Asia Pacific represents a highly active demand center, driven by large-scale manufacturing expansion, growing adoption of autonomous material handling, and increasing localization of safety component supply chains. North America continues to exhibit steady procurement patterns tied to facility modernization, logistics automation, and heavy industrial safeguarding initiatives. Latin America and the Middle East and Africa, while smaller in absolute volume, present targeted growth vectors where automation upgrades and export-oriented production facilities are accelerating safety technology adoption.
The competitive landscape mirrors this geographic dispersion and application diversity. Leading suppliers have built differentiated portfolios by emphasizing range performance, integration convenience, environmental hardening, and certification breadth. German manufacturers remain deeply embedded in the industrial safety value chain, offering families of two-dimensional safety laser scanners with protective field configurations tailored to stationary, mobile, and outdoor use cases, many carrying performance level d or safety integrity level 2 ratings. Japanese technology providers have focused on high-detection-range architectures, integrated vision capabilities, and robust networking protocols, enabling complex area guarding and warning zone management across demanding environments. American and Italian players contribute specialized form factors, compact footprints, and application-specific variants that address space-constrained integration, weld-cell protection, and machine safeguarding requirements.
Market concentration data underscores the strategic importance of competitive positioning. The sector is characterized by a meaningful share held by a relatively compact group of established vendors, which suggests that new entrants or expanding incumbents must deliver clear differentiation in performance, certification readiness, or total cost of integration to gain traction. Recent product and standardization developments illustrate how aggressively the field is moving. One major European supplier introduced a three-dimensional lidar sensor with safety certification for outdoor mobile applications, targeting cranes and autonomous guided vehicles with enhanced environmental protection and multi-echo signal processing. Another German manufacturer launched an ultra-compact scanner optimized for space-limited integration in autonomous platforms and machinery, emphasizing a wide scanning angle within a minimal footprint. At the same time, portfolio updates from other leading vendors have added fieldbus interfaces, expanded zone monitoring capacity, and streamlined diagnostic workflows to reduce commissioning time and simplify network integration.
Alongside product launches, the regulatory environment continues to reshape engineering requirements. Updated safety distance calculation standards have refined how protective devices are positioned relative to hazards, introducing more precise formulas for orthogonal approaches, reaching scenarios, and measurement uncertainty allowances. These revisions affect how scanners are specified, where they are mounted, and how safety zones are configured. In parallel, export control measures and semiconductor supply restrictions have influenced upstream component availability, particularly for infrared laser diodes and associated compound semiconductor wafers. Because a concentrated supplier base dominates gallium arsenide wafer capacity, scanner manufacturers must navigate lead-time variability and cost fluctuations that can ripple through production planning and final-device pricing.
What the Full Report Delivers to Decision-Makers
The complete Worldwide Optoelectronic Safety Laser Scanner Market study translates these dynamics into an actionable intelligence framework designed for executive review, technical planning, and commercial strategy development. The report is organized to support both high-level strategic synthesis and detailed tactical execution.
Worldwide Security Laser Scanner Market
-
Macro Market Modeling and Forecast Architecture
The analysis provides a year-by-year valuation path anchored in the 2025 baseline and extending through the 2032 forecast horizon. Revenue trajectories are contextualized against adoption drivers, regulatory milestones, and supply-side considerations, giving stakeholders a defensible reference point for budgeting, capacity planning, and investment timing.
-
Segment-Level Structural Analysis
Beyond aggregate growth, the study breaks down market composition by range category and end-user vertical, enabling readers to understand which configurations and applications are driving volume, which are expanding most rapidly, and how specification preferences differ across operational environments. This structure supports product portfolio prioritization, go-to-market targeting, and sales enablement with a clear view of where demand is concentrated and where it is shifting.
-
Regional Co-Evaluation and Market Access Insights
Geographic revenue distribution is mapped to regional automation maturity, regulatory environments, and supply chain conditions. This allows strategists to assess where established demand is stable, where modernization-driven growth is accelerating, and where localized supply or certification considerations may influence market entry or expansion decisions.
-
Competitive Profiling and Strategic Positioning
Detailed company evaluations cover portfolio scope, technology differentiation, certification coverage, and recent development activity for the leading participants shaping the market. These profiles are designed to help procurement teams benchmark supplier capabilities, assist product managers in identifying feature gaps, and support commercial teams in mapping competitive vulnerabilities and partnership opportunities.
-
Regulatory, Standards, and Supply Chain Context
The report integrates the impact of updated safety positioning standards, certification pathways for emerging three-dimensional variants, and upstream material constraints affecting laser diode availability. By connecting compliance requirements and component availability to market behavior, the study helps organizations anticipate specification changes, manage procurement risk, and align engineering roadmaps with evolving technical expectations.
-
Practical Decision-Support Frameworks
Throughout the analysis, findings are framed to support concrete business actions: where to focus research and development investment, how to prioritize integration features that reduce deployment friction, which end-user segments offer the most favorable risk-reward profiles, and how to interpret concentration dynamics when evaluating partnership or acquisition strategies.
Worldwide Optoelectronic Safety Laser Scanner Market
Strategic Implications for 2026 Planning
As enterprises move through 2026, the optoelectronic safety laser scanner market will reward organizations that treat safety sensing as a strategic integration layer rather than a commodity component. The convergence of higher automation intensity, more demanding safety calculations, and variable semiconductor supply conditions means that procurement timing, specification choices, and supplier relationships will have an outsized impact on project economics and operational reliability.
For manufacturers, the question is no longer simply which scanner meets a baseline safety requirement. It is how the selected technology integrates with control architectures, how quickly it can be commissioned across multiple zones, how its field configuration supports future layout changes, and how resilient its component supply chain is against upstream constraints. For suppliers and system integrators, the opportunity lies in aligning product development with the practical needs of mobile platforms, compact workcells, and outdoor mobile applications, while ensuring certification readiness keeps pace with evolving standard revisions. For investors and strategic planners, the concentration of market share among established players alongside persistent segmentation differences suggests that value creation will increasingly come from application-specific differentiation, integration simplification, and regional supply chain agility.
The full report is designed to give leadership teams the evidence base required to make these decisions with confidence. Rather than relying on broad directional statements, it provides the structured segmentation, competitive context, and forecast granularity needed to test assumptions, refine targets, and allocate resources where they are most likely to generate durable returns.
Access the Complete Strategic Intelligence
This overview has outlined the market's growth trajectory, the segmentation forces shaping demand, the competitive and regulatory environment influencing supply, and the practical analytical tools embedded in the full study. To move from high-level direction to precise, data-supported decision-making, stakeholders should consult the complete Worldwide Optoelectronic Safety Laser Scanner Market report. The full version contains the detailed segmentation breakdowns, regional revenue paths, company-specific competitive assessments, and forecast sensitivity context necessary to translate industry momentum into actionable strategy.
For executives and technical leaders preparing for 2026 planning cycles, the complete dataset offers a direct route to clearer market understanding, more disciplined specification choices, and stronger confidence in long-term safety technology investments.
For detailed analysis of this topic, please visit the official page: Worldwide Optoelectronic Safety Laser Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


