



PW Consulting: PVDF Coatings Market to Reach $2.41B by 2032 with 6.02% CAGR

Decoding the Global PVDF Fluorocarbon Coatings Landscape: Strategic Imperatives for 2026 and Beyond
The global coatings industry stands at a critical inflection point. As infrastructure modernization accelerates across emerging economies and sustainability regulations tighten in mature markets, fluorocarbon coatings have cemented their position as the standard for high-durability, weather-resistant protective finishes. At the center of this evolution is the polyvinylidene fluoride (PVDF) fluorocarbon coatings market, a specialized segment that bridges advanced polymer chemistry with large-scale architectural, industrial, and infrastructure applications.
PW Consulting's latest Worldwide PVDF Fluorocarbon Coatings Market report delivers a comprehensive strategic intelligence package designed explicitly for executive decision-makers, procurement leaders, and competitive intelligence teams navigating the 2026-2032 forecast cycle. Rather than offering a static snapshot of market boundaries, this research builds a dynamic framework that connects pricing trajectories, regional demand shifts, formulation transitions, and regulatory pressures to actionable commercial strategies.
Market Trajectory: From Consolidation to Sustained Growth
The historical record establishes a clear growth narrative. Between 2020 and 2025, the worldwide PVDF fluorocarbon coatings market expanded from approximately 1,180.5 million USD to 1,600.68 million USD, reflecting sustained investment in premium protective coatings for metal substrates across construction, industrial equipment, and automotive applications. This upward trajectory has carried momentum into 2026, with baseline revenue projected at 1,615.17 million USD, and the forecast horizon extending through 2032 forecasts a market value of 2,410.01 million USD.
The compound annual growth rate (CAGR) of 6.02 percent across the 2026-2032 forecast window signals more than incremental expansion. It reflects structural demand drivers that are reshaping procurement strategies and production planning across the value chain. Companies that treat PVDF coatings as a commodity input risk missing the strategic implications embedded in this growth curve: regional capacity reallocation, formulation chemistry transitions, raw material volatility management, and intensifying competitive positioning among global resin producers and formulated coating suppliers.
This report contextualizes the macro trajectory within the operational realities that executives face on the ground. Rather than presenting growth as a uniform trend, the analysis maps how different demand centers and application verticals contribute to the overall expansion, enabling leadership teams to prioritize investments where margin resilience and volume growth intersect.
Forecast Architecture: 2026-2032 Strategic Planning Window
The 2026-2032 forecast period is structured to support multi-year capital allocation and product portfolio decisions. The baseline year of 2025 anchors the analysis in recent market conditions, while the forward projections account for the interplay between raw material cost dynamics, capacity expansion timelines, and evolving end-use specifications. By 2027, the market approaches 1,795.94 million USD, and by 2030 it reaches 2,021.2 million USD, before accelerating toward the 2032 endpoint.
This growth path is not a straight line. The forecast architecture incorporates year-by-year variations that reflect the timing of production capacity additions, the pace of regulatory implementation across key jurisdictions, and the lag between raw material price shocks and downstream formulation adjustments. Decision-makers using this research can model sensitivity scenarios around these inflection points rather than relying on blunt average growth assumptions.
The report's forecast methodology is built to answer a specific set of executive questions: Where will incremental volume materialize over the next seven years? Which formulation categories are positioned to capture share as environmental standards evolve? How should organizations sequence capacity, inventory, and supplier diversification strategies against projected demand? These questions are addressed through segment-level analysis that preserves analytical precision without sacrificing strategic clarity.
Competitive Intelligence: The Arena's Principal Architects
The PVDF fluorocarbon coatings market is defined by a concentrated yet highly specialized competitive landscape. Leading resin producers and formulated coating manufacturers each occupy distinct strategic positions, balancing raw material control, application expertise, and regional distribution strength. Understanding these positions is essential for benchmarking, partnership evaluation, and threat assessment.
Worldwide PVDF Fluorocarbon Coatings Market
Arkema, headquartered in France, anchors its offering through Kynar PVDF resins and Kynar 500 for high-performance fluorocarbon coatings in architectural and industrial applications, with emphasis on weatherability, durability, and PFAS surfactant-free grades. Notably, Arkema announced a 20 percent expansion of Kynar PVDF production capacity at its Changshu site in China, with startup planned for 2028 to support demand in coatings and other applications. This capacity move signals a deliberate alignment with Asia-Pacific demand growth and underscores the strategic importance of resin supply availability in the coming years. Earlier, in June 2025, Arkema highlighted Kynar Aquatec waterborne low-VOC protective coatings for architectural applications, offering extended durability and reflectivity compared to traditional systems, illustrating the formulation innovation trajectory toward lower-emission architectures.
Solvay, based in Belgium, supplies Hylar PVDF resins used by licensed formulators for premium 70 percent PVDF fluorocarbon coatings focused on long-term color retention and architectural metal protection. Its resin-centric model highlights the partnership dynamics that shape the formulated coatings tier, where resin availability, grade consistency, and technical support directly influence downstream product performance and brand reputation.
PPG Industries and Sherwin-Williams, both headquartered in the United States, operate at the formulated coating end of the value chain. PPG formulates and supplies PVDF-based fluorocarbon coatings for architectural and industrial uses, leveraging high-durability resin systems for metal substrates. Sherwin-Williams markets Fluropon and other 70 percent PVDF fluorocarbon coatings for coil and extrusion on architectural metal, delivering superior color retention and longevity. Their market presence reflects the premiumization trend in architectural metal finishing, where performance claims around color stability, gloss retention, and substrate protection differentiate brands in specification-driven procurement environments.
AkzoNobel, headquartered in the Netherlands, produces PVDF fluorocarbon coatings for architectural applications, offering weather-resistant solutions for metal cladding and building exteriors. Daikin Industries and Kureha Corporation, both Japan-based manufacturers, produce PVDF resins suitable for fluorocarbon coatings and broader fluoropolymer applications, with emphasis on chemical resistance and durability. Together, these companies form a competitive ecosystem in which resin supply, formulation capability, and regional service networks interact to determine market positioning.
The report's competitive analysis goes beyond corporate profiling. It evaluates how recent capacity decisions, product advancements, and formulation shifts alter relative positioning across regions and end-use segments. Executives gain a structured view of where competitive intensity is rising, where proprietary technology or supply relationships create defensibility, and where market entry or partnership opportunities may emerge as incumbents reallocate resources.
Formulation Evolution and Regulatory Pressures
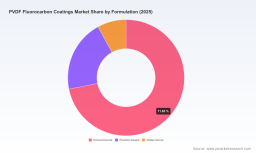
Formulation strategy has become a decisive competitive variable. The market spans solvent-borne, powder-based, and water-borne formulations, each responding differently to performance requirements, application conditions, and environmental regulation. The report analyzes how these formulation categories are evolving as manufacturers balance durability benchmarks against emissions constraints and processing economics.
Regulatory pressure is reshaping formulation priorities across key markets. Tightening VOC emission standards and PFAS-related scrutiny in North America and Europe influence the formulation of PVDF fluorocarbon coatings toward low-VOC and surfactant-free options. These dynamics are not abstract compliance issues; they affect product specifications, qualification cycles, and customer adoption timelines. Formulators that anticipate regulatory direction and align their portfolios accordingly gain a faster path to specification inclusion and repeat procurement.
At the same time, raw material conditions continue to inject cost volatility into the supply chain. In Northeast Asia, PVDF price stood at 15.36 USD per kilogram in April 2026, reflecting a 2.7 percent increase. Environmental clampdowns in Jiangsu and Shandong provinces in China led to 10-12 percent cost spikes for PVDF production, and vinylidene fluoride monomer raw material costs for PVDF increased significantly, contributing to overall production cost pressures. These cost dynamics interact with formulation choices, regional sourcing strategies, and pricing negotiation leverage. The report translates these pressures into strategic recommendations for cost pass-through management, inventory timing, and supplier diversification.
Application Demand and Regional Expansion Patterns
End-use demand provides the structural foundation for market growth. Architectural construction represents the dominant application category, driven by sustained demand for weather-resistant metal cladding, building exteriors, and long-life coil and extrusion coatings. Industrial equipment applications contribute a substantial secondary demand stream, where corrosion resistance and chemical durability justify premium coating solutions. Automotive, electrical and electronics, and other end-use segments add diversified demand that supports overall market resilience and expands the addressable base for specialized formulations.
Regional dynamics reveal a market with clear geographic hierarchy and shifting momentum. Asia Pacific stands as the largest revenue region, reflecting the concentration of construction activity, industrial manufacturing, and infrastructure investment. North America and Europe follow as mature but still strategically significant markets, where premium specifications, replacement cycles, and regulatory-driven formulation upgrades sustain demand. The Middle East and Africa, along with Latin America, contribute additional growth vectors tied to urbanization, industrial development, and coatings adoption in emerging applications.
The report examines how regional demand patterns interact with capacity location, pricing differentials, and specification influence. For multinational coating suppliers, understanding the relative weight of each region is not enough; it is equally important to grasp how local regulatory environments, construction cycles, and industrial procurement practices shape volume timing and margin profiles. This regional granularity supports market entry assessment, channel strategy refinement, and localized product positioning decisions.
Polyvinylidene Difluoride (PVDF) Market
Concentration Dynamics and Sourcing Strategy Implications
Market concentration remains a defining feature of the PVDF fluorocarbon coatings landscape. The combined share of the top three competitors reaches 42.15 percent, while the top five account for 58.6 percent. This level of concentration indicates that a relatively small group of established players exercises substantial influence over resin supply, formulation standards, and specification capture in premium applications.
For downstream formulators and end-user procurement teams, concentration carries both risk and opportunity. On the risk side, reliance on a narrow set of resin suppliers or coating manufacturers can expose procurement to capacity constraints, price adjustments, and qualification bottlenecks. On the opportunity side, the concentrated structure rewards strategic supplier relationships, long-term contracting, and technical collaboration that can secure consistent supply and preferential access to advanced grades. The report evaluates these concentration dynamics in the context of recent capacity expansion announcements and monomer cost pressures, helping organizations design sourcing strategies that balance resilience with cost efficiency.
What the Report Delivers for 2026 Decision-Making
This research is built as an operational intelligence platform rather than a high-level market summary. It provides the analytical scaffolding needed to connect market structure to commercial execution. The report includes detailed segmentation analysis across formulation types and end-use applications, regional market sizing that captures local demand intensity, and competitive profiling that compares strategic positioning, product architecture, and recent corporate moves.
Readers gain access to year-by-year market sizing through 2032, segment-level revenue breakdowns, and concentration metrics that quantify competitive structure. The report integrates recent industry developments, including capacity expansion timelines, product advancement milestones, raw material price movements, and regulatory change trajectories, into a unified analytical framework. This integration allows decision-makers to see how individual events fit into broader market dynamics rather than evaluating them in isolation.
The output is designed to support practical decisions: how to prioritize formulation investments in response to VOC and PFAS-related shifts; where to focus sales and specification efforts as regional demand patterns evolve; how to structure procurement and inventory strategies around raw material volatility; and how to benchmark competitive positioning against capacity and portfolio moves by leading players. Each section is written to feed directly into strategy workshops, procurement reviews, and competitive planning cycles.
Accessing the Complete Intelligence Package
The intersection of sustained market growth, formulation transition, raw material volatility, and regulatory evolution makes the PVDF fluorocarbon coatings market a strategic priority for organizations operating across construction, industrial equipment, automotive, and electrical applications. Navigating this environment requires more than headline market size and growth rates; it demands segment-level visibility, competitive context, and forward-looking scenarios that connect external market dynamics to internal planning assumptions.
PW Consulting's Worldwide PVDF Fluorocarbon Coatings Market report provides that depth. It is structured to serve as a reference point for executive teams seeking to align product strategy, sourcing strategy, and market expansion plans with a rigorous view of where the market is heading through 2032.
To access the complete dataset, regional and segment breakdowns, full competitive profiles, and the detailed forecast model supporting this analysis, visit the source report page. The full report delivers the granularity required to convert market intelligence into precise, defensible strategic action for the 2026-2032 planning horizon.
For detailed analysis of this topic, please visit the official page: Worldwide PVDF Fluorocarbon Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


