



Global MRI Compatible IV Infusion Pumps Market to Hit $828M by 2032, 8.6% CAGR

Navigating the Magnetic Frontier: Strategic Imperatives in the Worldwide MRI Compatible IV Infusion Pumps Market
The intersection of high-resolution diagnostic imaging and critical care infusion therapy represents one of the most technically demanding and commercially significant niches in modern medical device markets. As healthcare systems worldwide consolidate imaging capabilities into centralized suites and hybrid operating environments, the requirement for infusion pumps that can operate safely within the intense magnetic fields of Magnetic Resonance Imaging scanners has evolved from a specialized want to a clinical necessity. Our latest Worldwide MRI Compatible IV Infusion Pumps Market research study provides a comprehensive, data-backed examination of this evolving ecosystem, offering executives, procurement directors, and R&D strategists a clear roadmap for navigating an 8.6% compound annual growth trajectory through the 2032 forecast horizon.
This market intelligence report is engineered not merely as a statistical archive, but as an operational decision-support framework. Drawing on historical performance from 2020 through 2025 and extending our analytical models across 2026 to 2032, the study maps revenue expansion, competitive positioning, regulatory friction points, and procurement mechanics. For enterprise leaders evaluating capital allocation, supply chain resilience, and clinical workflow integration, the research delivers the contextual precision required to move from reactive participation to proactive market shaping. Below, we outline the strategic architecture of the study, illuminate the core dynamics driving adoption, and demonstrate why timing and technical differentiation will define market leadership in the coming cycle.
Market Architecture and Growth Vectors
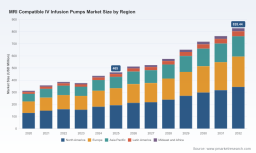
The global market for MRI compatible IV infusion pumps has demonstrated consistent structural expansion, with overall valuation scaling from approximately 312 million USD in the 2020 baseline through to a projected 828 million USD by the 2032 forecast terminus. The trajectory reflects a compound annual growth rate of 8.6 percent, a pace that outpaces general infusion pump market averages and underscores the accelerating convergence of advanced imaging volumes and complex infusion protocols. The 2025 base year valuation of 465 million USD establishes a mature but still expanding commercial landscape, driven by recurring replacement cycles, hospital infrastructure modernization, and the clinical imperative to maintain continuous medication delivery during prolonged MRI procedures.
Historical data reveals a resilient growth pattern, with performance holding steady despite broader macroeconomic volatility in healthcare capital equipment procurement. The 2023 dip to 376 million USD, followed by a robust rebound to 435 million USD in 2024, illustrates how procurement hesitation during economic recalibration quickly yields to renewed procurement urgency once clinical workflows recognize the operational risks of non-compatible infusion alternatives. Looking forward, the forecast period projects sustained expansion across all major revenue streams, with 2026 positioning at 512 million USD and the late-decade corridor accelerating toward the 700 to 800 million USD range. This growth is not merely volume-driven; it reflects structural upgrades in technology portfolios, regulatory pathway maturation, and institutional procurement frameworks that increasingly recognize the unique safety and performance requirements of magnetic environment operations.
Core Segmentation and Clinical Adoption Logic
The market is stratified across pump design architectures, clinical deployment environments, and geographic procurement clusters, each reflecting distinct workflow demands and capital planning rhythms. By pump architecture, the landscape splits between syringe-driven and volumetric delivery systems, with syringe-based configurations commanding a leading share of installed revenue. These systems are particularly favored in neuroimaging, contrast administration, and pediatric protocols where precise low-volume delivery and compact form factors are prioritized. Volumetric platforms, meanwhile, serve high-volume fluid administration, large-volume medication reservoirs, and extended-duration infusion workflows common in interventional radiology suites and hybrid procedural environments. Both segments benefit from continuous engineering refinement, yet their adoption curves diverge based on institutional procurement priorities, staff training familiarity, and the specific imaging modalities most frequently utilized within a given health system.
Clinically, hospital environments dominate deployment volume, anchoring the majority of procurement activity across acute care networks, integrated delivery systems, and academic medical centers. Diagnostic imaging centers constitute the second major adoption pillar, reflecting specialized outpatient workflows where MRI procedure throughput is high and infusion compatibility requirements are non-negotiable for safe contrast and sedation delivery. Ambulatory surgical centers, while representing a smaller volume footprint, are emerging as strategic growth nodes as facility consolidation and outpatient migration policies shift complex imaging-infusion protocols toward lower-acuity settings with stringent equipment standardization requirements. Procurement decisions across these settings increasingly balance upfront capital expenditure against total lifecycle cost, staff safety metrics, interoperability with existing medication management networks, and the regulatory liabilities associated with equipment failure or magnetic interference in high-stakes imaging environments.
Competitive Landscape and R&D Differentiation
The competitive architecture of this market is characterized by high concentration, with leading manufacturers accounting for a substantial portion of consolidated industry revenue. This concentration does not indicate market stagnation; rather, it reflects the rigorous engineering, regulatory validation, and clinical workflow integration barriers that protect established players while simultaneously raising the competitive bar for new entrants. The marketplace is populated by a mix of specialized innovators and broad-spectrum infusion therapy leaders, each pursuing distinct value propositions around magnetic shielding, non-magnetic motor technology, wireless remote control capability, drug library integration, and interoperability with hospital information systems.
IRadimed Corporation has institutionalized its leadership through a focused engineering philosophy that prioritizes non-magnetic construction for operation inside MRI environments up to 10,000 gauss. Its MRidium 3860+ platform, along with the newly cleared MRidium 3870 system, exemplifies the industry trajectory toward ultrasonic motor technology, touchscreen interfaces, and updated drug libraries that streamline workflow while preserving strict magnetic compatibility. B. Braun Melsungen AG approaches the market through the SpaceStation MRI system, a shielded configuration that enables up to four Space infusion pumps, including large-volume and syringe variants, to operate safely during MRI examinations across adult, pediatric, and neonatal patient populations. Baxter International Inc., Fresenius Kabi AG, and Becton, Dickinson and Company (BD) embed MRI-compatible considerations within broader infusion therapy portfolios, emphasizing hospital-scale deployment, reliability, and integration with existing medication management ecosystems. ICU Medical, Inc., including its Smiths Medical legacy portfolio, and Arcomed AG extend the competitive field with precision IV pump architectures and MRI-compatible options designed for diverse clinical environments. Moog Medical (Curlin) contributes ambulatory and multi-therapy infusion pump capabilities that support specialized settings where portability, durability, and protocol flexibility intersect.
Regulatory, Procurement, and Lifecycle Dynamics
The commercial viability of MRI compatible infusion pumps is tightly coupled to regulatory clearance pathways, procurement justification frameworks, and capital equipment lifecycle planning. Recent regulatory milestones underscore how clinical safety protocols, engineering validation, and classification pathways intersect to shape market entry velocity. In May 2025, IRadimed Corporation received FDA 510(k) clearance for the MRidium 3870 MRI Infusion Pump System, with the clearance specifying a Class II device classification for the delivery of IV fluids and medications in MRI environments. This regulatory milestone reflects the broader FDA expectation framework for infusion pump total product lifecycle management, which emphasizes additional pre-market clinical and human factors data for new or modified pump submissions. The clearance architecture not only validates device safety for magnetic environment use but also signals to health systems and procurement officers that the technology has cleared structured equivalence and performance benchmarks.
Worldwide MRI Compatible IV Infusion Pumps Market
Procurement mechanics represent an equally critical dynamic. Institutional buyers increasingly rely on sole source justification frameworks for highly specialized non-magnetic MRI compatible infusion pumps, recognizing that unique safety requirements in magnetic resonance environments constrain competitive bidding parameters. The U.S. Department of Veterans Affairs procurement process, for example, has formally acknowledged this dynamic, issuing a notice of intent for a sole source award for MRidium 3870 MRI IV pump units, accessories, software licenses, and training based on the device's status as a non-magnetic MRI compatible infusion pump. Such procurement approaches reduce competitive friction in highly technical categories while reinforcing the value proposition of devices engineered specifically for magnetic safety compliance.
Capital equipment lifecycle planning further shapes purchase timing and replacement forecasting. Institutional depreciation schedules and capital planning benchmarks frequently reference useful life standards for infusion pumps that directly influence procurement cadence, budgeting horizons, and technology refresh cycles. As installed bases age and clinical workflows demand more sophisticated interfaces, drug library capabilities, and interoperability features, replacement cycles accelerate and create recurring revenue opportunities for manufacturers that can demonstrate clear clinical workflow improvements and safety enhancements over legacy configurations. The interplay between aging equipment infrastructure, regulatory updates, and evolving clinical protocols creates a continuous refresh dynamic that sustains market momentum across the forecast period.
Why This Research Is a 2026 Decision-Making Asset
For executives and strategic planners, market intelligence must do more than summarize historical performance. It must translate data into trade-off analysis, competitive positioning guidance, procurement strategy recommendations, and technology investment roadmaps. This Worldwide MRI Compatible IV Infusion Pumps Market research study is structured to deliver precisely that operational utility. The report provides granular coverage of segment dynamics across pump architectures, clinical application settings, and geographic procurement clusters, mapping revenue distribution patterns and adoption drivers without forcing decision-makers to reassemble fragmented competitor intelligence. Instead, the study consolidates competitive profiles, recent regulatory and procurement developments, and structural market concentration metrics into a single strategic reference framework.
Elastomeric Infusion Pumps Market
Readers will find detailed profiling of the market's leading participants, including engineering differentiators, portfolio positioning, and recent clearance or procurement milestones that signal near-term market movement. The study contextualizes these developments within broader industry dynamics, including regulatory expectations for infusion pump lifecycle management, procurement justification mechanics for specialized non-magnetic devices, capital equipment useful life benchmarks, and the operational consequences of legacy equipment replacement cycles. By aligning historical data with forward-looking analytical models, the research supports scenario planning for capital allocation, supply chain and aftermarket service strategy, product portfolio investment, and competitive response planning.
Importantly, the report is designed to surface the institutional and clinical logic behind procurement behavior, not just the surface-level numbers. Decision-makers in hospital administration, imaging center operations, ambulatory facility planning, and device R&D can use the analysis to anticipate shift patterns in procurement criteria, evaluate the strategic implications of sole source dynamics in specialized safety categories, and assess the relative durability of technology moats built around non-magnetic motor architectures, wireless remote control integration, and drug library sophistication. The study bridges the gap between regulatory and procurement reality and commercial strategy, equipping leadership teams with the insights needed to align product development, pricing architecture, and market access planning with the structural realities of this niche.
Strategic Positioning for the Next Growth Cycle
As the Worldwide MRI Compatible IV Infusion Pumps Market advances along its projected growth corridor, the institutional pressures shaping procurement will intensify rather than recede. Hybrid imaging environments, outpatient migration, neonate and pediatric protocol expansion, and the clinical premium on uninterrupted infusion delivery during high-stakes imaging procedures will continue to elevate the strategic importance of magnetic-compatible infusion technology. Simultaneously, competitive intensity will reward manufacturers that can synchronize engineering innovation with regulatory fluency, procurement-ready documentation, and interoperability features that align with hospital medication management networks and capital planning realities.
The firms best positioned to capture disproportionate value across the 2026 to 2032 horizon will be those that treat MRI compatibility not as an accessory feature but as a core engineering discipline integrated into pump architecture, user interface design, drug library management, serviceability, and procurement enablement. Executive teams that understand the lifecycle economics, procurement justification mechanics, and segment-specific workflow priorities will be better equipped to optimize market entry timing, pricing strategies, and channel partnerships. They will also be more capable of anticipating replacement cycle accelerations as aging installed bases confront the growing incompatibility gap between legacy equipment and modern imaging environments.
This research delivers the analytical foundation to make those strategic calls with confidence. By consolidating market size trajectories, competitive profiling, regulatory and procurement dynamics, and segmentation logic into a single actionable framework, the study supports precise decision-making for the 2026 operating cycle and beyond. For organizations seeking to sharpen their competitive positioning, optimize capital deployment, or validate R&D investment priorities in the MRI compatible infusion pump space, the full report provides the detailed intelligence needed to move beyond assumptions and into structured, evidence-based strategy.
For detailed analysis of this topic, please visit the official page: Worldwide MRI Compatible IV Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


