



PW Consulting Report: Zero-Point Clamping Market Hits $633.19M in 2025, To Hit $987.21M by 2032

Unlocking Precision and Speed: Strategic Insights into the Global Zero-Point Clamping System Market 2026–2032
In the high-stakes environment of modern manufacturing, the margin between profitability and obsolescence often comes down to seconds. Every minute spent on machine setup is a minute of lost capacity. As we move deeper into 2026, the imperative for high-mix, low-volume production environments has never been more critical. The global Zero-point Clamping System market stands at the forefront of this operational shift, offering the technological backbone required for rapid changeovers, lights-out production, and uncompromising precision. Our latest Worldwide Zero-point Clamping System Market study is not merely a collection of statistics; it is a strategic compass designed to navigate the complex interplay of technological innovation, regional dynamics, and competitive intensity that defines this sector through 2032.
The Macro Economic Trajectory: A Decade of Sustained Growth
Understanding the broader market trajectory is the first step in strategic planning. The data reveals a robust growth story that extends well beyond temporary fluctuations. In our base year of 2025, the global market for zero-point clamping systems established a significant revenue baseline. Looking forward, the forecast period from 2026 to 2032 projects a steady and compelling compound annual growth rate (CAGR). This growth is not accidental; it is the direct result of manufacturing industries prioritizing efficiency metrics that were previously secondary to raw output.
Historical analysis covering the period from 2020 to 2025 shows a consistent upward trend in revenue valuation, measured in millions of USD. This historical resilience sets the stage for the future. The market size is expected to expand significantly by the end of the forecast period in 2032. For enterprise strategists, this indicates a healthy ecosystem where investment in clamping technology is viewed as a capital expenditure with demonstrable returns in operational throughput. The shift from manual intervention to automated, repeatable clamping solutions is becoming a standard rather than a luxury. However, the aggregate numbers only tell part of the story. The true value for decision-makers lies in understanding the velocity of adoption across different actuation technologies, the specific demands of key application verticals, and the uneven distribution of market revenue across global regions. These nuanced layers of data are essential for identifying where the next pockets of growth will emerge.
Industry Dynamics: The Drivers of Change in 2026
Several macro trends are converging to accelerate the adoption of zero-point clamping technology. The primary driver remains the urgent need to reduce setup times. In high-mix production environments, traditional workholding methods often create bottlenecks. Industry leaders highlight that implementing zero-point systems can reduce setup times by up to 90%. This efficiency gain directly translates to increased machine capacity, allowing manufacturers to run more batches or dedicate more time to actual cutting operations.
Furthermore, the integration of these systems into the broader Industry 4.0 framework is a critical dynamic. Zero-point clamping systems provide standardized, repeatable interfaces that are essential for CNC and robotic handling. This standardization enables lights-out production scenarios where machines operate autonomously overnight or during weekends. For corporations aiming to reduce labor dependency and mitigate supply chain volatility, the ability to run unmanned shifts is a strategic advantage that hinges on reliable workholding technology.
Precision and repeatability are also key factors capping the ceiling of market growth. Modern systems are engineered to compensate for thermal expansion with symmetrical fixed zero points and clearance-free fits. Achievement of repeat accuracy below 2.5 micrometers allows for tighter tolerances in finished parts, which is particularly vital in sectors where component failure is not an option. Additionally, the materials used in these systems are critical. High-strength hardened alloy steel components, often treated to approximately 57 HRC, ensure durability and precision under heavy loads. This material specification underscores the engineering rigor required to maintain system integrity over thousands of clamping cycles.
Report Scope and Operational Content
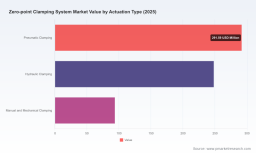
Our comprehensive study is structured to provide actionable intelligence rather than abstract theory. The report delves into the segmentation of the market by actuation type, covering pneumatic, hydraulic, and manual mechanical clamping solutions. Each actuation type offers distinct advantages regarding speed, force, and integration complexity. The analysis extends to the application landscape, dissecting demand across automotive manufacturing, aerospace and defense, medical device manufacturing, and general machinery and tooling. Each vertical presents unique challenges regarding vibration resistance, clamping force requirements, and cycle times.
Regional analysis is another cornerstone of this research. We examine the market concentration across Europe, Asia Pacific, North America, and the Rest of World. Understanding the regional distribution of revenue is vital for supply chain planning and market entry strategies. The report also scrutinizes the competitive landscape, analyzing market concentration metrics to understand the balance between dominant incumbents and emerging challengers. This includes an assessment of the top players who command significant market share, providing insight into pricing power and consolidation trends.
- Segmentation Analysis: Deep dives into actuation types and application verticals to identify high-growth niches.
- Regional Breakdown: Country and region-specific revenue trends to support geographic expansion or sourcing decisions.
- Competitive Intelligence: Profiles of key industry players, including their strategic moves, product launches, and exhibition activities.
- Investment Viability: Identification of high-value segments where capital deployment yields the highest return on investment.
Key Enterprise Profiles and Strategic Moves
The competitive arena is populated by specialized manufacturers who have anchored their reputations on precision and reliability. STARK Spannsysteme GmbH, part of the ROEMHELD Group, continues to pioneer zero-point clamping technology. Their solutions focus on fast, precise workpiece and fixture clamping in CNC machining, optimizing setup time across milling, turning, and automation. Similarly, LANG Technik GmbH offers the Quick•Point® system, known for modular 52 mm and 96 mm grids that emphasize versatility and retrofitting capabilities on various CNC machines.
The Zimmer Group provides modular systems suitable for milling, turning, EDM, and grinding, emphasizing error reduction. HAINBUCH GmbH offers the DockLock system for stationary applications, enabling quick change-over of clamping devices in under two minutes with form-fit clamping. SMW-AUTOBLOK supplies systems including APS series modules with turbo functions for enhanced pull-down force and sealed designs. EROWA AG specializes in systems optimized for automated CNC manufacturing and lights-out production, integrating loading units with platforms for EDM, milling, and measurement.
In the Americas, Jergens Inc. supplies a Zero Point System that combines fixing, positioning, and clamping in one step, reducing setup times by up to 90%. SCHUNK GmbH & Co. KG provides Vero-S and other solutions widely referenced for precision workholding. NIKKEN Kosakusho Works Ltd., operating in Japan and the USA, develops integrated technology directly into rotary tables to maintain machine rigidity without additional stack height.
Recent activity indicates a vibrant pipeline of innovation. Gressel AG released new plate modules for their gre4doc system in early 2025. The ROEMHELD Group and Gressel both showcased their technologies at EMO Hannover 2025. NIKKEN highlighted integrated zero-point clamping in their 5AX-201 rotary table in March 2025. AMF Andreas Maier GmbH & Co. KG published a comprehensive catalog covering mechanical, hydraulic, and pneumatic modules. These developments signal that the industry is not static; product lifecycles are active, and competition is fierce.
Competitive Landscape and Market Concentration
The market structure is characterized by a concentration of revenue among a core group of established players. Analysis of market concentration reveals that a significant portion of the total revenue is held by the top companies. This concentration suggests strong brand loyalty, high barriers to entry regarding precision engineering certifications, and the importance of existing customer relationships in CNC machining networks. However, the presence of specialized manufacturers, such as ZeroClamp GmbH and Suzhou SET Industrial Equipment System Co., Ltd., indicates niche opportunities where specific value propositions like extreme repeat accuracy or custom high-precision solutions can carve out market share.
Worldwide Zero-point Clamping System Market
Strategic decisions for 2026 must account for this landscape. Whether a company is looking to source clamping technology to improve internal operations or considering market entry, understanding the capabilities of competitors like STARK, LANG, and EROWA is essential. These companies are not just selling hardware; they are selling uptime and precision. Their recent trade show exhibitions and catalog releases demonstrate a commitment to continuous improvement and adaptation to new machining requirements, such as additive manufacturing compatibility seen in recent presentations by companies like LEHMANN.
Magnetic Clamping Technology Market
Strategic Recommendations for 2026 Decision Makers
As we navigate 2026, the integration of zero-point clamping systems should be viewed through the lens of total cost of ownership rather than just initial procurement cost. The reduction in setup time allows for quicker changeovers, which is critical for the demand for customization in automotive and medical sectors. In aerospace and defense, the emphasis on error reduction and material durability aligns with the stringent quality standards required.
For manufacturers, the first step is evaluating current bottlenecks. If setup times are consuming significant machine availability, the ROI on zero-point systems is likely clear. For investors and analysts, the growth trajectory suggests that companies enabling high-mix, low-volume production will continue to see favorable conditions. The technology supports the macro trend of reducing labor intensity while increasing output quality. Supply chain managers should also note the importance of material specifications, such as the hardness of steel components, which impacts longevity and maintenance schedules.
The data presented in this overview serves as a foundation. The specific percentages of regional revenue splits, the exact valuation of each actuation segment, and the detailed share percentages of the top five competitors require a deeper dive into the full analysis. These granular details are necessary for precise budgeting and strategic targeting. For example, while the broad strokes show strong growth, the specific disparity between pneumatic and hydraulic adoption rates in specific regions can dictate sourcing strategies.
Conclusion: Accessing the Full Intelligence
The Worldwide Zero-point Clamping System Market is evolving from a niche component supply chain to a critical enabler of modern manufacturing efficiency. The projected growth through 2032 reflects a structural shift in how workpieces are held, positioned, and changed. The competitive landscape is dynamic, with established German and Swiss engineering prowess coexisting with innovative solutions from Japan and emerging players in China. Recent product launches and trade show demonstrations confirm that innovation is accelerating, particularly in areas related to automation integration and thermal management.
While this article provides a strategic overview of market dynamics, segmentation drivers, and competitive profiles, it is designed as a preview of the comprehensive intelligence available in our full study. The aggregate figures and qualitative trends serve to establish context, but the detailed breakdown of market sizes, regional revenue splits, and compound growth rates for each sub-segment holds the specific data required for immediate tactical execution. To access the complete dataset, including the precise market valuation for each region and application, and to leverage the full competitive benchmarking, we invite you to explore the full Worldwide Zero-point Clamping System Market report. This resource is designed to equip stakeholders with the granular intelligence necessary to secure a competitive advantage in the precision engineering sector.
For detailed analysis of this topic, please visit the official page: Worldwide Zero-point Clamping System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


