



PW Consulting: Reusable Food Wrap Market Hits $245M in 2025, Projects 7.15% CAGR to 2032

The Reusable Food Wrap Revolution: Strategic Insights for Navigating Market Growth Through 2032
A PW Consulting Executive Preview
The global transition away from single-use plastics has moved from a niche consumer preference to a mainstream operational imperative. For businesses operating in the food storage, packaging, and sustainable goods sectors, the reusable food wrap market represents one of the most dynamic growth vectors of the decade. Our latest comprehensive study, Worldwide Reusable Food Wrap Market, offers a granular, data-driven roadmap for navigating this evolving landscape. This article serves as a strategic preview, outlining the macro-trajectory, the competitive architecture, and the regulatory catalysts that will define market winners between 2026 and 2032.
The Macro Trajectory: From Recovery to Accelerating Expansion
Over the past half-decade, the worldwide reusable food wrap market has demonstrated a robust recovery and expansion phase. Historical revenue data from 2020 through 2025 illustrates a clear upward trajectory, with the market size climbing from 173.46 million USD to a projected 245.0 million USD. This growth reflects not only the post-pandemic normalization of supply chains but also a structural shift in consumer purchasing behavior. As households and commercial kitchens increasingly prioritize waste reduction, demand for breathable, plastic-free alternatives has cemented itself as a recurring revenue stream rather than a transient trend.
Looking forward to the forecast period spanning 2026 to 2032, the market is positioned for sustained expansion. The projected compound annual growth rate of 7.15 percent signals that the sector will outperform many traditional consumer goods categories. By 2032, the overall market revenue is expected to reach 397.3 million USD. For corporate strategists, this CAGR implies a compounding opportunity: early movers who establish distribution networks, brand loyalty, and regulatory compliance frameworks today will capture disproportionate market share as the total addressable market expands. The forecast also highlights year-over-year inflection points, such as the jump toward 315.56 million USD in 2028, suggesting that regulatory deadlines and commercial adoption curves will likely accelerate demand velocity in the latter half of the forecast window.
It is crucial for decision-makers to understand that these macro figures represent the aggregate of distinct regional performances, product typologies, and end-use applications. Our full report unpacks these layers systematically, providing the precise volume and value breakdowns required for regional go-to-market planning, product portfolio optimization, and capacity allocation. However, the headline trend is unambiguous: the market is scaling, and the pace of scaling is tightening around a consistent mid-single-digit growth rate that rewards strategic foresight over reactive positioning.
Decoding the Competitive Architecture
The reusable food wrap sector is characterized by a moderately fragmented but strategically consolidating competitive landscape. Market concentration metrics indicate that the top three players command approximately 28.5 percent of total revenue, while the top five hold around 36.2 percent. This distribution suggests that while no single entity dominates the global stage, established brands with strong product differentiation, ethical sourcing narratives, and supply chain resilience are capturing meaningful pockets of influence. The remaining market share is distributed among a vibrant ecosystem of specialized manufacturers, regional producers, and emerging direct-to-consumer brands, creating a highly dynamic environment for both competition and partnership.
Key incumbents exemplify the strategic pillars driving success in this space. Bee's Wrap, LLC, headquartered in Vermont, has positioned itself as a pioneering brand by offering reusable beeswax food wraps crafted from GOTS-certified organic cotton, ethically sourced beeswax, jojoba oil, and tree resin. Their emphasis on breathable, plastic-free alternatives across various sizes and patterns demonstrates how product variety and material transparency can build enduring consumer trust. Similarly, Abeego Designs Inc. from Canada has capitalized on the original beeswax food storage wrap concept, designing products that allow food to breathe while protecting it. Their focus on extending the freshness of produce, cheese, and bread aligns tightly with the narrative of reducing household food waste, a powerful purchase driver.
Reusable Water Bottle Market
The competitive field also includes Etee, another Canadian player providing organic reusable food wraps and zero-waste products that serve as sustainable alternatives to single-use plastics. LilyBee Wrap targets eco-conscious consumers with organic cotton beeswax wrappers featuring diverse designs, highlighting the importance of aesthetic differentiation alongside functional sustainability. The Beeswax Wrap Company Ltd operates as a manufacturer and supplier focused on reusable, biodegradable options for household food preservation, illustrating the role of dedicated B2B and wholesale channels in scaling distribution. Keep Leaf integrates reusable food wraps into a broader sustainable kitchen product line, emphasizing eco-friendly materials that resonate with lifestyle-focused retail assortments.
Further down the value chain, U-KONSERVE offers reusable food storage solutions including wraps that prioritize durable, sustainable alternatives to disposable plastics. Khala & Company provides beeswax wraps and related eco-products with an emphasis on natural and ethical sourcing, reinforcing how supply chain integrity has become a competitive differentiator. SuperBee supplies beeswax wraps and eco-friendly products compliant with various dietary and manufacturing standards, targeting sustainable food storage with a framework that appeals to regulated and quality-conscious markets. Honeywrap and Apiwraps both offer beeswax-based reusable food wraps for everyday kitchen use, representing the steady demand from brands that focus on everyday utility and repeatable purchase cycles.
On the manufacturing and export frontier, Henan Green Wrap Products Co., Ltd in China operates as a large-scale manufacturer of beeswax wraps, vegan wraps, and related products compliant with LFGB, REACH, and FDA standards, while offering OEM/ODM services. This profile underscores the strategic importance of regulatory compliance and flexible manufacturing partnerships for brands seeking to scale internationally or launch private-label offerings. Green Wrap, also based in China, positions itself as an experienced manufacturer of reusable beeswax food wraps and bags, emphasizing stable quality and efficient production. Together, these manufacturers illustrate how production capacity, certification portfolios, and service models are reshaping the competitive dynamics beyond consumer-facing brands.
For executives, the central insight is that competition in this market is multidimensional. It is not merely a price war; it is a contest over material credibility, product performance, regulatory readiness, and supply chain agility. Our full report provides detailed comparative assessments that help brands identify white-space opportunities, benchmark against incumbents, and evaluate potential acquisition or partnership targets within this ecosystem.
Regulatory Catalysts and Raw Material Realities Shaping the Demand Curve
Market growth in the reusable food wrap sector cannot be understood in isolation from the regulatory environment. Policy interventions across multiple jurisdictions are actively reshaping end-user demand and creating compliance-driven purchasing behavior. In the United States, California's SB 54 mandates that 100 percent of single-use packaging and food service ware sold in the state must be recyclable or compostable by 2032. This legislative trajectory is a powerful demand catalyst for reusable alternatives, as food service operators and packaging suppliers seek compliant, scalable solutions that can meet both environmental targets and operational practicality. The regulation effectively expands the commercial addressable market by forcing a structural shift in procurement priorities.
Beyond California, a cascade of state-level actions is tightening the regulatory perimeter around single-use plastics. New Jersey's law prohibits food service businesses from providing single-use utensils and condiments under certain conditions, effective August 1, 2026. Georgia has implemented a ban on single-use plastic food packaging and foodware for food service establishments, effective July 1, 2026. These measures, documented by CalRecycle and the New Jersey Department of Environmental Protection, among other sources, signal a clear policy direction: single-use disposables are increasingly constrained, and reusable, durable alternatives are moving from optional sustainability enhancements to baseline compliance requirements. For commercial end-users and the brands that supply them, this regulatory cadence creates both urgency and a multi-year window to align product portfolios with evolving mandates.
At the same time, raw material dynamics introduce both opportunity and risk. Beeswax, a foundational input for many reusable wrap products, has experienced notable price volatility. In late 2025, visible trade data indicated that US beeswax transaction prices reached approximately 18.29 USD per kilogram. Meanwhile, the global average beeswax export price in 2024 was recorded at 6,311 USD per ton. These figures highlight the importance of input cost monitoring, supplier diversification, and formulation strategies that can buffer margin pressure. Brands that rely heavily on beeswax must navigate geographic sourcing variations, certification requirements, and seasonal supply fluctuations, while manufacturers of vegan or alternative-material wraps must track the cost and performance trajectories of their own material substitutes. Our research integrates these raw material realities into the broader demand forecast, enabling clients to model sensitivity scenarios and make informed sourcing decisions.
Inside the Report: Practical Intelligence for Strategic Execution
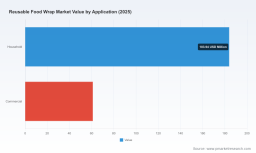
The Worldwide Reusable Food Wrap Market study is designed as an operational decision-support tool, not merely a high-level overview. It provides a structured exploration of the market's foundational drivers, restraints, and enabling factors, connecting macro forces to actionable business implications. Readers gain access to a detailed segmentation analysis that dissects the market by region, by product type, and by application, allowing stakeholders to pinpoint where growth is concentrating and where competitive intensity is rising. This multi-dimensional segmentation is essential for companies evaluating market entry, expansion, or portfolio rebalancing, as it reveals the relative weight of household versus commercial demand and clarifies how product categories perform across different economic and regulatory contexts.
The report also includes comprehensive profiles of the key companies shaping the competitive landscape. Each profile examines brand positioning, material and sourcing strategies, product range breadth, compliance frameworks, and distribution approaches. By mapping these profiles against market share and concentration metrics, the study helps clients identify competitive gaps, evaluate benchmarking targets, and anticipate likely strategic moves from both established players and agile challengers. For investors and corporate development teams, this company-level intelligence supports due diligence, partnership screening, and market positioning exercises with a clear view of who is leading in which segment and why.
Worldwide Reusable Food Wrap Market
Beyond segmentation and company analysis, the study embeds the regulatory and raw material context directly into the market narrative. This integration ensures that forecasts are not developed in a vacuum; instead, they reflect the combined influence of legislation, material pricing, consumer behavior shifts, and supply chain capacity. The forecast period through 2032 is treated as a sequence of decision-relevant milestones, allowing clients to align product launches, capacity investments, and geographic prioritization with the most probable market inflection points. The result is a research asset that supports scenario planning, pricing strategy, channel mix optimization, and risk assessment within a single coherent framework.
Translating Insight into 2026 Decision-Making
As organizations move into 2026, the strategic imperative is to convert market awareness into structured action. The reusable food wrap market is large enough to reward focused investment, yet dynamic enough to penalize delayed or uninformed decisions. Companies that act early can secure distribution relationships, align product specifications with emerging regulatory expectations, and build brand equity around material transparency and performance reliability. Those that wait risk entering a market where compliance costs are higher, consumer expectations are more entrenched, and competitive positions are already defended by brands with multi-year head starts.
For consumer brands, the priority is to determine which product types and application segments offer the most defensible growth profile, then to calibrate pricing, packaging, and marketing around the value propositions that resonate with target buyers. For manufacturers and suppliers, the focus should be on certification readiness, production efficiency, and the ability to support OEM/ODM demand from brands seeking to scale quickly while maintaining quality and compliance. For investors and corporate strategists, the opportunity lies in identifying which companies possess the combination of material expertise, regulatory agility, and market reach needed to compound value as the forecast period unfolds.
The macro figures point to a market moving from 245.0 million USD in 2025 toward 397.3 million USD in 2032, with a CAGR of 7.15 percent anchoring a credible growth narrative. Yet the real strategic advantage comes from understanding the distribution of that growth: which regions are expanding fastest, which product types are gaining share, which applications are shifting from early adoption to mainstream procurement, and how regulatory timelines will compress decision windows. Those details are the difference between a general sense of optimism and a precise execution plan.
Access the Full Intelligence
This preview has outlined the structural forces, competitive architecture, and regulatory momentum defining the reusable food wrap market through 2032. To move from directional confidence to decision-ready precision, stakeholders need the complete dataset, segmentation matrices, company benchmarking, and forecast sensitivities contained in the full study. The detailed breakdown of regional performance, product-type dynamics, household versus commercial application splits, and raw material scenario modeling is available in the comprehensive Worldwide Reusable Food Wrap Market report. We invite executives, strategists, and investment teams to access the full research asset and equip their 2026 planning with the depth required to act decisively in a market that is scaling quickly and rewarding informed positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


