



PW Consulting: Global Freight Forwarding Market to Hit $200M in 2025, Grow at 4.55% CAGR to 2032

Navigating the Global Freight Forwarding Landscape: Strategic Intelligence for 2026 and Beyond
The international freight forwarding industry stands at a critical inflection point. As supply chains adapt to geopolitical shifts, regulatory pressures, and rapid technological transformation, organizations require more than surface-level market data to navigate the coming years with confidence. This comprehensive market research study delivers a rigorous, data-driven analysis of the Worldwide International Freight Forwarding Services Market, offering executives and strategy teams the actionable intelligence needed to make informed decisions across 2026 and the forecast horizon through 2032.
Drawing on historical performance data from 2020 through 2025 and projecting forward across a seven-year forecast period, this report captures both the cyclical volatility and the structural growth trajectories that define modern logistics ecosystems. The base year analysis establishes a clear foundation, while forward-looking projections equip decision-makers with the planning parameters necessary for capacity allocation, partnership strategies, and technology investment roadmaps.
Market Size Evolution and Growth Trajectory
The global freight forwarding market has demonstrated remarkable resilience despite confronting unprecedented disruptions over the past half-decade. Historical revenue figures reveal a market that weathered pronounced fluctuations before stabilizing and returning to a sustainable growth path. After reaching a valuation exceeding 174,000 million USD in 2020, the sector experienced a pronounced surge through 2022, driven by pandemic-era demand restructuring and inventory restocking cycles. The subsequent correction in 2023 and 2024 reflected normalization patterns as freight rates adjusted and consumer spending patterns shifted, yet the underlying demand fundamentals remained intact.
By the 2025 base year, the market had recovered to approximately 200,000 million USD, establishing a solid platform for forward expansion. The forecast period from 2026 through 2032 charts a steady upward trajectory, with projected revenues expanding from roughly 203,300 million USD in 2026 to over 273,000 million USD by 2032. This growth reflects a compound annual growth rate of 4.55 percent, a figure that underscores the sector's capacity to generate consistent value even amid fluctuating macroeconomic conditions. For enterprise planners, this growth rate provides a reliable benchmark for modeling revenue expectations, evaluating market entry opportunities, and calibrating long-term investment commitments.
Structural Segmentation: Where Value Is Created
Understanding the multidimensional structure of the freight forwarding market is essential for targeting the right opportunities and mitigating concentration risks. This report dissects the market across three critical analytical dimensions: geographic regions, transport modes, and end-use industries. Rather than presenting opaque aggregates, the analysis isolates the revenue contributions and growth characteristics of each segment, enabling stakeholders to identify high-potential corridors and service lines.
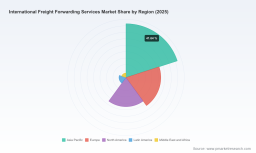
The geographic breakdown reveals distinct regional dynamics shaped by trade policy, infrastructure readiness, and industrial composition. Asia Pacific commands the largest revenue share, driven by manufacturing exports, intra-regional trade intensification, and expanding port infrastructure. Europe maintains a substantial position, supported by integrated multimodal networks and stringent regulatory frameworks that drive demand for compliance-forward logistics solutions. North America represents a mature but evolving market where e-commerce acceleration and nearshoring trends are reshaping forwarding volumes. Latin America and the Middle East and Africa, while smaller in absolute terms, present high-growth opportunities tied to emerging market industrialization, resource-sector logistics, and corridor development initiatives.
On the service mode front, the analysis differentiates between ocean freight, air freight, road and rail transport, and specialized other services. Ocean freight remains the dominant revenue contributor, reflecting the continued centrality of maritime shipping to global trade. Air freight sustains a significant share, buoyed by time-critical shipments, high-value goods, and resilience-driven routing decisions. Road and rail transport segments demonstrate steady demand, particularly in intra-continental corridors where multimodal integration offers cost and efficiency advantages. Complementary service lines, including customs brokerage, warehousing integration, and value-added logistics, represent differentiated niches where forwarders can capture margin premium.
End-use industry segmentation further clarifies where forwarding demand originates. Manufacturing remains the largest consumer of freight forwarding services, reflecting complex global sourcing networks and just-in-time production requirements. Retail and e-commerce continue to expand their logistics footprint, driven by consumer expectations for faster delivery and the proliferation of cross-border online commerce. Consumer goods, healthcare, and automotive and energy sectors each present distinct forwarding requirements shaped by regulatory standards, temperature control needs, hazardous materials handling, and project logistics complexity. By mapping forwarding demand to these end-use verticals, the report provides a practical lens for aligning service portfolios with sector-specific growth cycles.
Competitive Landscape and Market Concentration
The freight forwarding industry operates within a fragmented yet consolidating competitive environment. The analysis indicates a moderate level of market concentration, with the top three players collectively accounting for approximately 12.4 percent of total market revenue and the top five firms representing roughly 18.25 percent. This concentration profile suggests ample room for both established incumbents and specialized challengers to compete on service differentiation, digital capabilities, and regional expertise.
Several globally recognized enterprises define the competitive frontier, each pursuing distinct strategic positions. Kuehne + Nagel has reinforced its position as a leader across sea, air, and road forwarding by integrating digital platforms such as myKN to deliver end-to-end visibility and streamlined transaction workflows. DSV has expanded its comprehensive forwarding capabilities across all major transport modes while building distinctive strength in project logistics, culminating in a landmark acquisition of DB Schenker in September 2025 that created the world's largest freight forwarder by revenue. DB Schenker itself has built a strong reputation for ocean, air, and land forwarding with particular emphasis on automotive and healthcare verticals.
DHL Global Forwarding continues to lead in time-critical air freight and ocean forwarding, leveraging resilience capabilities such as resilience360 to provide supply chain visibility and risk mitigation. Expeditors International has differentiated itself through technology-driven operations, proprietary EDI systems, and a focus on air, ocean, and ground services that emphasize operational precision and client responsiveness. CEVA Logistics offers full-service forwarding integrated with contract logistics, targeting automotive and consumer sectors with coordinated supply chain solutions. UPS Supply Chain Solutions and FedEx Trade Networks bring the advantage of integrated global networks, with UPS emphasizing Quantum View tracking and FedEx specializing in customs brokerage alongside its air and ocean forwarding capabilities.
Regional and specialized players further enrich the competitive landscape. Nippon Express anchors strong Asia-Pacific trade lane expertise across air, sea, and rail services. Sinotrans provides integrated sea, air, and rail forwarding from a Chinese base with global reach. C.H. Robinson has scaled a digital freight forwarding platform through Navisphere, enabling ocean, air, and truck services with a technology-first operating model. Hellmann Worldwide Logistics, as a family-owned forwarder, combines air, sea, and contract logistics with cloud-based track and trace functionality. Geodis delivers multi-modal forwarding with notable strength in e-commerce and healthcare supply chains. Bolloré Logistics focuses on Africa and energy sector logistics via air and sea networks, while Agility Global Integrated Logistics targets emerging markets and provides integrated warehousing and forwarding services through its GWC operations.
Industry Dynamics Shaping Strategic Decisions
Market size and participant profiles alone do not capture the forces that will determine competitive outcomes in 2026 and beyond. A suite of operational, regulatory, and geopolitical dynamics exerts direct influence on forwarding costs, service reliability, and routing strategies. Understanding these forces is indispensable for scenario planning and risk management.
Fuel cost volatility remains a persistent pressure point. Ocean freight bunker fuel prices averaged approximately 650 USD per metric ton in the fourth quarter of 2025, representing a year-over-year increase of 15 percent driven in part by compliance costs associated with IMO 2020 sulfur regulations. For forwarding providers and their clients, fuel cost fluctuations translate directly into freight rate variability and require proactive hedging and pricing strategies.
Regulatory developments are adding new layers of compliance complexity and cost. The European Union Emissions Trading System was extended to shipping in 2025, imposing carbon-related costs on a portion of emissions for intra-EU voyages. This regulatory shift incentivizes carbon-efficient routing, modal optimization, and investment in greener equipment, while simultaneously affecting cost structures for European-facing trade lanes. Labor cost escalation represents another structural headwind. Global logistics labor costs rose by approximately 8 percent in 2025, propelled by port worker shortages across the United States and Europe. This tightening labor market pressures throughput capacity at key nodes and elevates the value of automation and workforce productivity initiatives.
Worldwide Freight Forwarding Service Provider Services Market
Trade policy and geopolitical events continue to reshape freight flows in ways that forwarding strategies must accommodate. Tariff actions, including the imposition of 25 percent tariffs on Chinese steel imports by the United States effective March 2025, have influenced forwarding volumes and routing decisions by altering the economics of specific trade corridors. Geopolitical disruptions have similarly forced adaptive responses. Red Sea disruptions rerouted a significant share of Asia-Europe container traffic via the Cape of Good Hope in early 2025, increasing transit times and fuel consumption while testing the resilience of forwarding networks. These events highlight the importance of diversified routing options, scenario-aware contingency planning, and real-time visibility capabilities that enable rapid response to unfolding disruptions.
Worldwide International Freight Forwarding Services Market
What This Research Delivers for Strategic Decision-Makers
This market research study is designed to translate complex market data into clear strategic guidance. The full report provides an extensive toolkit for executives, business development leaders, investors, and operations strategists. Key deliverables include:
- Detailed historical market sizing and forward projections segmented by region, transport mode, and end-use industry, enabling precise demand forecasting and market opportunity quantification.
- Competitive benchmarking across leading global forwarders, with analysis of strategic positioning, service portfolios, digital capabilities, and recent corporate developments such as acquisitions, platform launches, partnership initiatives, and major client engagements.
- Assessment of market concentration trends and their implications for pricing power, partnership dynamics, and competitive strategy.
- Analysis of the operational and regulatory forces affecting cost structures, route viability, and service reliability, including fuel cost patterns, emissions regulations, labor market conditions, tariff impacts, and geopolitical disruption scenarios.
- Strategic recommendations for aligning service offerings, technology investments, and regional expansion plans with the most promising growth vectors identified in the data.
By integrating quantitative market sizing with qualitative assessments of competitive and operational dynamics, the report equips organizations to move beyond reactive adjustments and toward proactive, evidence-based strategy formulation.
Why This Research Matters for 2026 Planning
The freight forwarding market of 2026 will be defined by organizations that can balance growth ambition with operational adaptability. The 4.55 percent compound annual growth rate projected through 2032 signals a market that continues to expand, but the path of that expansion will be uneven across regions, modes, and industries. Companies that understand where demand is concentrating, which competitors are capturing share, and how regulatory and cost pressures are evolving will be best positioned to allocate resources efficiently and capture disproportionate value.
Digital transformation remains a decisive competitive differentiator. Recent moves by leading forwarders, including AI-driven rate management platform updates, partnerships focused on supply chain resilience, and proprietary technology systems that enhance tracking and transaction efficiency, demonstrate that technology investment is no longer optional. Similarly, corporate consolidation events underscore the importance of scale, network reach, and integrated service capabilities in a market where clients increasingly demand end-to-end solutions.
For enterprises evaluating market entry, service expansion, partnership formation, or investment targeting, the granular insights contained in this report reduce uncertainty and sharpen strategic focus. The segmentation data clarifies which corridors and verticals offer the most attractive risk-adjusted returns. The competitive analysis identifies where incumbents are strengthening their positions and where gaps may exist for differentiated service models. The dynamics assessment provides the context needed to design cost structures, pricing frameworks, and contingency plans that withstand volatility.
Next Steps for Intelligence-Driven Strategy
Accessing the complete dataset, segmentation breakdowns, and competitive profiles allows decision-makers to move from high-level awareness to specific, actionable planning. The full version of this market research includes detailed revenue projections, mode-level and region-level performance analysis, end-use industry demand drivers, company-specific strategic profiles, and a comprehensive overview of the industry events and regulatory developments shaping near-term market behavior.
For organizations seeking to strengthen their positioning in the global freight forwarding market, this research provides the evidence base required to make confident strategic choices in 2026 and beyond. Explore the complete market intelligence to uncover the segmentation insights, competitive benchmarks, and forward projections that will inform your next round of strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide International Freight Forwarding Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


