



PW Consulting: High Power CW Laser Market Surges to $3.4B in 2025, Projected to $6.02B by 2032

Strategic Intelligence for the High-Power CW Laser Era: Why 2026 Demands Precision Market Intelligence
The industrial landscape of 2026 is defined by an uncompromising demand for precision, throughput, and energy efficiency. At the heart of this transformation lies the continuous-wave (CW) high-power laser sector—a market that has evolved from a niche manufacturing enabler into a critical infrastructure component for global production ecosystems. As automation accelerates and material processing requirements grow increasingly complex, decision-makers across industrial manufacturing, semiconductor packaging, and emerging technology sectors face a critical imperative: move beyond superficial trend tracking and ground capital allocation, R&D roadmaps, and supply chain strategies in rigorously validated market intelligence.
Our recently published Worldwide High Power CW Laser Market research delivers exactly that foundation. Spanning a comprehensive historical baseline from 2020 through 2025 and extending a structured forecast horizon to 2032, this study transforms fragmented industry signals into a cohesive strategic narrative. For executives, investors, and engineering leaders navigating the 2026 operating environment, the report serves not as a static reference document, but as a dynamic decision-support framework calibrated to the velocity of technological adoption and competitive realignment.
The Macro Trajectory: Sustained Expansion Anchored in Industrial Realities
Market momentum in the high-power CW laser space is no longer speculative; it is quantifiable, structural, and increasingly non-linear. Drawing on validated historical revenue tracking and forward-looking econometric modeling, the research documents a clear trajectory of expansion. Starting from an established base in 2020, the market has consistently advanced through 2025, crossing significant descriptive milestones that reflect both capacity expansion and deepening application penetration. Looking ahead, the forecast window through 2032 projects a sustained compound annual growth rate of 8.5 percent, measured in USD millions. This growth rate is not an artifact of optimistic modeling; it is anchored in observable adoption curves across metal fabrication, battery manufacturing, additive processes, and precision industrial marking.
For strategic planners, the implication is straightforward: the high-power CW laser market is entering a phase where scale advantages, technological differentiation, and regional supply chain positioning will dictate competitive outcomes. The forecast horizon to 2032 provides a multi-year lens that aligns with typical capital equipment procurement cycles, facility expansion timelines, and technology refresh schedules. Executives who integrate this trajectory into their 2026 planning will be better positioned to time capacity investments, negotiate long-term supply agreements, and anticipate shifts in customer demand before they become visible in quarterly order books.
Worldwide High Power CW Laser Market
Navigating Market Concentration and Competitive Realignment
Scale alone does not guarantee strategic advantage in a market characterized by concentrated leadership and rapidly evolving technological boundaries. The research captures a highly structured competitive environment, with the top three participants commanding a combined share of approximately 56.4 percent and the top five collectively representing over 72 percent of total market revenue. This concentration signals mature competitive dynamics, where incumbents leverage manufacturing scale, application engineering depth, and system-level integration to defend positioning, while challengers and regional specialists pursue targeted differentiation in cost structure, beam quality, or application-specific optimization.
Understanding these dynamics requires more than a leaderboard view. The report dissects how established players balance diversified product portfolios with focused high-margin offerings, how regional manufacturing footprints influence cost competitiveness and logistics resilience, and how strategic partnerships, channel relationships, and vertical integration shape go-to-market effectiveness. For 2026 decision-making, this competitive intelligence translates directly into actionable planning: it informs benchmarking exercises, identifies potential partnership or acquisition targets, highlights whitespace opportunities in underserved application segments, and clarifies where pricing pressure is likely to intensify versus where technology premium positioning remains defensible.
CW DFB Laser Diode Market
Structural Partitioning: Technology, Application, and Regional Interplay
A market of this scale cannot be understood through aggregate figures alone. The research maps the underlying structural partitions that drive demand creation, pricing behavior, and technology roadmapping. Across the laser technology spectrum, the study differentiates performance trajectories, cost curves, and adoption velocity among fiber-based architectures, CO2 platforms, solid-state and disk configurations, and direct diode solutions. Each architecture carries distinct implications for beam delivery, thermal management, maintenance complexity, and end-use suitability, and the report translates these technical attributes into commercial relevance for procurement teams, systems integrators, and technology planners.
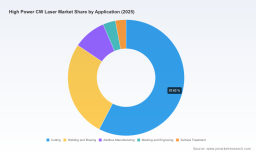
On the application side, the analysis isolates the demand drivers that are reshaping purchasing priorities. Cutting processes continue to anchor a substantial portion of high-power CW laser deployment, reflecting their centrality to metal fabrication, sheet processing, and high-volume manufacturing. Welding and brazing applications represent a parallel growth axis, increasingly influenced by battery assembly requirements, automotive lightweighting initiatives, and aerospace structural joining demands. Additive manufacturing, marking and engraving, and surface treatment applications each contribute distinct volumes and margin profiles, and the report delineates how these segments interact with regional industrial policies, automation investment cycles, and quality-certification requirements.
Regional demand distribution further complicates the strategic picture. The research examines how manufacturing capacity, local automation adoption rates, industrial policy incentives, and supply chain regionalization influence market pull across major geographic corridors. Rather than presenting static share tables, the report contextualizes regional behavior within broader macroeconomic and industrial transformation trends, enabling readers to assess where localized production strategies, export-oriented supply positioning, or regional partnership models will yield the strongest return on commercial engagement in 2026 and beyond.
Tactical Intelligence for 2026 Decision-Making
High-level trajectory and structural analysis are necessary, but rarely sufficient for operational planning. The report is engineered to bridge strategic overview and tactical execution. It provides procurement and engineering leaders with framework-level insights into technology selection criteria, including guidance on when fiber-based solutions dominate, where diode or solid-state alternatives offer compelling tradeoffs, and how beam quality, power stability, and back-reflection resilience influence application suitability for reflective or thermally sensitive materials.
For supply chain and operations executives, the study addresses material dependency considerations and production scalability constraints. It traces how specialized semiconductor and optical raw material dynamics, including regional supply concentration and spot price volatility observed in recent periods, intersect with manufacturing continuity planning. The report also incorporates regulatory and safety compliance requirements that shape design, qualification, and maintenance processes for high-power systems, emphasizing that thermal management complexity and non-linear optical effects demand specialized engineering expertise and rigorous process controls. These factors directly influence total cost of ownership, service network requirements, and vendor evaluation criteria.
Commercial and go-to-market teams will find actionable frameworks for positioning, segmentation, and partnership strategy. The research outlines how application-specific value propositions differ across cutting, welding, additive, and surface treatment contexts, and how system-level integration, service availability, and performance guarantees influence buyer decision-making. By aligning market structure with commercial execution pathways, the report equips teams to refine pricing architectures, prioritize addressable segments, and design channel strategies that match the realities of regional demand and competitive intensity.
Recent Developments Reshaping the Competitive Frontier
The 2026 operating environment is being actively reshaped by product launches, sampling programs, and recognition events that signal where technology leadership is concentrating. Recent industry activity underscores this momentum. In early 2026, leading fiber laser developers showcased compact high-power single-mode sources with tightly controlled beam quality metrics, earning industry recognition for packaging efficiency and industrial usability. These exhibitions and awards are not merely ceremonial; they signal commercial readiness, validate performance claims, and often precede accelerated adoption in precision cutting and welding workflows where beam consistency directly impacts process yield.
Simultaneously, adjacent high-power CW developments are expanding the addressable context beyond traditional industrial processing. Sampling programs for high-power CW sources targeting AI datacenter and co-packaged optics applications indicate a broadening demand ecosystem, where optical power requirements, linewidth control, and fabrication scalability on advanced substrate lines are becoming commercially relevant. Early-stage production timelines and initial revenue expectations tied to these initiatives illustrate how high-power laser technology is feeding into next-generation infrastructure and photonics architectures, creating cross-sector demand linkages that traditional industrial laser markets did not previously capture.
Additional recent introductions in high-efficiency CW sources with stringent linewidth and wall-plug efficiency targets further reflect the industry-wide push toward energy optimization and integration compatibility. Together, these developments demonstrate that the high-power CW laser market is not a closed industrial loop; it is a convergent technology platform where manufacturing, photonics, and infrastructure demands increasingly interact. The report synthesizes these signals into a coherent view of where near-term commercial activity is likely to concentrate and which performance benchmarks are becoming table stakes for competitive participation.
Why This Research Matters for 2026 Strategy
The strategic value of this market research lies in its integration of macro trajectory, structural partitioning, competitive positioning, and near-term industry signals into a single, decision-ready framework. For 2026, that integration matters because the cost of misreading market direction is rising. Capital deployed into misaligned technology platforms, capacity added without clear regional demand justification, or supply agreements negotiated without visibility into concentration dynamics and raw material risk can quickly erode competitive positioning. Conversely, organizations that anchor their planning in validated market structure, realistic growth trajectories, and application-specific demand drivers can time investments more effectively, negotiate from a position of informed confidence, and identify differentiation pathways before competitors lock them in.
The report is designed to support precisely that informed confidence. It equips leadership teams with the context needed to evaluate technology roadmaps against realistic adoption curves, to assess competitive vulnerability and opportunity across regions and applications, and to align procurement, manufacturing, and commercial strategies with the structural realities of a high-growth, technically demanding market. It also provides the analytical discipline required to separate transient market noise from durable demand shifts, a distinction that becomes increasingly critical as automation, electric vehicle manufacturing, aerospace additive requirements, and emerging photonics applications collectively reshape purchasing priorities.
Direction for Deeper Engagement
This overview establishes the analytical foundation and strategic relevance of the study, but the full market intelligence required for definitive 2026 planning resides in the complete research deliverable. The underlying segmentation detail, regional demand mapping, application-specific volume and revenue context, technology performance comparisons, and company-level profiling are structured to support granular scenario modeling, vendor evaluation, and investment prioritization. Accessing the complete report enables decision-makers to move from directional understanding to precise, actionable intelligence tailored to their operational footprint, technology roadmap, and commercial objectives.
For executives and strategy teams seeking to align 2026 capital allocation, product positioning, and supply chain planning with the trajectory of the worldwide high-power CW laser market, the full research offers the depth, structure, and forward visibility required to act with confidence. The market is expanding, concentrating, and converging across industrial and infrastructure applications; the organizations that navigate this environment successfully will be those that replace assumption with evidence, and direction with detail.
For detailed analysis of this topic, please visit the official page: Worldwide High Power CW Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


