



PW Consulting: RF Chip Inductors Market Hits $1.79B in 2025, 7.5% CAGR to 2032

Navigating the RF Chip Inductors Landscape: Strategic Intelligence for the 2026–2032 Cycle
Executive Perspective
The RF chip inductor market is entering a phase of disciplined expansion where volume growth, technological specificity, and supply chain resilience must be managed simultaneously. Based on our Worldwide RF Chip Inductors Market research, the sector is projected to move from approximately USD 1,794.5 million in 2025 to around USD 2,977.2 million by 2032, reflecting a compound annual growth rate of 7.5 percent. This trajectory is not merely a function of broader electronics demand. It is being redefined by high-frequency communication architectures, vehicle intelligence mandates, and the material and geopolitical pressures that now shape component sourcing decisions.
For senior leaders, procurement heads, product strategists, and investors, the market story is no longer about whether RF chip inductors matter. The question is where value will concentrate, how competitive positioning will shift, and which decisions made in 2026 will determine margin and optionality through the end of the decade. This article previews the strategic logic behind our latest study and explains how its structure supports high-stakes planning without exposing the granular intelligence that gives competitive advantage to paying stakeholders.
Why 2026 Is a Defining Planning Year
A Market Framework Built for Decision-Making
Any useful market study for 2026 must do more than present a forward revenue curve. It needs to connect historical behavior, structural demand drivers, and near-term market friction into a single operational lens. Our research framework was designed with that intent. The historical base from 2020 through 2025 provides a migration path that shows how the RF chip inductor market has consistently expanded across technology cycles, product generations, and regional manufacturing shifts. That history is valuable precisely because it exposes the pattern of acceleration and consolidation that often repeats in passive component markets when new communications standards and automotive electronics requirements converge.
From a planning perspective, the forecast window from 2026 through 2032 is where early decisions compound. Because the sector is moving toward roughly a USD 2.98 billion revenue envelope by 2032, even modest changes in sourcing strategy, qualification lead times, or technology mix can translate into meaningfully different cost positions and time-to-market outcomes. Our report translates that macro path into a structured environment where leadership teams can test assumptions around demand timing, component allocation, and portfolio prioritization rather than reacting to market signals after they have already reshaped the supply base.
Importantly, this study is built to support decisions at multiple levels of granularity. Executives can use it to validate top-down market direction, while operations and engineering teams can use its segmentation logic to think through technology choice, application exposure, and regional sourcing implications. The objective is not simply to describe the market, but to provide a reusable analytical scaffold that can inform product roadmaps, supplier negotiations, and capital allocation conversations throughout the forecast period.
What the Study Covers: From Market Structure to Execution
Segmentation Logic That Maps to Operational Reality
The research is organized around the dimensions that matter most to actual sourcing, design, and commercialization decisions. Rather than offering a single aggregate narrative, the report breaks the market into type, application, and region in a way that reflects how buyers evaluate trade-offs among performance, form factor, qualification burden, and cost.
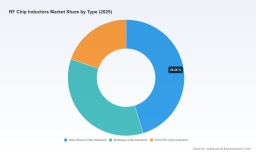
On the product side, the study examines how wire-wound, multilayer, and thin-film chip inductor technologies differ in the contexts where they are most relevant. Each technology pathway carries distinct implications for high-frequency performance, miniaturization, manufacturing complexity, and qualification requirements. Instead of treating these categories as static labels, the report ties them to application needs and supply characteristics so that engineering and procurement teams can interpret them as strategic choices rather than catalog options.
The application perspective is equally practical. Communication-related devices, automotive electronics, industrial and IoT systems, and consumer electronics plus other end-use contexts each place different demands on RF chip inductors. Some prioritize high-frequency stability and noise management, others prioritize durability under vehicle-grade qualification regimes, and still others depend on cost-compressed volume delivery. By analyzing the market through application lenses, the study helps readers understand where demand intensity is structurally stronger and what that means for capacity planning, supplier dependencies, and launch timing.
RF Inductors Market
Regional analysis completes the picture by linking market size distribution to sourcing architecture and manufacturing footprint considerations. In practice, geography is inseparable from risk, lead time, logistics, and qualification strategy. The report situates regional dynamics within the broader supply chain environment so that decision-makers can assess not just where demand is concentrated, but where production, trade exposure, and input vulnerabilities intersect.
Competitive Positioning and the Shape of the Supply Base
Concentration, Differentiation, and the Players That Matter
Market structure is one of the most actionable elements of the study because it reveals where bargaining power, innovation tempo, and qualification advantage tend to reside. The RF chip inductor sector is characterized by a moderately concentrated competitive field, with the top five participants accounting for a substantial share of activity and the top three representing nearly half of the market. That level of concentration is significant. It suggests that while multiple suppliers remain available, strategic relationships, technical differentiation, and reliability credentials increasingly shape sourcing outcomes.
The report profiles a broad set of established and region-specific participants whose product footprints illustrate the competitive logic of the market. Japanese manufacturers such as Murata Manufacturing, TDK Corporation, and Taiyo Yuden continue to occupy prominent positions in multilayer and high-frequency RF inductor offerings, with product development emphasis on high-Q performance, miniaturization, and communication- and vehicle-relevant use cases. Murata, for example, commercialized its LQP02HQ_Z2 high-Q RF chip inductor series in a very compact form factor for in-vehicle communication devices, bringing AEC-Q200 qualification into mass production.
In the United States, suppliers including Bourns, Coilcraft, Vishay Intertechnology, Gowanda Electronics, and API Delevan illustrate the range of specialization available in the market. Bourns has advanced multiple multilayer chip inductor series built around advanced multilayer technology and monolithic construction, targeting high-frequency performance, compact size, and strong self-resonant frequency characteristics for RF and mobile applications. Coilcraft contributes high-performance RF inductor and magnetic component expertise oriented toward RF, microwave, and high-frequency signal processing environments. Vishay and Gowanda extend the competitive field with multilayer and wire-wound approaches as well as ceramic core solutions aimed at demanding RF, power, military, and medical requirements. API Delevan rounds out this group with RF inductors tuned for high-frequency analog circuits, signal processing, RFID, GPS, and radar applications, including qualified and custom options.
Worldwide RF Chip Inductors Market
European participation is represented by Würth Elektronik, whose RF inductor and passive component portfolio supports signal and communications applications across high-frequency chip inductor designs. Meanwhile, Taiwan-based suppliers such as Walsin Technology, ABC ATEC, and Chilisin Electronics, along with Shenzhen Sunlord Electronics in China, reflect the increasingly important role of regional manufacturers in RF inductor supply, spanning wire-wound ceramic chips, multilayer RF inductors, LTCC-based products, and broader communications-related components.
These company profiles are not included as marketing directories. They are used to show how product strategy, application targeting, and technology selection differentiate suppliers in a market where specifications, qualification records, and delivery reliability often matter as much as headline price. The report also tracks recent company-level moves so readers can connect competitor actions to broader market momentum. The recent product launches and commercialization milestones captured in the study demonstrate how the competitive field is actively responding to miniaturization, high-frequency performance, and automotive-grade requirements in parallel.
Market Dynamics: Materials, Regulation, and Risk Asymmetry
Why Structural Pressures Are Now Central to Strategy
No market study for 2026 can treat pricing and supply as background variables. In the RF chip inductor space, raw material behavior and regulatory direction are becoming core drivers of cost structure and availability. Early 2026 has already seen rising silver and copper costs interacting with strong AI, electric vehicle, and industrial demand, producing structural price adjustments across multilayer chip inductors and related passive components. Copper price movement on the London Metal Exchange has moved materially above late-2025 averages, feeding directly into inductor production economics. At the same time, ferrite core supply has tightened, extending delivery cycles for certain models and slowing inductive component production in some contexts.
These pressures create a risk asymmetry that decision-makers cannot afford to overlook. When input costs rise and lead times elongate, the cost of late planning increases as well. Buyers that rely on reactive sourcing are more exposed to allocation constraints, spot pricing, and qualification delays. Organizations that anticipate these dynamics can protect margins through design flexibility, dual qualification, inventory policy adjustment, and more deliberate supplier coordination. The report integrates these material and supply dynamics so that procurement and engineering teams can evaluate not only what the market size trajectory implies, but also what it will cost to access supply reliably.
Regulatory direction adds another layer of strategic relevance. EU RoHS and WEEE directives continue to influence the adoption of recyclable and low-toxicity materials in chip inductor production, reinforcing the idea that compliance is increasingly tied to material selection and manufacturing process choices. At a geopolitical level, Europe’s dependence on China for rare earth elements and high-purity ferrites remains a critical vulnerability, with export controls on materials such as gallium and certain rare earths classified as high supply risk. This context matters for any organization evaluating regional sourcing strategies or long-term supply resilience because it shows that component availability is no longer determined by factory output alone. It is also shaped by trade policy, material concentration, and the broader regulatory environment.
Strategic Applications of the Research for 2026 Decision-Making
From Intelligence to Action
The real value of this study lies in the decisions it helps organizations make more confidently. The report is intended to support:
- Portfolio and technology roadmapping decisions by linking RF chip inductor types to application requirements and future demand trajectories
- Sourcing and supplier strategy by clarifying where competitive concentration, specialization, and regional dynamics shape access and negotiation leverage
- Cost and risk planning by incorporating material price behavior, supply tightness, and regulatory shifts into scenario-based thinking
- Market entry, expansion, or partnership evaluation by identifying where demand intensity and technology needs are most pronounced
- Investment and capability prioritization by showing how market growth is distributed across application and technology pathways rather than treating growth as a monolith
In practice, these applications often converge. A product team may need to decide whether a design should emphasize one inductor technology over another; a sourcing leader may need to assess whether current supplier coverage is sufficient under tightening material availability; and a strategy group may need to evaluate whether regional exposure creates unacceptable risk in the context of trade and material controls. The study is structured to support all three discussions with a consistent evidence base.
How to Use This Intelligence Without Guesswork
Accessing the Full Analytical Depth
The preview above reflects the strategic architecture of the report, but many of the most useful analytical outputs are designed for users who need full segmentation context, competitive benchmarking, and forward-looking scenario support. The complete study goes beyond narrative to provide the structured detail that teams require for supplier scoring, demand modeling, risk assessment, and executive alignment.
Because the RF chip inductor market is being shaped simultaneously by technology differentiation, application growth, material cost pressure, and geopolitical supply exposure, the margin between good planning and reactive planning is widening. Organizations that understand the direction of travel early can align product development, procurement, and investment decisions before the market redistributes advantage.
To benefit from the complete assessment, including the detailed segmentation findings, company-level competitive analysis, and forecast-supported planning tools, we invite you to access the full Worldwide RF Chip Inductors Market research. The published report is designed to give leadership teams the depth they need to act with precision in 2026 and to build resilience through the 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide RF Chip Inductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


