



PW Consulting: Global Rubella Treatment Market to Reach $1.60B by 2032, Growing at 3.62% CAGR

Strategic Horizons: Navigating the Global Rubella Treatment Landscape Through 2032
Executive Overview
The global landscape for rubella treatment and prevention is undergoing a subtle but significant transformation. As public health priorities shift towards strengthening immunization infrastructure and addressing regional coverage gaps, understanding the commercial dynamics of this market is critical for stakeholders across the pharmaceutical value chain. Our latest research, the Worldwide Rubella Treatment Market analysis, offers a comprehensive examination of the sector, projecting trends from the base year 2025 through 2032. This article serves as an strategic preview, outlining the macro-economic forces and competitive intelligence that will define decision-making in the coming years.
For industry leaders, investors, and public health partners, the sheer volume of data can be overwhelming. The key is not just access to numbers, but the contextual interpretation of what those numbers mean for supply chain resilience, regulatory strategy, and product development pipelines. This report is designed to bridge that gap, moving beyond surface-level statistics to provide actionable intelligence on how the market evolves amidst varying healthcare policies and manufacturing capabilities.
Market Trajectory and Growth Dynamics
The historical trajectory of the rubella treatment market reflects the broader success of global vaccination initiatives. From 2020 to 2025, the market demonstrated resilience, with revenue climbing from approximately $1045.2 million to $1251.0 million. This growth underscores the sustained demand for both prophylactic vaccines and supportive care medications necessitated by routine immunization schedules and outbreak management protocols.
Looking forward to the forecast period of 2026 to 2032, the market is expected to maintain a steady upward trajectory. Analysts project the overall market size to grow at a Compound Annual Growth Rate (CAGR) of 3.62%. By 2032, the total revenue is anticipated to reach $1604.6 million. This growth is not merely a continuation of past trends but is driven by specific structural factors, including the expansion of public health programs in emerging economies and the introduction of technologically advanced vaccine delivery systems.
However, growth is not linear. The forecast period accounts for potential fluctuations based on supply chain stability and regulatory milestones. For instance, the market size is projected to experience slight adjustments in the near term, stabilizing before accelerating again towards the end of the decade. This nuanced projection allows strategists to model cash flows and investment returns with greater accuracy, accounting for both the steady demand in mature markets and the higher volatility in developing regions.
Strategic Implications of Market Concentration
Understanding the competitive intensity is vital for new entrants and established players alike. The market exhibits a moderate to high level of concentration. Data indicates that the top three companies command a significant portion of the market share, while the top five firms collectively hold a substantial majority of the revenue. This concentration suggests that while the market is accessible, competitive barriers exist in terms of regulatory approval, manufacturing scale, and established distribution networks.
For companies looking to penetrate this space, the strategy often involves differentiation through delivery technology or targeting specific underserved geographic segments. For incumbents, the focus remains on maintaining coverage rates and navigating the complex landscape of public procurement and reimbursement policies.
Segmentation Analysis: Treatment Modalities and Channels
The market is fundamentally segmented by treatment type, end-user, and region. While specific percentage splits are detailed in the full report, the broader categories reveal where value is being generated.
- Treatment Types: The landscape is dominated by preventive measures, specifically MMR (Measles, Mumps, and Rubella) and MMRV vaccines. These combination vaccines represent the largest share of revenue, reflecting their status as the primary tool for rubella eradication. Supportive medications constitute a secondary but essential segment, addressing symptom management when infection occurs. Hyperimmune globulins represent a specialized, smaller segment utilized in specific high-risk scenarios.
- End-User Channels: Distribution flows primarily through institutional channels. Hospitals and public health centers are the predominant recipients of rubella-related products, driven by national immunization programs and outbreak response protocols. Retail pharmacies play a supporting role, often handling follow-up doses or private sector vaccinations. The balance between public procurement and private consumption varies significantly by region.
The interplay between these segments is critical. For example, advancements in vaccine thermostability could reduce cold-chain reliance, thereby impacting the cost structures for public health centers in regions with logistical challenges. Similarly, shifts in reimbursement policies regarding supportive medications can alter demand patterns within hospital versus retail segments.
Competitive Landscape and Key Players
The rubella treatment market features a mix of global pharmaceutical giants and specialized biotechnology firms. The competitive environment is shaped by intellectual property, manufacturing capacity, and regulatory approvals in key markets such as the United States, Europe, and Asia Pacific.
Worldwide Buruli Ulcer Treatment Market
Merck & Co., Inc., based in the United States, remains a cornerstone of the market with its M-M-R II vaccine, a live attenuated virus vaccine widely used for active immunization. Their portfolio strength lies in established distribution networks and long-term safety data. GlaxoSmithKline (GSK), headquartered in the United Kingdom, is another major force, offering Priorix for MMR prevention. GSK has recently been active in regulatory engagements, securing FDA approvals for Priorix formulations, which reinforces their position in the Western market.
Sanofi Pasteur, headquartered in France, supplies MMR vaccines including Trimovax, contributing to combination formulations used in various national schedules. In the emerging market space, the Serum Institute of India stands out as a major producer of affordable MMR vaccines like Tresivac, playing a pivotal role in global prevention programs where cost is a primary constraint. Similarly, PT Bio Farma in Indonesia manufactures rubella-containing vaccines for domestic use and export, supporting national immunization efforts in Southeast Asia. The Shanghai Institute of Biological Products in China develops and produces local MMR formulations, catering to the large domestic demand.
A notable innovation dynamic comes from Micron Biomedical Inc. in the United States. Their focus on needle-free delivery technology represents a potential shift in how measles and rubella vaccines are administered, aiming to improve coverage in global immunization programs by overcoming needle-stick injuries and reducing waste.
Recent Regulatory and Development Activity
Recent developments highlight the pace of innovation and regulatory activity in this sector. In March 2026, GlaxoSmithKline received FDA approval for Priorix (Measles, Mumps and Rubella Vaccine, Live) for active immunization against rubella in individuals 12 months of age and older. This follows earlier regulatory updates in November 2025, signaling continuous optimization of their portfolio.
Additionally, while not a direct rubella treatment, the broader antiviral landscape is seeing activity. In February 2026, NanoViricides, Inc. filed an Orphan Drug Designation application with the FDA for NV-387 as a potential treatment for measles. While this targets a related paramyxovirus context, it holds exploratory antiviral research relevance for rubella-like infections, indicating a potential long-term shift towards therapeutic options beyond vaccination, though currently, no specific antivirals are approved for rubella.
Industry Dynamics: Regulation, Reimbursement, and Manufacturing
The operational environment for rubella treatment is heavily influenced by regulatory frameworks and public health policies. Currently, there are no specific antiviral drugs approved for the treatment of rubella infection. Management relies primarily on supportive care, including rest, hydration, and symptom relief with antipyretics such as acetaminophen. This clinical reality cements the importance of the vaccine segment over the therapeutic drug segment.
Research into broad-spectrum antivirals continues. Peer-reviewed studies have noted that nitazoxanide has demonstrated in vitro inhibition of rubella virus replication. However, these findings remain exploratory, and the compound is not approved for this indication. This gap between research potential and clinical approval defines a key risk and opportunity area for future R&D investment.
Reimbursement structures are heavily tied to public health mandates. MMR vaccines targeting rubella are included in routine childhood immunization schedules supported by public health programs globally. High coverage targets are set by the WHO and national governments, ensuring a stable baseline demand. However, changes in public funding or shifts in policy prioritization could impact procurement volumes for manufacturers reliant on government contracts.
Manufacturing complexities also pose strategic challenges. The production of live attenuated rubella vaccines requires specific cell culture systems and strict cold-chain logistics to maintain viability during distribution. These requirements are particularly challenging during global immunization campaigns in regions with infrastructure limitations. Innovations that improve thermal stability or simplify logistics are therefore highly valued strategic assets.
Regional Dynamics and Strategic Focus
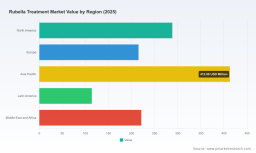
Regional variations define the opportunity set for the forecast period. The Asia Pacific region represents a significant volume of activity, driven by large populations and ongoing immunization expansion efforts. North America and Europe maintain steady demand driven by mature healthcare systems and booster programs, while the Middle East, Africa, and Latin America offer growth potential linked to international aid and regional health infrastructure development.
Strategists must consider that while overall market size grows, the velocity of growth differs by region. Factors such as local manufacturing capabilities, reliance on imported vaccines, and the stability of public health funding play crucial roles. For instance, regions with strong domestic manufacturing may see different margin structures compared to those reliant on global supply chains.
Strategic Value of the Full Report
While this overview provides a high-level snapshot of the market's direction, the full Worldwide Rubella Treatment Market report offers the granular intelligence required for precise planning. Decision-makers need access to detailed segmentation splits, historical data correlations, and proprietary forecasts that go beyond aggregated statements.
The complete study delves into specific regional revenue contributions, detailed treatment type breakdowns, and end-user distribution metrics that are essential for market entry strategies and capacity planning. It also provides deep-dive profiles of key competitors, analyzing their recent developments, strategic moves, and potential vulnerabilities.
Worldwide Rubella Treatment Market
Furthermore, the full report contextualizes the regulatory noise into actionable insights. It analyzes how recent FDA approvals, orphan drug filings, and international health guidelines interplay to create both barriers and openings for business development. Understanding the nuances of cold-chain requirements versus emerging needle-free technologies, for example, requires the detailed technical analysis provided in the full document.
For organizations aiming to optimize their portfolio, secure supply chains, or identify partnership opportunities in the rubella treatment space, the comprehensive data set is indispensable. It transforms macro trends into micro-level tactics, enabling stakeholders to navigate the 2026-2032 period with confidence.
We invite industry leaders and strategic planners to access the full report to unlock these critical insights. The landscape is evolving, and the margin between success and missed opportunity lies in the depth of understanding. Let the data guide your next strategic move.
For detailed analysis of this topic, please visit the official page: Worldwide Rubella Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


